Key points:
-
- Yesterday’s national accounts confirmed a disturbing reality for Australia: immigration-led population growth but flat-lined living standards.
-
- There are two main ways a nation can grow its economic pie (total output and income): (1) POPULATION growth (mainly via immigration): more people producing the same old output per person; and (2) PRODUCTIVITY growth: higher output and income per person by working smarter.
-
- POPULATION growth (mainly immigration) puts pressure on housing, traffic, services, prices. But PRODUCTIVITY growth means the existing population working smarter in better paying, more satisfying jobs, and rising living standards.
-
- Australia’s economic growth has been increasingly reliant on POPULATION growth rather than PRODUCTIVITY growth. Unfortunately, the problem has been building for many years, and will take many years to remedy.
-
- Productivity growth (and overall economic growth) have been in steady DECLINE in Australia for several decades through ALL governments.
-
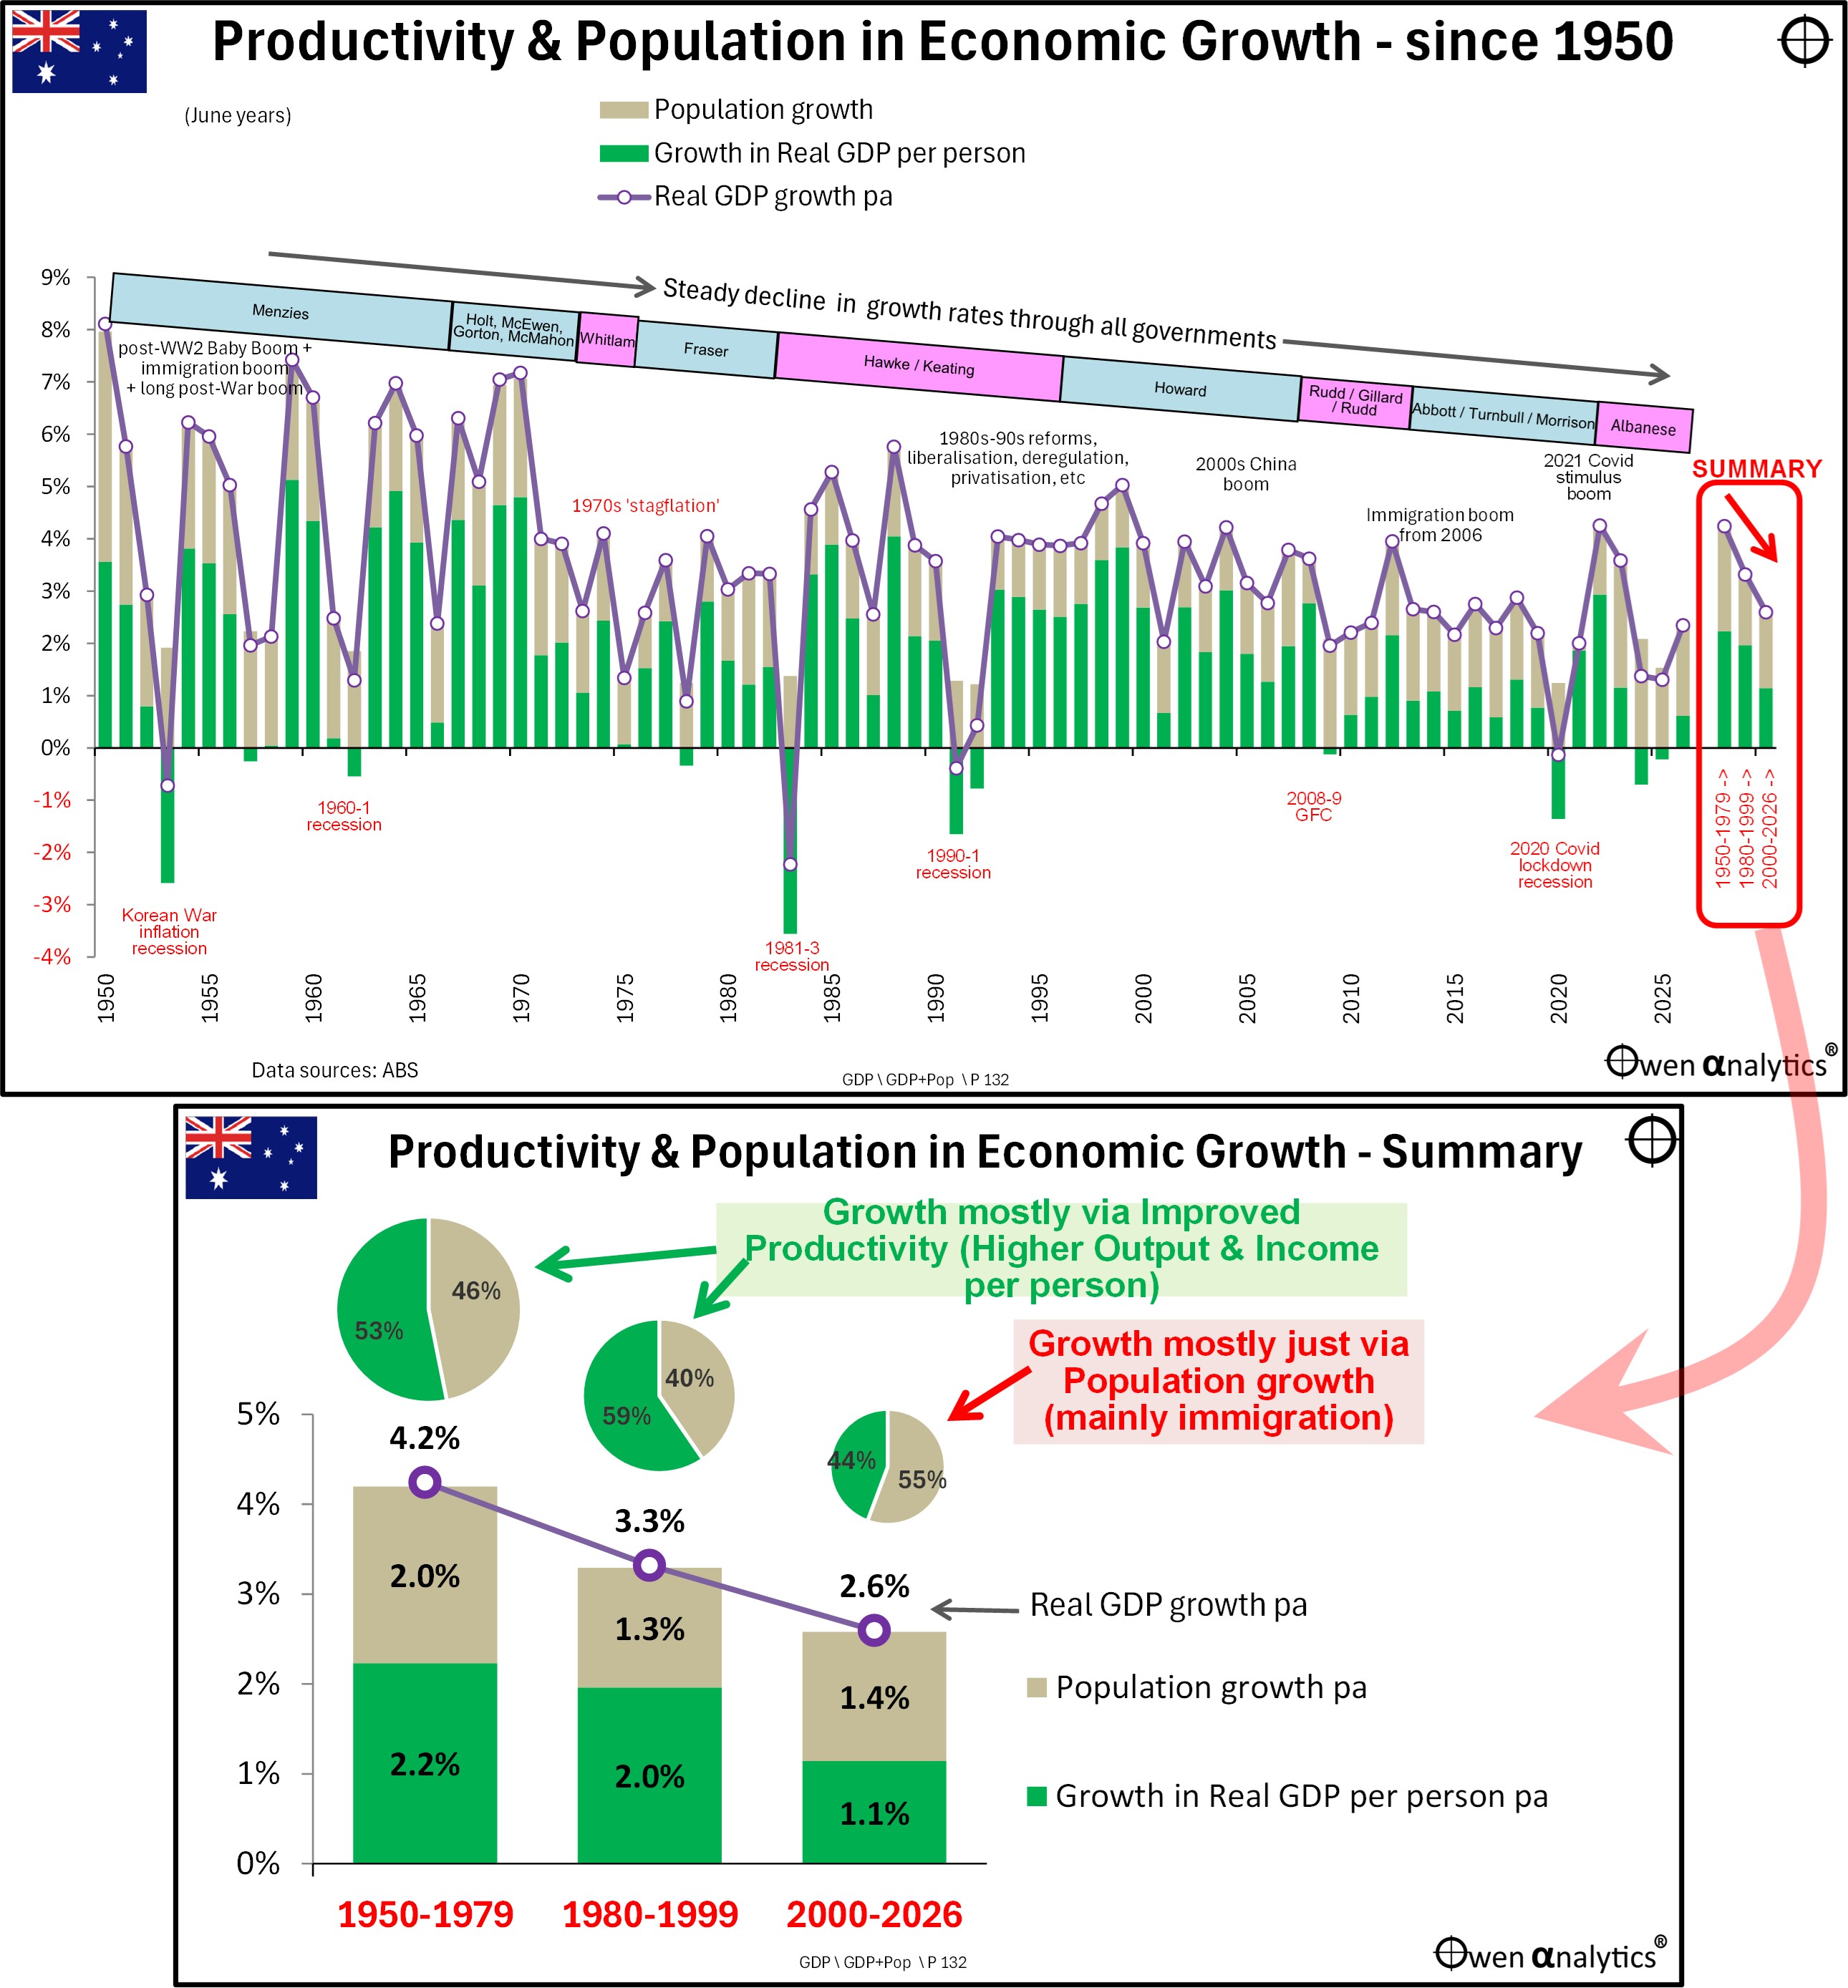
- Today’s main chart shows annual growth in real GDP (total output and income) since 1950, broken into the two main sources of growth: population growth (grey bars) and productivity growth (green). The lower chart highlights (a) the steady decline in overall growth rates, and (b) the rising reliance on population growth.
-
- The post-WW2 boom of the 1950s & 1960s (Lib/Nat) was a period of high productivity growth, but this waned in the 1970s stagflation (Labor plus Lib/Nat).
-
- The next period of productivity gains was kick-started by the Hawke/Keating reforms in the mid-1980s to early 1990s (Labor), and continued in the early Howard years (Lib/Nat) until the early 2000s.
-
- However the past 20 years under both sides of politics have seen almost no serious productivity-boosting reforms, and indeed several reversals and unwinding of reforms (eg industrial relations, re-regulation, protectionism, industry policy, tax).
-
- Rather than make painful and politically risky reforms to increase business investment and worker productivity, it is far easier, lazier and less politically risky to simply grow the economic pie by importing more people instead.
-
- The problem is that increased voter populism today is not only making productivity-boosting reforms even more prohibitive and unlikely, all three sides of politics (Labor, Lib/Nat, and now One Nation) are bowing to political pressure to CUT immigration, which has been the primary source of economic growth this century.
-
- This lower growth future will challenge Australian investors’ long-held assumptions of steadily rising corporate revenues, profits and dividends that have been based primarily on high immigration.
Greetings fellow investors!
Australia’s economic growth has been increasingly reliant on population growth rather than real reforms to improve productivity and living standards. This is not a new trend. It has been deteriorating for several decades through governments of all types.
Growth in a country’s overall economic pie comes from two main sources:
(a) growth in population (more people producing, earning, and spending the same per person as last year); and
(b) growth in output, income, and spending per person – which drives growth in living standards
Australia has (and has had for two centuries) the highest population growth rate of any country outside of Africa, and is still the most sparsely populated country on earth (even if you include just the arable land)! See -
· Australia’s extraordinary population-led growth
Today’s story highlights the fact that Australia’s economic growth has been increasingly reliant on population rather than real reforms to improve productivity and living standards.
Population -v- Productivity growth
Of these two components of growth, the second is far more important and desirable, because it contributes to higher living standards per person, through higher levels of incomes and wealth per person, better schooling, and health care, etc.
On the other hand, population growth doesn’t increase living standards per person. Economic growth through population growth alone just means more traffic, more crowded schools and hospitals, more pollution, more waste, more construction, more noise.
The problem is that most of Australia’s overall economic growth has come from population growth, rather than productivity growth. It has been getting worse for decades, and it is still getting worse.
Long, slow decline in growth rates
The upper chart above shows annual growth in Australia’s real GDP (purple line) per year since 1950, separated into the two main sources of growth: population growth (grey bars), and growth in GDP per person (green bars).
The most obvious feature is the steady decline in economic growth rates in Australia over many decades (punctuated briefly by recessions).
This steady decline has persisted through ALL governments from both sides of politics, as indicated on the chart. Some governments have been better than others of course.
Without going into politics, the first observation would be that all governments of all persuasions, from the very first years of British colonial settlement, have generally been pro-growth, pro-resource exploitation, pro-immigration, pro-individual freedoms, and (mostly) pro-business.
We tend to take these things for granted here, but other countries have not had the same success. Australia’s prosperity has not just been resource abundance - there are plenty of resource rich countries that are economic basket cases.
Summary of shrinking growth rates since 1950
The lower chart expands the Summary section in the right section of the upper chart.
Rates of overall economic growth in Australia have declined substantially - from 4.2% per year in the 1950s to 1970s, down to 3.3% per year in the 1980s and 1990s, and now down to just 2.6% per year so far this century.
Critically, more than half of the growth in the total economic pie is now just coming from population growth – the politically easy option.
Post-WW2 boom
During the second half of the twentieth century, Australia experienced the highest rates of growth per person (growth in living standards) since the first half of the nineteenth century.
(For the full story since 1788 see - Australia's shrinking growth - mostly just population growth (7-Mar-2024)
The high rates of growth in the post-WW2 boom in the 1950s and 1960s ended in the ‘stagflation’ of the 1970s, a global phenomenon made worse by government policies here (on both sides).
1980s-1990s economic reforms
High growth rates were lifted once again after the radical economic reforms under Hawke/Keating (Labor). These included floating the dollar, removal of capital controls, deregulating banking, opening banks to foreign competition, privatising government businesses, reducing tariff protection, improving competition laws, productivity-based enterprise bargaining, tax reforms, central bank independence, compulsory ‘super’.
In the Howard years (Lib/Nat) the Hawke/Keating reforms were extended but much of the windfall gains from the early 2000s China/mining boom were squandered on middle class welfare, which have been politically near impossible to wind back (although some of the gains were ‘banked’ by paying off the national debt and setting up the Future Fund).
Prospects for reforms to raise productivity and living standards?
The nearly two decades since the Global Financial Crisis have been a whirlwind of revolving door governments that have not demonstrated much ability to think beyond the daily news cycle or the next election or leadership challenge.
The current governments (Federal and State) are clearly moving backward toward centralised controls, reduced workplace flexibility, increased union power, industry-wide strikes, productivity-free wage rises, subsidising and picking ‘winners’. Governments are squandering temporary windful mining gains on expanding government spending and rapidly increasing government debts, rather than paying them off.
Population growth easier than hard reforms
Genuine economic reforms are painful and politically risky.
Deep and radical government reforms in the past have only been made when the nation faced nightmare conditions – like persistent double-digit inflation (1970s), or 20%+ unemployment & income reductions (1890s, 1930s), or military attacks on our soil (1940s). Making far-reaching and unpopular decisions was an urgent necessity, not an option.
Compared to traumatic conditions in the past that triggered deep and lasting policy changes, conditions today are very mild. Life is just too good. Inflation, interest rates and unemployment rates are relatively low (historically), commodities prices are high and bumper export revenues are flooding in.
Instead of painful reforms, to keep the headline numbers growing - like jobs numbers and company revenues and profits, it is much easier to just increase the population (mostly via immigration).
Even after two centuries of experiencing the highest population growth rates in the world outside of Africa, Australia is still the sparsest country in the world (even if we include just the arable land). It is still virtually empty!
This vast, sparsely populated rock we live on seems to be packed with enormous reserves of an ever-increasing array of raw materials that other people in other countries want to buy from us, to turn them into useful stuff to sell back to us at hundreds of times the price we got for them in the first place.
The case for high immigration has always been that we need more people to dig up these bountiful natural resources we keep finding in and on our rock, and we need more people to defend the rock!
Populist pressure to radically reduce immigration
The problem is that increased voter populism today (much of which is thinly disguised racism) is not only making productivity-boosting reforms even more prohibitive and unlikely, all three sides of politics (Labor, Lib/Nat, and now One Nation) are bowing to political pressure to CUT immigration significantly, which has been the primary source of economic growth this century.
This lower growth future will challenge Australian investors’ long-held assumptions of steadily rising corporate revenues, profits and dividends that have been based primarily on high population growth.
Food for thought!
‘Till next time – safe investing and stay healthy!
Ashley Owen
No ai. All Human. All original research & analysis.