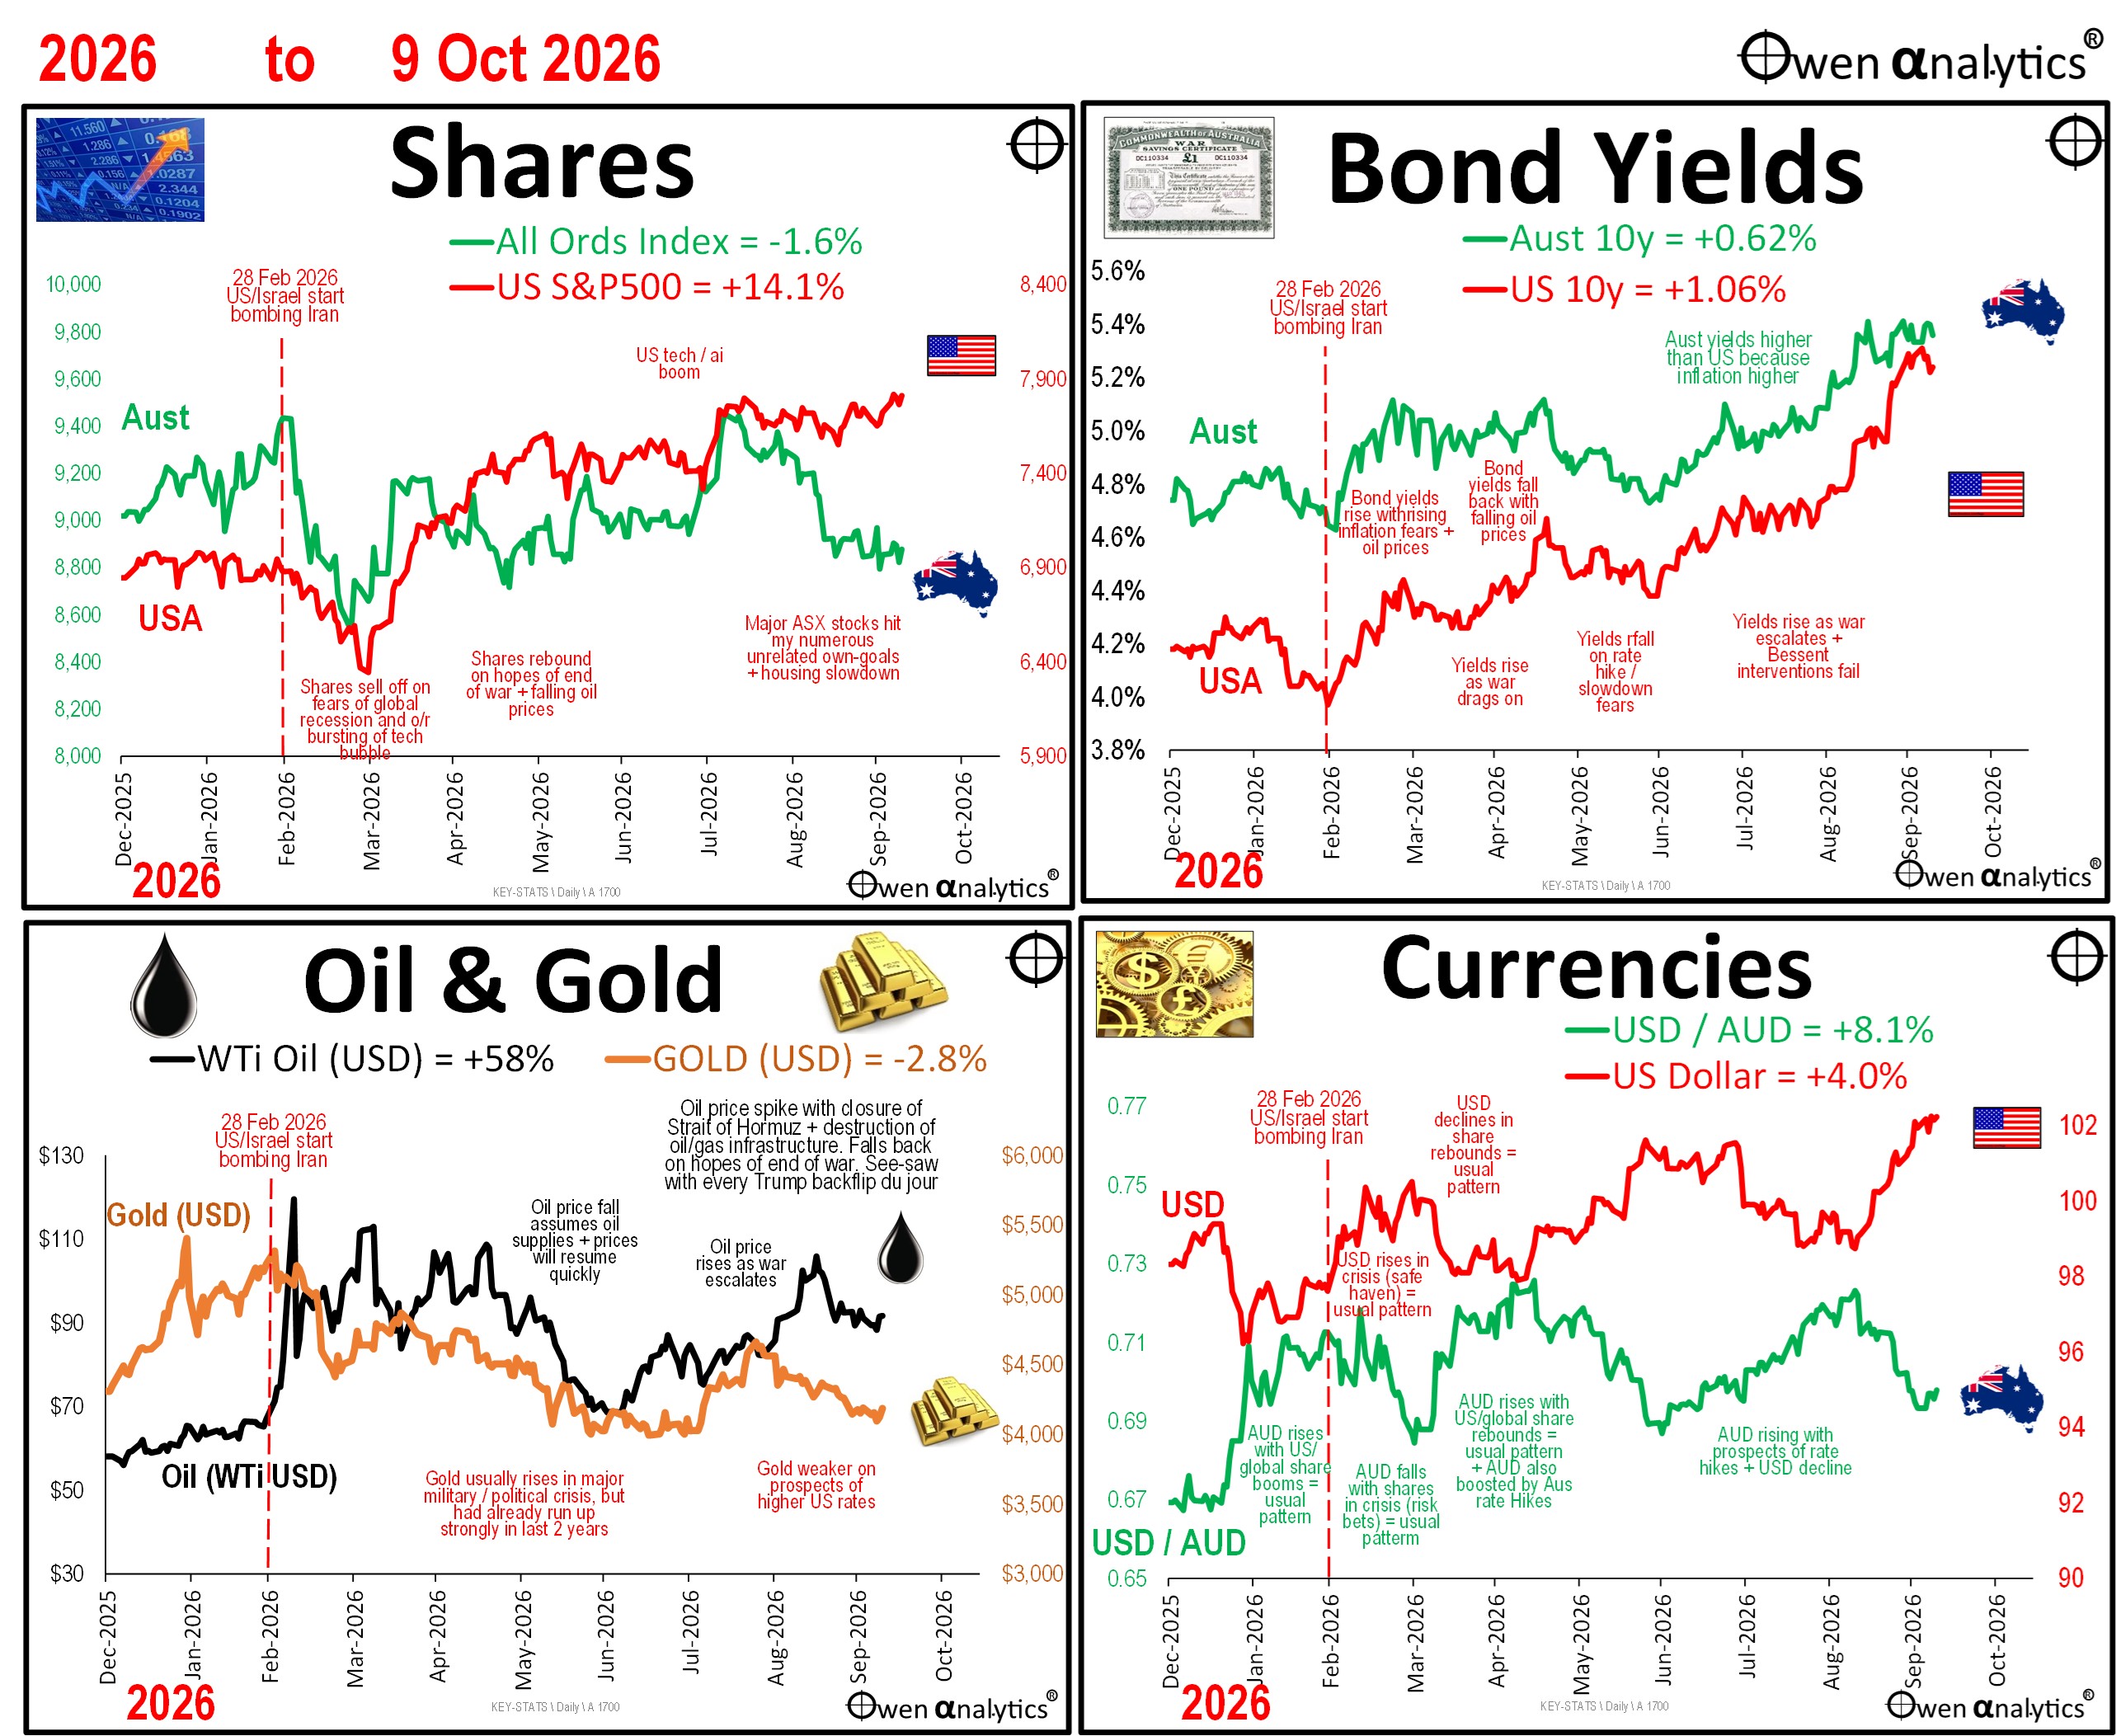
Background - I track and analyse thousands of data points across all markets and asset classes, but the most important barometers and drivers of local and global markets for my day-to-day purposes (answering questions from media & colleagues, and mentoring advisors & portfolio managers in managing their client portfolios and client comms) are the following key items:
- Share markets (Australia & US),
-
-
- the Aussie market as it still anchors most long-term diversified portfolios
-
-
- the US market as it dominates (financial and sentiment) global markets
- Treasury bonds (Aus & US)
-
-
- because fixed rate bonds still make up a sizeable chunk in most long-term diversified portfolios,
-
-
- and because treasury yields reflect expectations of future inflation and interest rates, which directly affect other asset classes including shares, real estate, commodities, currencies.
-
-
- The AUD because it is a ‘risk’ currency, which it ALWAYS falls in general global sell-offs as global (mainly US) investors dump foreign risky assets and retreat to the safety of the US. Conversely, but in general global rebounds and booms, the AUD usually (but not always) rises as foreign investors (mainly US) venture back in.
-
-
- The USD as it is the global reserve currency on which everything else is anchored,
- Oil – because fuel prices filter directly or indirectly into just about every inflation category, and inflation expectations drive interest rate decisions and bond yields, which in turn affect the pricing of all other assets.
- Gold – as it is the original ‘hard currency’ and it is still a good proxy measure for how investors, governments, and central banks are felling about future inflation and political / civil / military unrest and disruptions.
This handy set of four charts track changes in these key markets since the start of 2026, and is my quick go-to daily reference point.
Here’s my latest quick take on the week’s activity on local & global markets for Aussie investors:
Owen’s Market Pulse- 10 Oct 2026: Cracks in the a.i. hyper-hype?
Global headlines during the week were dominated not by Trump’s directionless war on Iran, but by rising bond yields in the US and France. Rising US yields threaten to prick the ai bubble, while rising French yields rekindled memories of the 2010-1 sovereign debt crisis. Neither was enough to prevent US share markets from hitting new all-time highs.
Aussie headlines were dominated by the opportunistic top-of-the-market float of Firmus, the vastly over-hyped and over-priced ai data centre start-up cooked up by jailbird insider trader Oliver Curtis. (He may have done is time, but would you trust him with your money?) There were at least a dozen other red flags besides that. Fortunately sanity prevailed and investors rejected it.
SHARES - The ASX edged up 0.3% for the week (but is still under water this year). Banks were down as house prices continued to slide. Iron ore miners were down with weaker iron ore prices. Oil producers rose with higher oil prices, and Gold miners rose. CSL & Goodman re-gained some lost ground after their recent slides.
US share markets hit new highs during the week. Chip makers Nvidia, Micron, AMD fell but the ‘hyper-scalers’ buying up their chips rose, including Microsoft, Amazon, Alphabet/Google, Telsa, and Palantir the best up 10%.
BONDS - Australian yields kept rising on inflation fears fuelled by out-of-control government spending/debt binges (and Smiling Jim Charmer still in denial). Short rates also edged up further, pointing to more rate hikes ahead.
US bond yields at multi-decade highs dominated headlines. However, I showed that US yields are actually still LOW relative to history, logic, fundamentals, or inflation.
· US 10-year yields ‘soar’ above 5%. Shock Horror! But actually they’re still rather LOW relative to history, logic, fundamentals, and inflation. Get used to it! (27-Sep-2026)
Today’s yields only look high because people have got used to artificially ultra-low yields since the GFC, but that era is over. Rising yields means another bad year for bond markets everywhere. (I have been out of fixed rate bonds since 2021).
OIL – prices rose back above $90 in the US and near $105 in Europe as Trump’s flip-flop ‘deal-or-no-deal’ war or Iran continues with no end in sight.
GOLD – was more or less flat for the week, at around 20% below its January peak. Gold’s attraction has weakened in recent months by rising US interest rates. Gold is touted as a hedge against US debt troubles, but as soon as the interest rate on that debt becomes attractive enough, people suddenly forget their concerns and race in to chase the higher yield! At the right price, greed overtakes fear!
CURRENCIES – The AUD rose 0.7% for the week with the prospect of more RBA cash rate hikes, which suck in capital, raising the exchange rate.
MY TAKE - Despite Trump’s endless war on Iran, I remain relatively positive in the short-term because Trump’s primary immediate goal must be getting fuel prices down to retain MAGA votes in the November mid-terms. Expect a flurry of ‘deals’ to make a US retreat look like an EPIC VICTORY!
But time is running out!
Stay tuned!
‘Till next time – happy investing and stay healthy!