Background - I track and analyse thousands of data points across all markets and asset classes, but the most important barometers and drivers of local and global markets for my day-to-day purposes (answering questions from media & colleagues, and mentoring advisors & portfolio managers in managing their client portfolios and client comms) are the following key items:
Share markets (Australia & US),
o the Aussie market as it still anchors most long-term diversified portfolios
o the US market as it dominates (financial and sentiment) global markets
Treasury bonds (Aus & US)
o because fixed rate bonds still make up a sizeable chunk in most long-term diversified portfolios,
o and because treasury yields reflect expectations of future inflation and interest rates, which directly affect other asset classes including shares, real estate, commodities, currencies.
Currencies (AUD & USD)
o The AUD because it is a ‘risk’ currency, which it ALWAYS falls in general global sell-offs as global (mainly US) investors dump foreign risky assets and retreat to the safety of the US. Conversely, but in general global rebounds and booms, the AUD usually (but not always) rises as foreign investors (mainly US) venture back in.
o The USD as it is the global reserve currency on which everything else is anchored,
Oil – because fuel prices filter directly or indirectly into just about every inflation category, and inflation expectations drive interest rate decisions and bond yields, which in turn affect the pricing of all other assets.
Gold – as it is the original ‘hard currency’ and it is still a good proxy measure for how investors, governments, and central banks are felling about future inflation and political / civil / military unrest and disruptions.
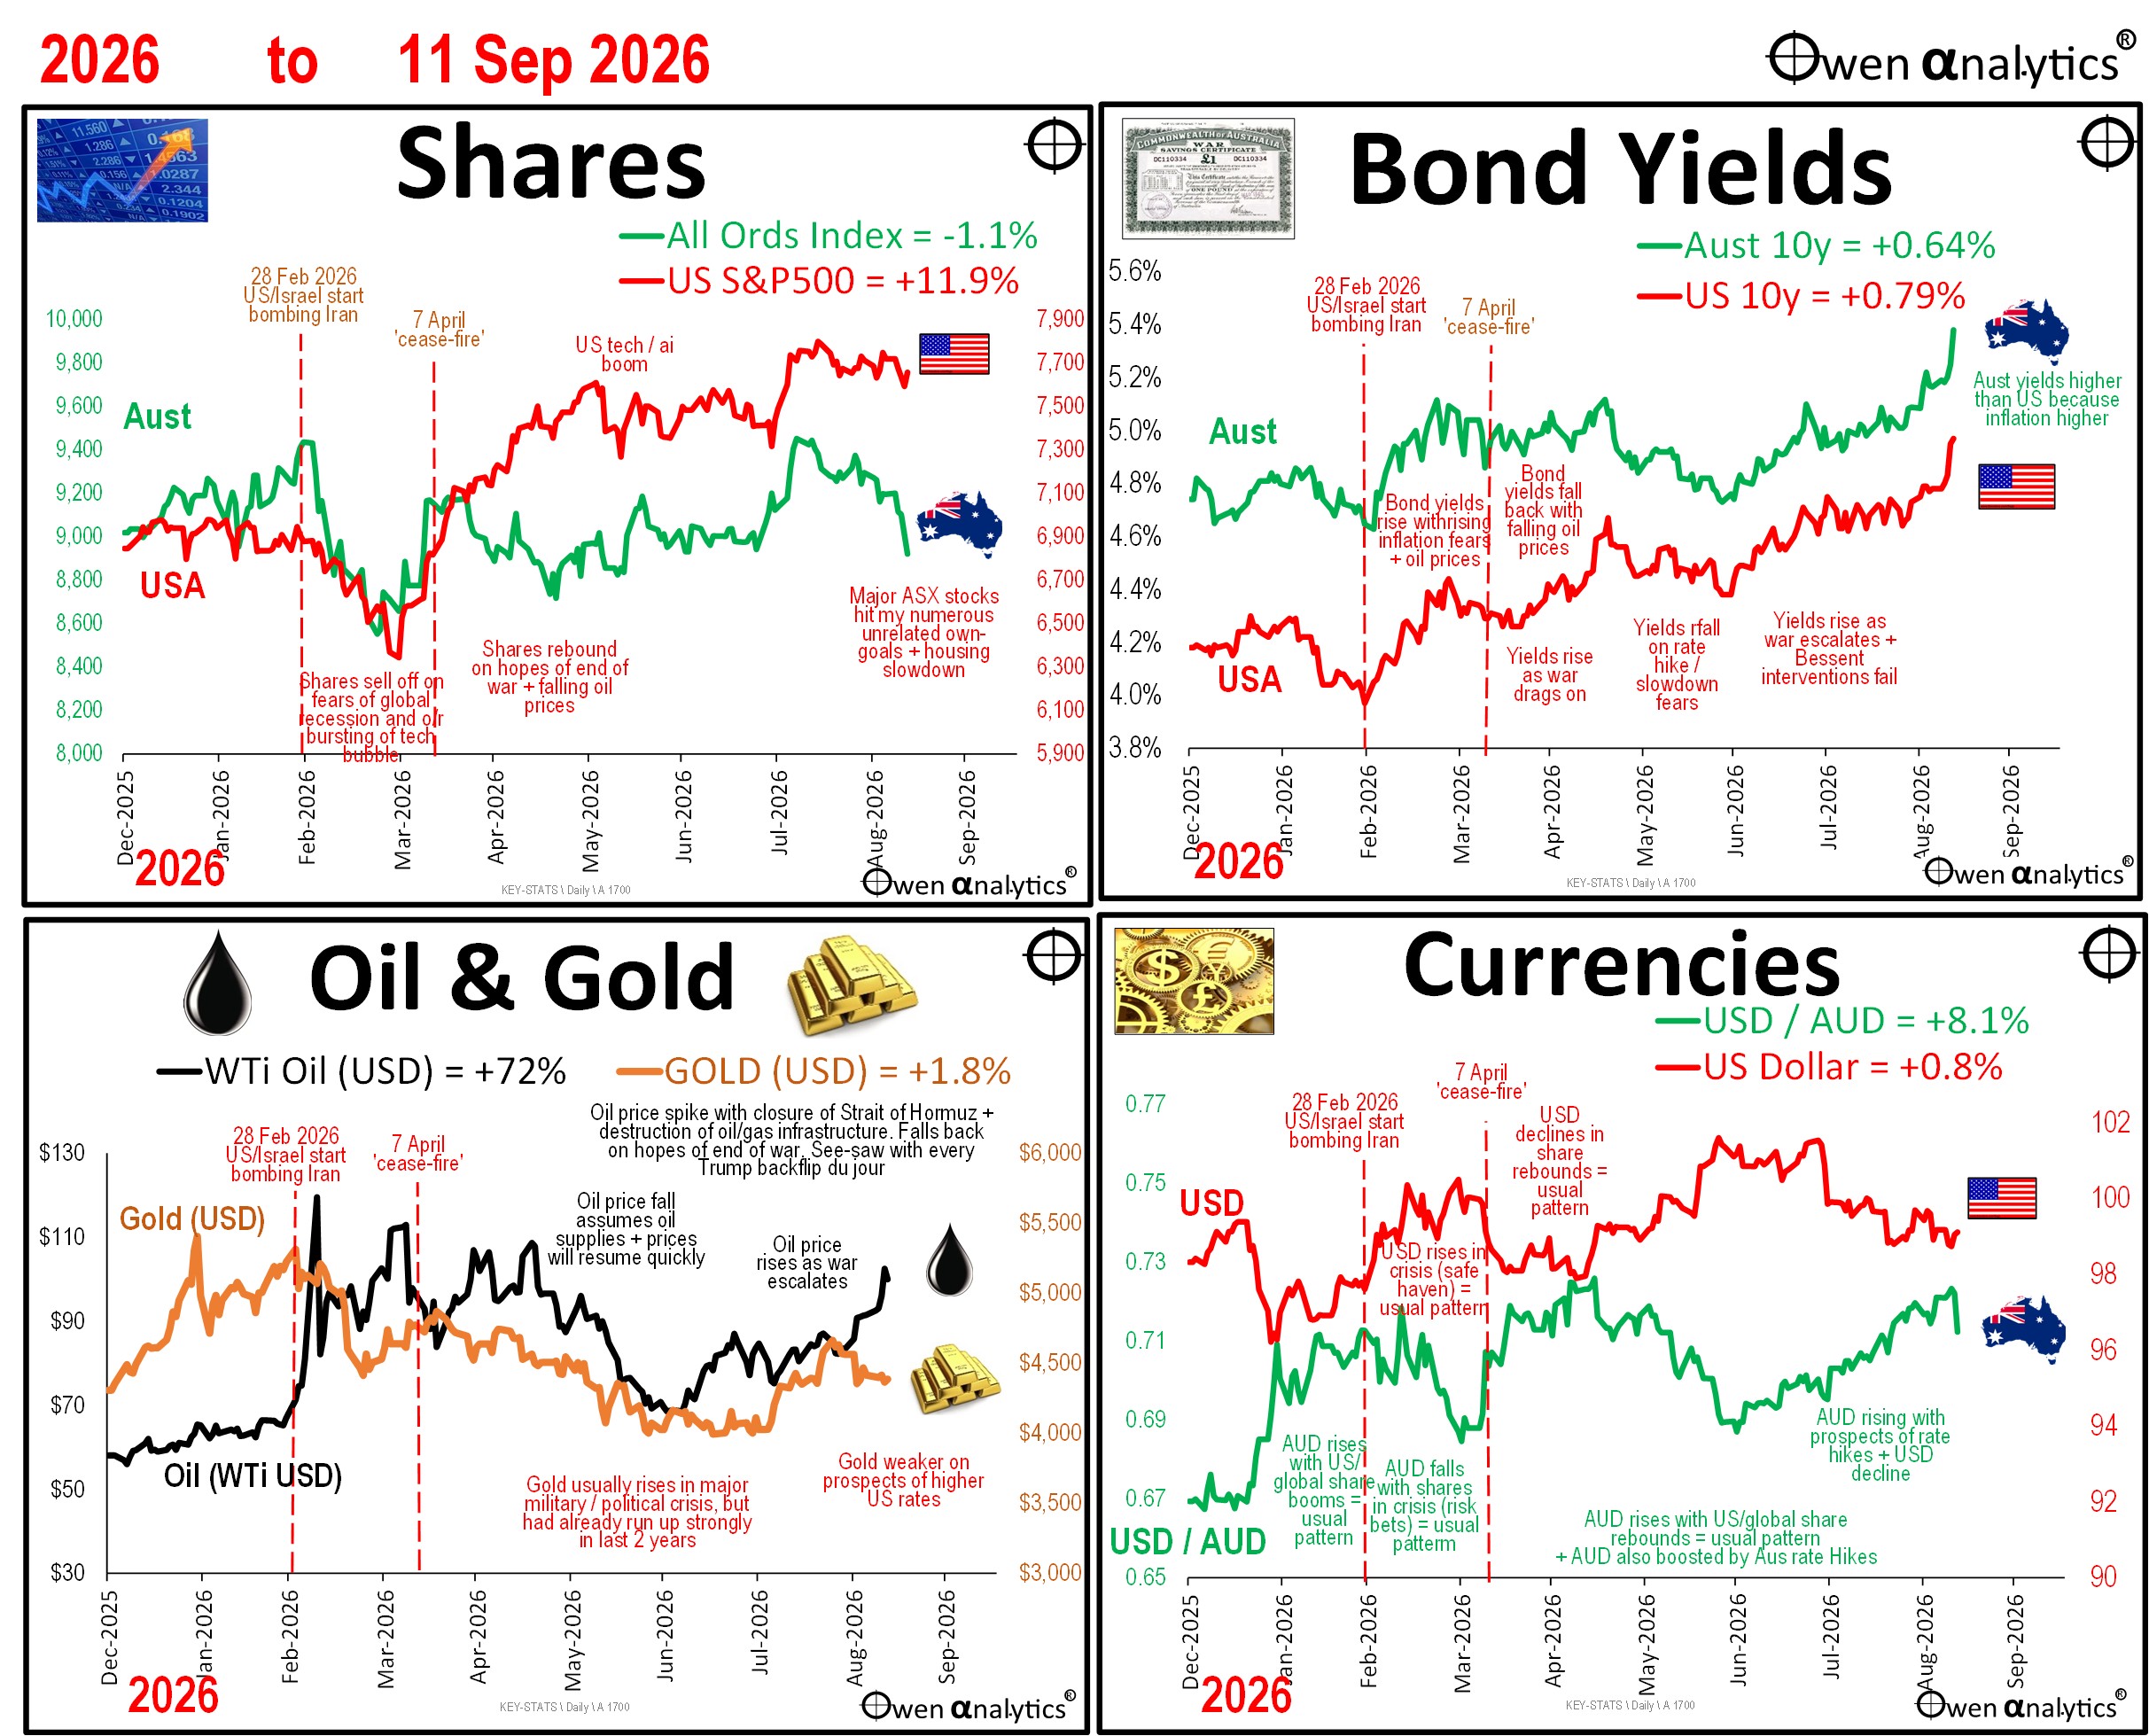
This handy set of four charts track changes in these key markets since the start of 2026, and is my quick go-to daily reference point.
Here’s my latest quick take on the week’s activity on local & global markets for Aussie investors:
Owen’s Market Pulse- 25 July 2026: 11 September 2026: Soaring oil prices & bond yields dent share markets
In a nutshell: Two negative developments this week: (1) Oil prices surged as Trump’s war on Iran veered further out of control, and (2) bond yields soared on rising inflation fears, another failed intervention by US Treasury Secretary Scott Bessent, stubbornly high inflation numbers, and now Trump’s extraordinary promise of a US$5k gift to every American adult citizen if the Republicans win the Senate and House, which will add another $1 trillion to the US debt pile to be serviced and repaid by taxpayers and their kids.
SHARES - The ASX market ended down 3% for the week. All major stocks lost ground except fossil fuel producers, which jumped with oil prices. Banks were down with the continued slide in house prices and lending volumes, plus increased probability of further rate hikes starting to fuel recession fears.
The big iron ore miners fell with iron ore prices. Likewise for gold miners as the gold price fell back a fraction with rising US interest rates. CSL lost some of its recent rebound gains, and Goodman (now an ai/data centre bet) echoed the global ai slide.
US share markets fell by less than a percent in August, but the picture was somewhat mixed. The main negative factors continue to be fears that over-investment in ai infrastructure (data centres & chips) will fail to generate decent returns, plus rising fears of inflation, rising bond yields, fuel prices and prospects of US rate hikes.
Gains in Apple, Meta/Facebook, Tesla and SpaceX were more than offset by falls in chip makers Nvidia and Micron (although AMD was up), along with falls in Microsoft, Amazon, Palantir.
BONDS - Australian yields kept rising for a sixth straight week on inflation fears due to escalating government spending / debt binges (Federal & State) with no sign of restraint or discipline. Short rates also edged up further, pointing to higher rates ahead. Queensland government debt was hit with a credit downgrade, and other troubled states are likely to follow suit.
US bonds also had their worst week since Trump’s tariff tirade in April 2025 as yields also soared to multi-decade highs with government spending / debt / inflation fears outweighing slowdown fears as higher fuel prices drag on spending and confidence. It will be another shocker of a year for bond holders everywhere. (I have had no fixed rate bonds in my own or advised portfolios since 2021.)
OIL – US oil prices (WTI) rose back above $100 (and European Brent prices above $105) for the first time since the start of the US-Iran war, after Iran-backed Houthi rebels in Yemen extended their disruptions to shipping through the Bab el-Mandep Strait (the alternate Red Sea route with the Strait of Hormuz closed).
GOLD – fell back a fraction during the week with prospects of higher interest rates in the US, causing falls in Aussie gold miners.
CURRENCIES – The AUD fell 1% for the week, consistent with its behaviour as a ‘risk’ currency – generally rising and falling with share markets. Upward pressure on the AUD due to rising chances of another RBA rate hike, is being offset by similar rising prospects of a Fed rate hike.
MY TAKE on macro conditions for investment markets: Despite continued entanglements in the US/Iran war, I remain relatively positive in the short-ish-term (lower oil prices, which should support share markets) because Trump’s primary immediate goal must be to do whatever it takes to get fuel prices down in time to retain MAGA votes in the November mid-term elections. My theory is that the closer it gets to November, the more desperate Trump will be to get out of the Middle East. But he must find a way to make it look like an EPIC VICTORY!
He knows he must retain both the House and Senate in order to retain unfettered power in the next two years to execute his agenda to achieve his goal of becoming the greatest leader in the history of the world (in his own mind anyway).
Stay tuned!
‘Till next time – happy investing and stay healthy!
Visit my web site for hundreds of original articles on a wide range of topics for advisers, portfolio managers, and serious long-term investors.
https://www.owenanalytics.com.au/
· All completely free of charge. Free of conflicts. Free of ‘ai’.
· All original research and analysis.
· No ads, No marketing material, No sponsored material at all.
· Not ‘monetised’ in any way. No ‘revenue model’.
· Guaranteed No ‘hot stocks’, No ‘hot tips’.
· Guaranteed No ‘ai’. All human.
Enjoy!