Key Points:
-
-
- SHARES - US share markets fell over the week, mainly on Friday’s strong jobs report reviving fears of further rate hikes. Nasdaq tech stocks were hit particularly hard.
- However the ai boom shifted up another gear with the SpaceX IPO and plans for IPOs for OpenAI and Anthropic to cash in on the crazy retail FOMO frenzy.
- The ASX market went backwards last week. The big banks fell further in the fall-out from the government’s proposed tax hikes to hit housing and share investment, while the big miners were also hit by lower prices for iron ore, copper and gold. Our market will follow the US Friday fall (it always does) when markets re-open for the new week.
- BONDS - Australian yields rose a fraction back up to near 5% on government spending/debt fears, despite rising unemployment. US yields are still hovering around 4.6%, with government spending / debt / inflation fears balancing slowdown fears for the US economy as higher fuel prices drag on.
- OIL - Oil prices basically essentially follow Trump’s latest tweets / insider trading opportunities about his endless peace ‘deals’ and threats to annihilate civilizations, then his inevitable backdowns and deferrals. WTi rose back above $90 during the week (after last week’s falls) as Trump’s latest deal fell apart (again).
- GOLD - Gold ended the week 4% lower after falling in Friday’s general sell-off.
- CURRENCIES - AUD fell a fraction to 0.7121 USD, consistent with share markets falling. In addition, rising unemployment and the housing slowdown lowered chances of further imminent rate hikes, which would ordinarily attract more money in Australia and push up the dollar.
- USD index rose +1.2% for the week, consistent with share markets falling.
- My most likely scenario is still: – war dragging on, keeping oil prices elevated, bond yields rising, tempered by rate hikes, and hopefully yields not rising sharply enough to trigger major share market sell-off, which is well and truly due. But at least not yet.
- However I still remain relatively positive in the short-term as Trump’s primary immediate goal must be to get fuel prices down in time to retain MAGA votes in the November mid-term elections.
Greetings fellow British colonial subjects - and Happy King’s Birthday!
Yep, a sorry reminder that in this day and age we are still a British colony, with a British Head of State, (a Germanic King!), who’s representative still officially must sign off every piece of ‘Australian’ federal and state legislation, and who’s head is still on ‘Australian’ currency notes and coins.
Wake Up Ostraya!
Anyway - here’s my quick pulse on the global markets for Aussie investors.
(I track and analyse thousands of data points across all markets and asset classes, but the most important barometers and drivers of local and global markets for my purposes are: share markets (Aus & US), treasury bonds (Aus & US), currencies (AUD & USD), oil and gold.)
Here they are from the start of 2026, with key events/dates highlighted:
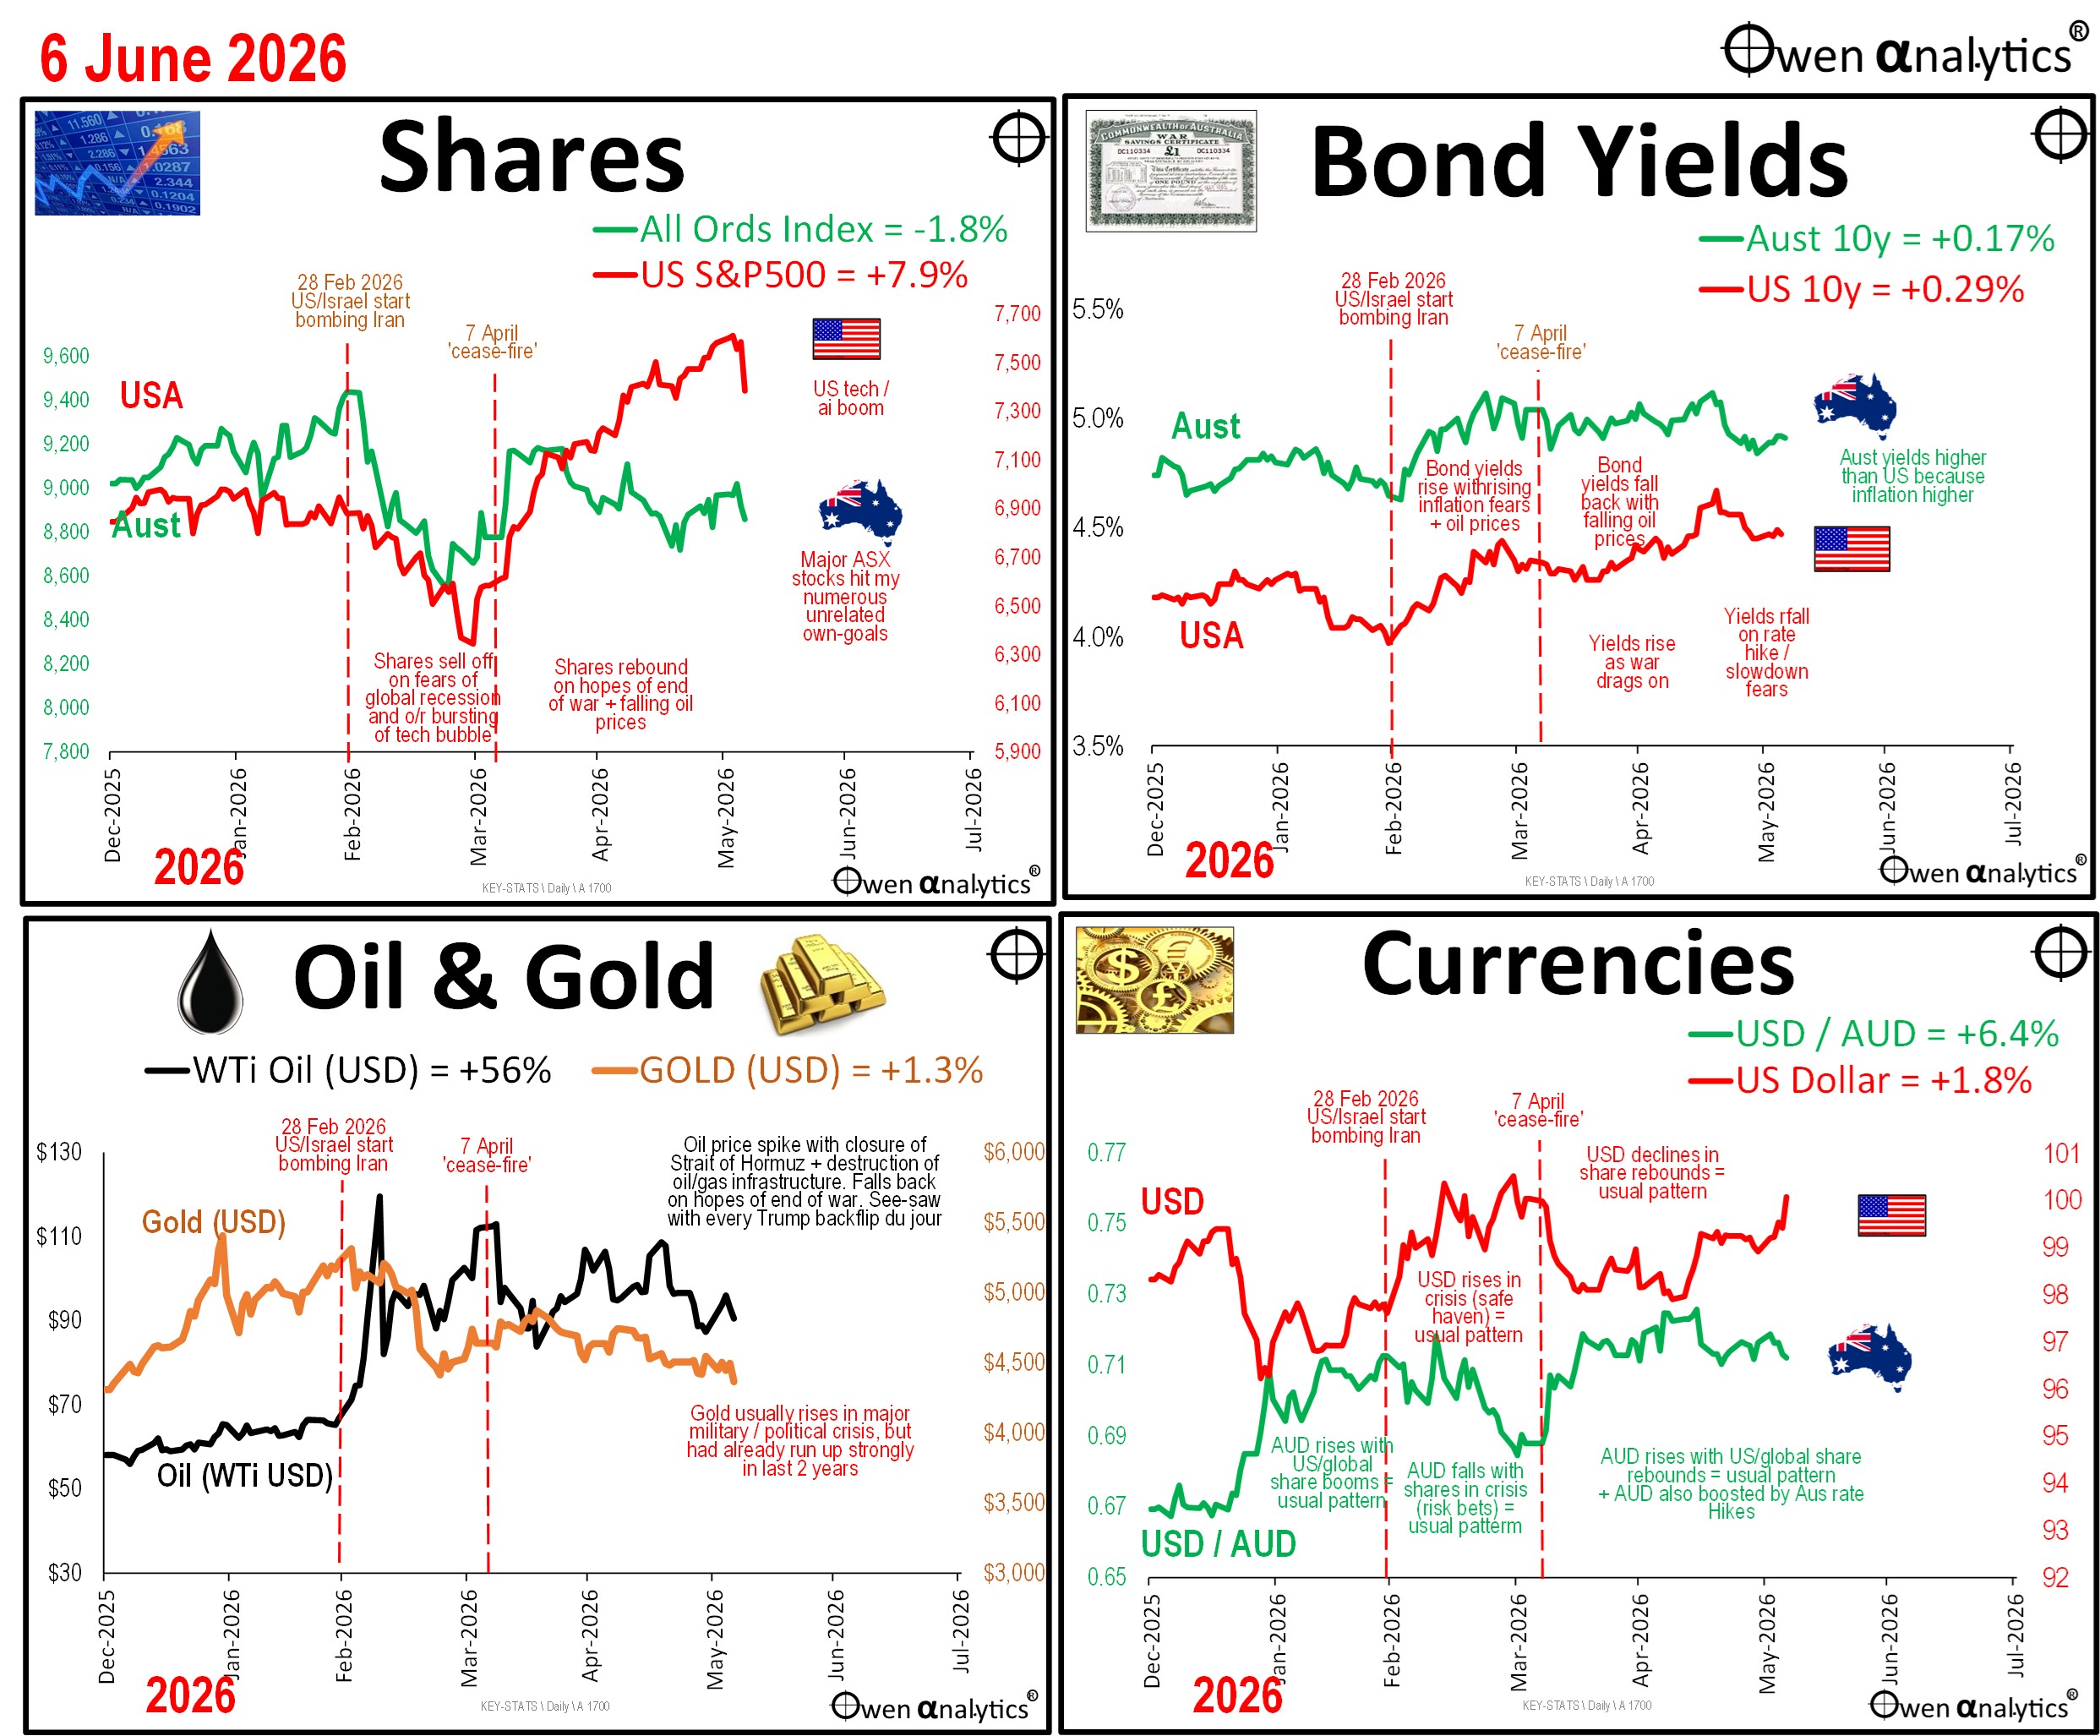
Brief comments on the major markets:
Shares
2026 to date:
-
-
- At the start of the war share markets everywhere sold off sharply. Then, from the beginning of April, shares started to rebound on signs of an early end to the war, and share markets kept rising after the 7 April phoney ‘cease fire’ deal.
- Although the war has dragged on since then, with oil prices remaining high and inflation numbers rising across the world, US share prices have kept rising in the US-led tech / ai / chip boom. The US S&P market has posted 24 new all-time highs for 2026 to date.
- Meanwhile, here in Australia the All Ords has posted only 2 new all-time highs this year. The last one was on 27 Feb before the US/Iran war).
- The ASX market does have some big miners that are benefiting from the global supply disruptions and demand surges, but it has two main problems holding it back. First, it has almost no tech / ai / semiconductor stars. Second, a string of major local stocks across a variety of sectors have been hit by ‘own-goals’ – ie problems of their own making.
- The local health care sector in particular has been a sea of share slumps this year - including: CSL, Cochlear, ProMedicus, ResMed, Sonic. Most of these have been own goals – with aggressive expansion adventures failing to live up to the hype.
- Also hit hard this year have been several former tech stars for the same reason (overly ambitious expansion) plus also the threat of annihilation by ‘ai’ - including: Wisetech, Xero, Seek, CarSales, REA.
- Also own-goals in other majors like Northern Star (gold production problems in the Super Pit).
Latest week:
-
-
- US share markets fell over the week, mainly on Friday after a strong jobs report sparked new fears of further rate hikes. Nasdaq tech stocks were hit particularly hard.
- It has always been my view that tightening monetary policy is going to be one of the main contributing factors / triggers for the crash that ends the current boom.
- The Friday sell-off was enough to cast a shadow over the otherwise frenzied euphoria over the upcoming SpaceX IPO. More on SpaceX below.
- The ASX market went backwards last week. The big banks fell further in the fall-out from the government’s proposed tax hikes to hit housing and business, while the big miners were also hit by lower prices for iron ore, copper and gold. Our market will follow Friday falls in the US market (it always does) when markets re-open for the new week.
Bond yields
2026 to date:
-
-
- Bond yields reflect expectations of future inflation and interest rates.
- At the start of the war, yields started rising in expectation that rising fuel prices would lead to higher general price inflation that would be met with interest rate hikes. After the 7 April ‘cease fire’, yields started falling in expectation of a resolution and lower oil prices.
- However, yields have drifted up again since mid-late April as the war dragged on, the Strait of Hormuz remained largely closed, and oil prices remained high.
- Why are bond yields important? Because rising bond yields mean lower prices and lower returns on fixed rate bonds. This is bad for long-term institutional funds in Australia (including all Big Super funds) and globally, which are stacked full of bonds. In addition, even if you are like me and hold no fixed rate bonds (have not since 2021), rising bond yields almost always trigger sell-offs in other asset classes including share markets and real estate.
Latest week:
-
-
- Australian yields rose a fraction back up to near 5% on government spending/debt fears, despite rising unemployment.
- US yields are still hovering around 4.6%, with government spending / debt / inflation fears balancing slowdown fears for the US economy as higher fuel prices drag on.
- It looks like yet another bad year for bond markets everywhere (and therefore out-performance of my funds as I have been out of fixed rate bonds in my portfolios and advised portfolios since 2021)
Oil
2026 to date:
-
-
- Oil prices shot up at the start of the war, then eased back on hopes of early resolution, but rose again from Mid-April on Iran’s closure of Strait of Hormuz and destruction of oil/gas infrastructure. Prices remain high as the war drags on with no end in sight.
- Elevated energy prices are feeding into inflation numbers rising everywhere, lifting bond yields (and ordinarily should be dampening share markets).
- Why is oil important? Because rising fuel prices filter directly or indirectly into just about every inflation category, and inflation expectations drive interest rate decisions and bond yields, which in turn affect the pricing of all other assets.
- NB: The chart shows ‘West Texas Intermediate’ (WTI) which is the main US price benchmark for oil. Also of interest is ‘Brent Crude’ for Europe (Brent is currently around $5 to $10 above WTI), or ‘Tapis Crude’ for Aian markets traded through Singapore, etc. For me WTi is a pretty good general barometer.
Latest week:
-
-
- Oil prices basically just follow Trump’s latest tweet / insider trading opportunity.
- WTi rose back above $90 during the week (after last week’s falls) as Trump’s latest deal fell apart (again).
Gold
2026 to date:
-
-
- Gold usually rises in major military / political crisis but in this crisis the price action has been subdued, as gold had already doubled in price in the 12 months leading up to the war.
- The biggest buyers of gold in recent years have been central banks, especially in countries non-aligned to the US (who is aligned to the US under Trump?). Rising prices sparked a frenzied retail FOMO-led peak at the end of January this year, but prices fell back early in the war.
- Gold prices have remained relatively flat at around levels seen in the first few weeks of the year.
- The gold price should be kept elevated, and/or rising given:
-
- (a) rising inflation due to high energy prices and possible prices-wages spiral;
- (b) likely continued elevated fuel prices given Trump’s inability to end the war he started;
- (c) possible reluctance of central banks to hike rates to fight inflation; and
- (d) signs of China possibly revisiting plans to invade Taiwan.
- (I put gold in long-term portfolios (my own + advised) a couple of years ago, and it has been the best asset class since then).
Latest week:
-
-
- Gold ended the week 4% lower after falling in Friday’s general sell-off.
Currencies
2026 to date:
-
-
- The US dollar is the global ‘safe haven’ currency (and has been since WW1). The USD almost always rises in general crises (even if the cause of the crisis is the US itself – eg the GFC), as global investors (mainly US) sell risky foreign assets and retreat to the safety of US cash or bonds. To do this they need to sell the foreign currency and buy US dollars, putting downward pressure on foreign currencies and upward pressure on the US dollar.
- Conversely, The US dollar almost always declines during rebounds and general rallies. When global investors (mainly US) are bullish, they venture overseas to buy risky foreign assets. To do this they have to sell US dollars and buy foreign currencies, putting downward pressure on the US dollar and upward pressure on the foreign currencies.
- The Aussie dollar is a ‘risky’ foreign currency, so it ALWAYS falls in general global sell-offs as global (mainly US) investors dump foreign risky assets and retreat to the safety of the US. Conversely, in general global rebounds and booms, the AUD usually (but not always) rises as foreign investors (mainly US) venture back in.
- From the start of the war, the US dollar rose and the AUD fell – as per the usual pattern.
- After the 7 April ‘cease fire’ deal, confidence return (briefly) so the US dollar fell back, and the AUD rose -also the usual pattern. Also boosting the attractiveness of the AUD are the three interest rate hikes here this year.
- However, since the 7 April ‘cease fire’ deal, they have reversed again as hopes for lower oil prices and an end to the war fade – sending the US dollar higher and the AUD lower.
Latest week:
-
-
- AUD fell a fraction to 0.7121 USD, consistent with share markets falling. In addition, rising unemployment and the housing slowdown lowered chances of further imminent rate hikes, which would ordinarily attract more money in Australia and push up the dollar.
- USD index rose +1.2% for the week, consistent with share markets falling.
In other news
The dominant topic of debate in Australia is still Labor’s proposed tax hikes. We are now seeing the impact in the form of slower auction clearance rates and lower house prices as potential buyers hit the Pause button until the tax landscape becomes clearer.
People are coming to realise that the lofty aim of ‘more affordable housing’ sounds good when you say it quickly, but it actually means ‘lower house prices’, and that means disappearing home equity for geared-up mortgagors, and banks requiring top-up security. Hence the fall in bank share prices on fears of rising bad debts.
The longer term impacts are even worse. Labor had two main goals: (1) to help young people buy homes, but the tax changes will discourage housing investment/supply and push up rents and prices further. Goal (2) was to improve intergenerational equity, but the proposed CGT changes will punish young working investors and provide exemptions for older investors including boomer pensioners.
It is a classic case of hasty political decisions driven by blinkered ideology, ignoring basic economics and common sense.
Stay tuned!
‘Till next time – happy investing and stay healthy!
Visit my web site for hundreds of original articles on a wide range of topics for advisers, portfolio managers, and serious long-term investors.
https://www.owenanalytics.com.au/
- All completely free of charge. Free of conflicts. Free of ‘ai’.
- All original research and analysis.
- No ads, No marketing material, No sponsored material at all.
- Not ‘monetised’ in any way. No ‘revenue model’.
- Guaranteed No ‘hot stocks’, No ‘hot tips’.
- Guaranteed No ‘ai’. All human.
Enjoy!
IMPORTANT DISCLAIMERS
This is just my view of the facts as I see them. It is certainly NOT ‘advice’ or a recommendation to buy, hold, or sell any stock or security or fund. My aim is to provide dispassionate information, insights, and informed analysis for portfolio managers and advisers.
As always, investors should take your own time, do your own research, form your own views, and seek professional advice based on your own individual goals, needs and circumstances.
Please read the disclaimers and disclosures below.
Experiences
Director/Principal, Owen Analytics Pty Ltd (current)
Investment Markets Research & Analytics, Portfolio Construction & Management, Corporate Finance, Venture Capital, M&A, and IPOs. Investment Committee membership, consulting to advice firms and financial institutions.
Co-founder & Regular Contributor, Firstlinks (current)
Co-founder of Australia's leading investment and superannuation newsletter and website for industry professionals and investors.
Non-exec Director, Third Link Investment Managers (current)
Leading Australian equities fund-of-funds that donates all management fees to Australian charities. The fund has donated in excess of $21m to a range of Australian chartities since inception in 2008.
Chief Investment Officer, Stanford Brown (past)
Responsible for managing over $2 billion AUM in multi-asset class portfolios and discretionary accounts at a privately-owned advice practice.
Director & Joint CEO at Philo Capital Advisers Pty Ltd (past)
Specialises in investment portfolio construction & management, multi-asset class asset allocation, and global macro strategies.
Check out my full bio here