Key Points:
-
- OVERALL – US/global tech / ai / chip boom back in full swing (at bubble-like pricing levels) despite US/Iran war dragging on, high energy prices, and rising inflation. Primed and due for major correction, just waiting for the trigger/s.
- OIL - prices shot up at the start of the war, then fell briefly on hopes of an early resolution but have remained high as the war drags on through endless Trump announcements, deferrals and backflips.
- Elevated energy prices are feeding into inflation numbers rising everywhere, lifting bond yields (and ordinarily should be dampening share markets).
- SHARES – Despite the war dragging on, oil prices remaining high, and inflation numbers rising across the world, the US share market is back into full boom mode - driven by tech / ai / chips.
- The ASX ordinarily would be dragged up in the boom frenzy, but has been hit a string of own-goals in several major stocks. Plus fall-out from Federal budget tax changes.
- BONDS - Bond yields rising since mid-late April as the war drags on, the Strait of Hormuz remains largely closed, oil prices remain high, and ongoing fears of government spending/debt.
- US Dollar – was declining since early April on hopes of end of war (as per usual pattern for the USD as the global safe haven) but declining as the share boom resumed (also the usual pattern).
- Aussie Dollar – was rising since early April on hopes of end of war (as per usual pattern as a risk currency) but falling in past few days with rising unemployment reducing chances of further rate hikes.
- Gold usually rises in major military / political crisis / but in this crisis the price action has been subdued, as gold had already doubled in price in the 12 months leading up to the war. Gold prices have remained relatively flat at around levels seen in the first few weeks of the year.
- My most likely scenario is still: – war dragging on, keeping oil prices elevated, bond yields rising, tempered by rate hikes, and hopefully yields not rising sharply enough to trigger major share market sell-off, which is well and truly due. But at least not yet.
Greetings all!
Here’s my quick pulse on the global markets for Aussie investors.
(I track and analyse thousands of data points across all markets and asset classes, but the most important barometers and drivers of local and global markets to get a quick snapshot of global conditions are: share markets (Aus & US), treasury bonds (Aus & US), currencies (AUD & USD), oil and gold.)
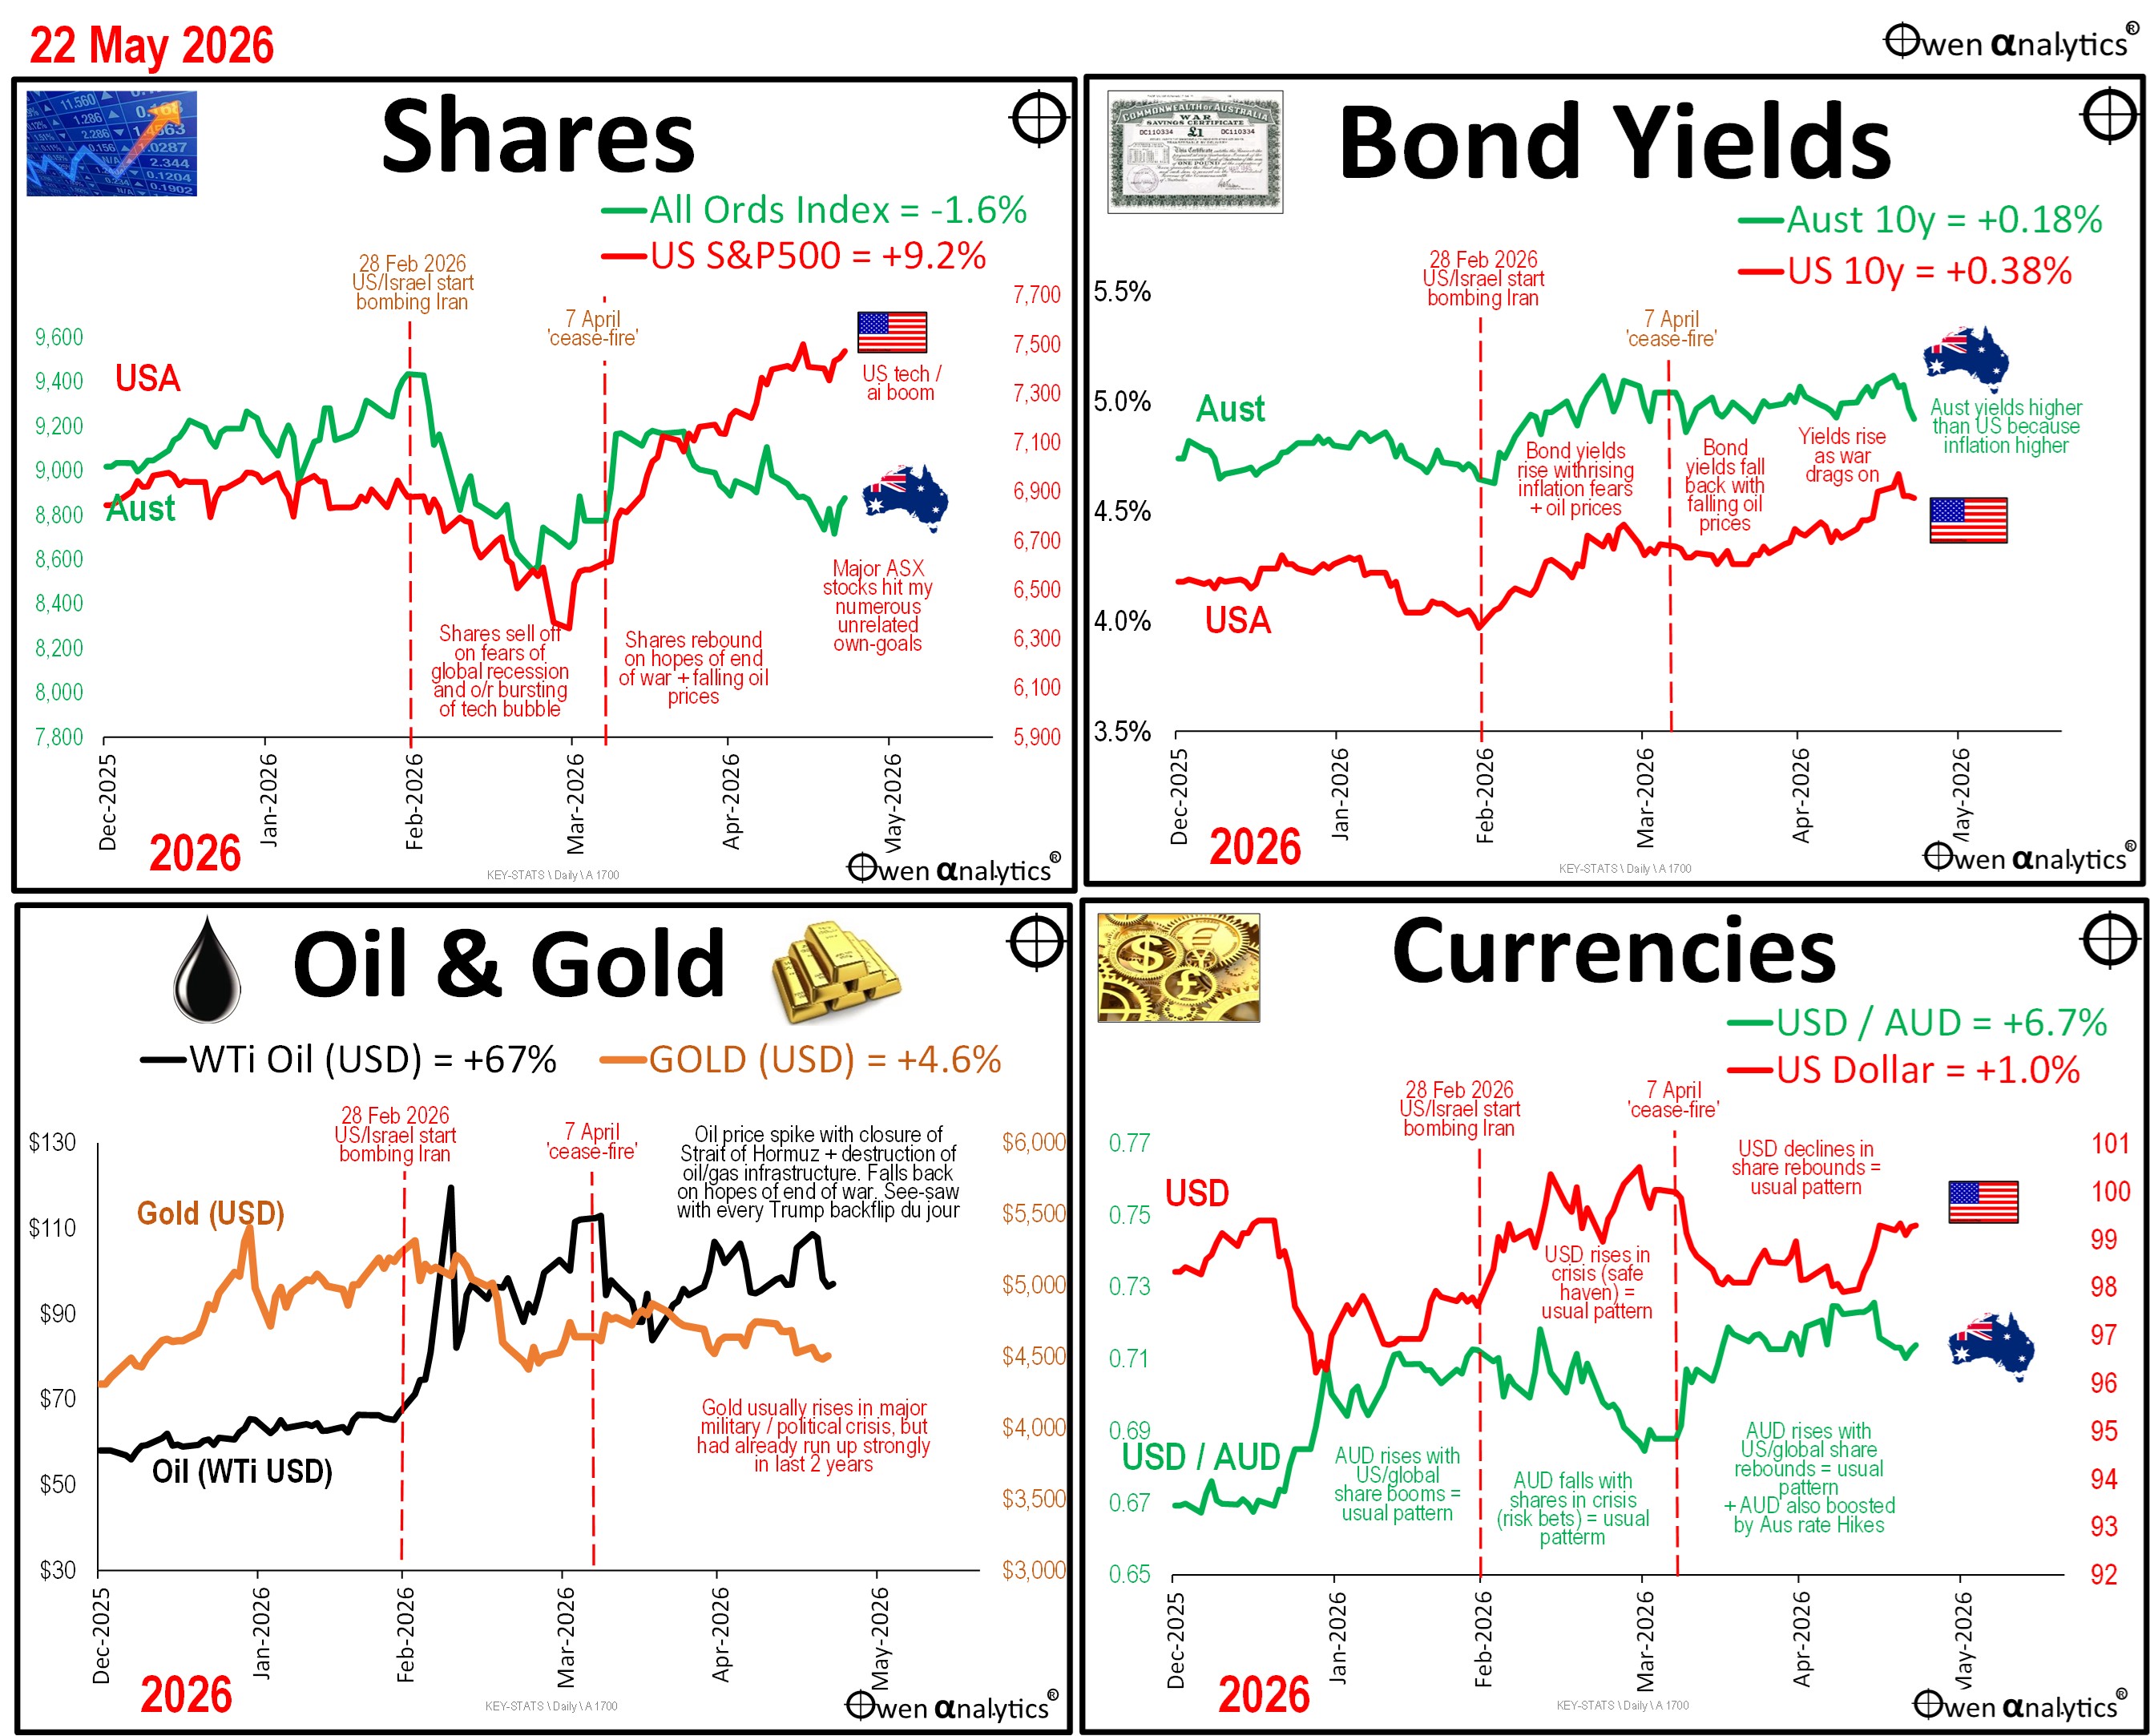
Here they are from the start of 2026, with key events/dates highlighted:
Brief comments on the major markets:
Shares
2026 to date:
- At the start of the war share markets everywhere sold off sharply. Then, from the beginning of April, shares started to rebound on signs of an early end to the war, and share markets kept rising after the 7 April ‘cease fire’ deal.
- Although the war has dragged on since then, with oil prices remaining high and inflation numbers rising across the world, US share prices have kept rising in the US-led tech / ai / chip boom. The US S&P market has posted 18 new all-time highs for 2026 to date.
- While the US market has posted 7 new all-time highs so far in May, the All Ords has posted none (the last All Ords all-time high was 27 Feb and it has only posted 2 new all-time highs this year).
- The ASX market does have some big miners that are benefiting from the global supply disruptions and demand surges, but it has two main problems holding it back. First, it has almost no tech / ai / semiconductor stars. Second, a string of major local stocks have been by ‘own-goals’ – ie problems of their own making.
- The local health care sector in particular has been a sea of share slumps this year - including: CSL, Cochlear, ProMedicus, ResMed, Sonic. Most of these have been own goals – with aggressive expansion adventures failing to live up to the hype.
- Also hit hard this year have been several former tech stars for the same reason (overly ambitious expansion) plus also the threat of annihilation by ‘ai’ - including: Wisetech, Xero, Seek, CarSales, REA.
- Also own-goals in other majors like Northern Star (gold production problems in the Super Pit).
Latest week:
- US shares inched up another 1% for the week as the US/Iran stalemate continued, Gains in Apple Palantir, Amazon1% and Tesla, more than offsetting falls in Nvidia, Alphabet/Google, Meta/FB and Microsoft.
- The ASX market was flat for the week. CBA recovered some ground from last week’s initial budget shock (tax changes designed to hit housing market), offsetting declines in BHP and Fortescue, despite rising iron ore and copper prices, and gold miners on lower gold prices.
Bond yields
2026 to date:
- Bond yields reflect expectations of future inflation and interest rates.
- At the start of the war, yields started rising in expectation that rising fuel prices would lead to higher general price inflation that would be met with interest rate hikes. After the 7 April ‘cease fire’, yields started falling in expectation of a resolution and lower oil prices.
- However, yields have been rising again since mid-late April as the war dragged on, the Strait of Hormuz remained largely closed, and oil prices remained high.
- Why they are important? Because rising bond yields mean lower prices and lower returns on fixed rate bonds. This is bad for long-term funds in Australia and globally, most of which are stacked full of bonds. Even if you are like me and hold no fixed rate bonds (have not since 2021), rising bond yields almost always trigger sell-offs in other assets including share markets and real estate.
Latest week:
- Australian yields rose above 5% on government spending/debt fears, reaching 5.12%, which is the highest since July 2011. However, yields were down a fraction by the end of the week after the release of weak jobs numbers and higher unemployment.
- US yields are hovering near 4.6%, with government spending / debt / inflation fears balancing slowdown fears for the US economy as higher fuel prices drag on.
- Looks like yet another bad year for bond markets everywhere (I have been out of fixed rate bonds in my portfolios and advised portfolios since 2021.)
Oil
2026 to date:
- Oil prices shot up at the start of the war, then eased back on hopes of early resolution, but rose again from Mid-April on Iran’s closure of Strait of Hormuz and destruction of oil/gas infrastructure. Prices remain high as the war drags on with no end in sight.
- Elevated energy prices are feeding into inflation numbers rising everywhere, lifting bond yields (and ordinarily should be dampening share markets).
- Why is oil important? Because rising fuel prices filter directly or indirectly into just about every inflation category, and inflation expectations drive interest rate decisions, bond yields, which in turn affect the pricing of all other assets.
- NB: The chart shows ‘West Texas Intermediate’ (WTI) which is the main US price benchmark for oil. Also of interest is ‘Brent Crude’ for Europe (Brent is currently around $10 above WTI), or ‘Tapis Crude’ for Aian markets traded through Singapore, etc. For me WTI is a pretty good general barometer.
Latest week:
- Another volatile week for oil prices – jumping on Trump’s threats to annihilate Iran (again), then falling back when Trump defers or delays (again), a pattern that is surely just to create more lucrative insider trading profits for himself, his family, and loyal henchmen.
- WTI still hovering below $100, and Brent around $105.
Currencies
2026 to date:
- The US dollar is the global ‘safe haven’ currency (and has been since WW1). The USD almost always rises in general crises (even if the cause of the crisis is the US itself – eg the GFC), as global investors (mainly US) sell risky foreign assets and retreat to the safety of US cash or bonds. To do this they need to sell the foreign currency and buy US dollars, putting downward pressure on foreign currencies and upward pressure on the US dollar.
- Conversely, The US dollar almost always declines during rebounds and general rallies. When global investors (mainly US) are bullish, they venture overseas to buy risky foreign assets. To do this they have to sell US dollars and buy foreign currencies, putting downward pressure on the US dollar and upward pressure on the foreign currencies.
- The Aussie dollar is a ‘risky’ foreign currency, so it ALWAYS falls in general global sell-offs as global (mainly US) investors dump foreign risky assets and retreat to the safety of the US. Conversely, in general global rebounds and booms, the AUD usually (but not always) rises as foreign investors (mainly US) venture back in.
- From the start of the war, the US dollar rose and the AUD fell – as per the usual pattern.
- After the 7 April ‘cease fire’ deal, confidence return (briefly) so the US dollar fell back and the AUD rose -also the usual pattern. Also boosting the attractiveness of the AUD are the three interest rate hikes here this year.
- However, since the 7 April ‘cease fire’ deal, they have reversed again as hopes for lower oil prices and an end to the war fade – sending the US dollar higher and the AUD lower.
Latest week:
- AUD down a little to 0.7139 USD as rising unemployment lowered chances of further imminent rate hikes, which would ordinarily attract more money in Australia and push up the dollar.
- USD index down a fraction for the week, consistent with share markets rising a fraction.
Gold
2026 to date:
- Gold usually rises in major military / political crisis but in this crisis the price action has been subdued, as gold had already doubled in price in the 12 months leading up to the war.
- The biggest buyers of gold in recent years have been central banks, especially in countries non-aligned to the US (who is aligned to the US under Trump?). Rising prices sparked a frenzied retail FOMO-led peak at the end of January this year, but prices fell back early in the war.
- Gold prices have remained relatively flat at around levels seen in the first few weeks of the year.
- The gold price should be kept elevated, and/or rising given:
- (a) rising inflation due to high energy prices and possible prices-wages spiral;
- (b) likely continued elevated fuel prices given Trump’s inability to end the war he started;
- (c) possible reluctance of central banks to hike rates to fight inflation; and
- (d) signs of China possibly revisiting plans to invade Taiwan.
- (I put gold in long-term portfolios (my own + advised) a couple of years ago, and it has been the best asset class since then).
Latest week:
- Gold hovering around $4,500, up 4.6% for the 2026 year to date.
In other news
Aside from Trump’s repeated and increasingly tiresome threats to annihilate then back down on Iran, the main global development for me was Xi Jinping’s back-to-back meetings with Trump and then Putin in Beijing. Xi’s relations with Putin appeared much closer and more aligned than with Trump, including Xi’s portrayal of China and Russia providing the bulwark of global stability in the face of Trump’s volatile and unilateral law-of-the-jungle aggression.
China remains our largest export customer and has been by far the largest contributor to our national income, wealth and living standards since the start of this century. USA used to be our reliable friend and ally.
In Australia, the dominant topic of debate is Labor’s proposed tax changes, and the inevitable walking back and carving out to appease the most vocal and well-funded special interest groups.
Labor had two main goals: (1) to help young people buy homes, but the tax changes will discourage housing investment/supply and push up rents and prices further. Goal 2 was to improve intergenerational equity, but the proposed CGT changes will punish young working investors and provide exemptions for older investors including boomer pensioners.
Interesting times indeed. . .
Stay tuned!
‘Till next time – happy investing and stay healthy!
Visit my web site for hundreds of original articles on a wide range of topics for advisers, portfolio managers, and serious long-term investors.
https://www.owenanalytics.com.au/
- All completely free of charge. Free of conflicts. Free of ‘ai’.
- All original research and analysis.
- No ads, No marketing material, No sponsored material at all.
- Not ‘monetised’ in any way. No ‘revenue model’.
- Guaranteed No ‘hot stocks’, No ‘hot tips’.
- Guaranteed No ‘ai’. All human.
Enjoy!