Here’s my quick wrap-up on global markets for serious long-term Aussie investors – including shares markets, interest rates, inflation, bonds, currencies, commodities, and more, including portfolio implications.
Key points:
-
-
- Share markets around the world rebounded in April after a very brief war / inflation scare in March, but the ASX remains a global laggard.
- Investors have two positives to support their bullishness. The first is hope that Trump retreats (dressed up as an epic ‘win’ of course) because his most urgent goal is to get fuel prices down in order to retain MAGA voters in the November mid-term elections.
- The second positive is strong US profits, thanks to tech / ai, and the bonanza for fossil fuel producers like the US.
- The war continues, but is increasingly looking like a stalemate, probably with higher energy prices and inflation for a while yet. Rate cuts or rate hikes?
- Share markets everywhere (not just US tech) are still vastly over-priced on numerous measures – including and especially in Australia. A major global correction is due.
- Bond markets posted more losses again as yields kept rising in expectation of higher inflation and interest rates ahead.
- The AUD rose and US dollar fell with the share rebound, as per the usual pattern in global panics / rebounds.
- Commodities prices mostly rebounded in April, benefiting ASX resource stocks.
But first - my essential 1-page snapshot chart - covering Australian and US share markets, short and long-term interest rates, inflation, and the AUD/USD exchange rate. Regular readers will notice that this year I have dropped the first version (all on one chart) and now just have the second version (showing Australian and US inflation and interest rates separately in the lower sections) from now on.
It is my go-to chart that tells me what happened when and why, whenever answering queries from advisers, investors, doing webinars, market updates, etc.
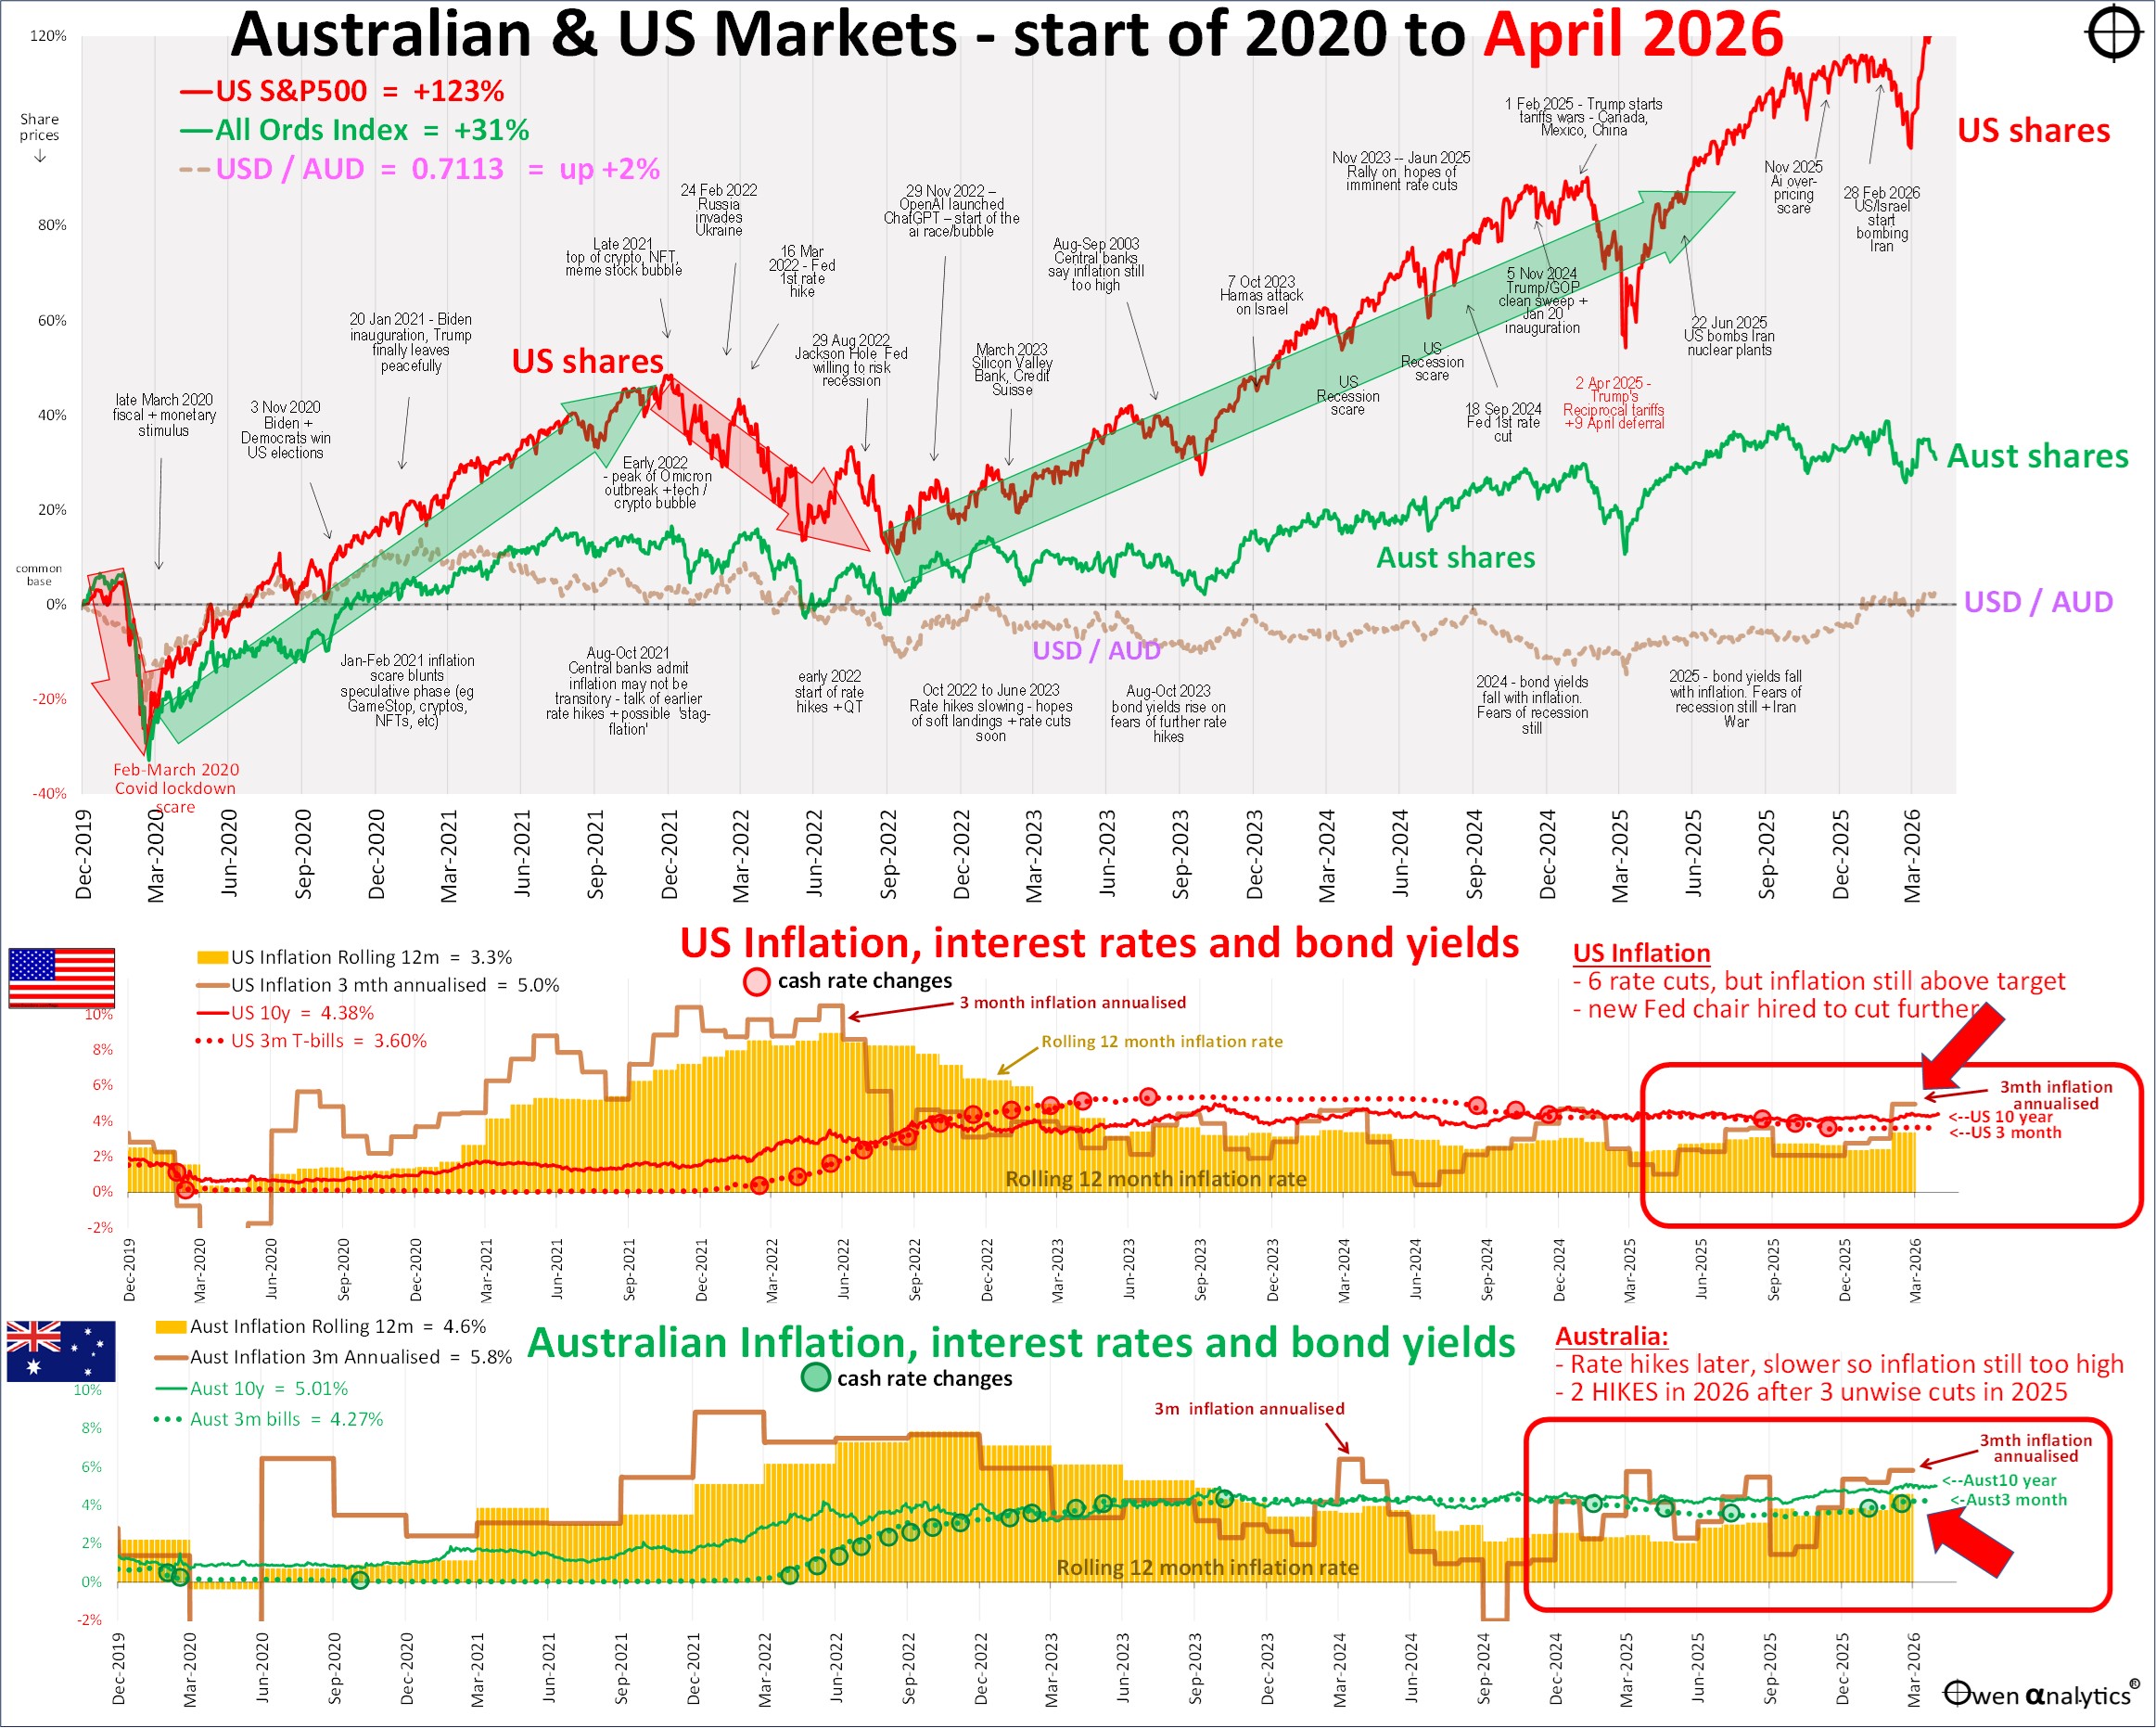
Not only does this have all the detail I need to answer investor questions from advisers, but even from the back of the room you can easily see the big picture on where we are for share markets, currency, inflation, long & short interest rates.
I will get into shares in a moment, but from the back of the room you can see that share markets had a minor hiccup in March (top right corner of the chart – red for US, green for ASX), but are back on track in April.
Bottom line – if you were rattled by the volatility and price falls in March then you ain’t seen nothin’ yet! (or you are too young to remember what a decent sell-off looks and feels like!)
Share markets
Global share markets rebounded in April after the brief sell-off in March when panicking investors sold down just about everything except for oil/gas stocks profiting from higher prices with the Strait of Hormuz closed.
As I pointed out in last month’s report, panic selling is crazy of course. It’s just an irrational knee-jerk panic reaction we see in every so-called ‘crisis’. I also suggested readers take a look at some of my research that debunk myths about the impacts of wars and oil prices on share markets -
And:
These fact-based research pieces demonstrate that most of the big wars/crises, including those involving oil price spikes, inflation, and even ‘big’ wars, actually turned out to be positive for share markets in a large majority of cases (after initial short-term panic sell-offs of course).
Then, right on cue, share markets brushed off the March panic and rebounded in April.
Global Industry Sectors
The next charts show total returns from global sectors for April 2026 (middle chart), calendar year to date (right), compared to 2025 (left chart):
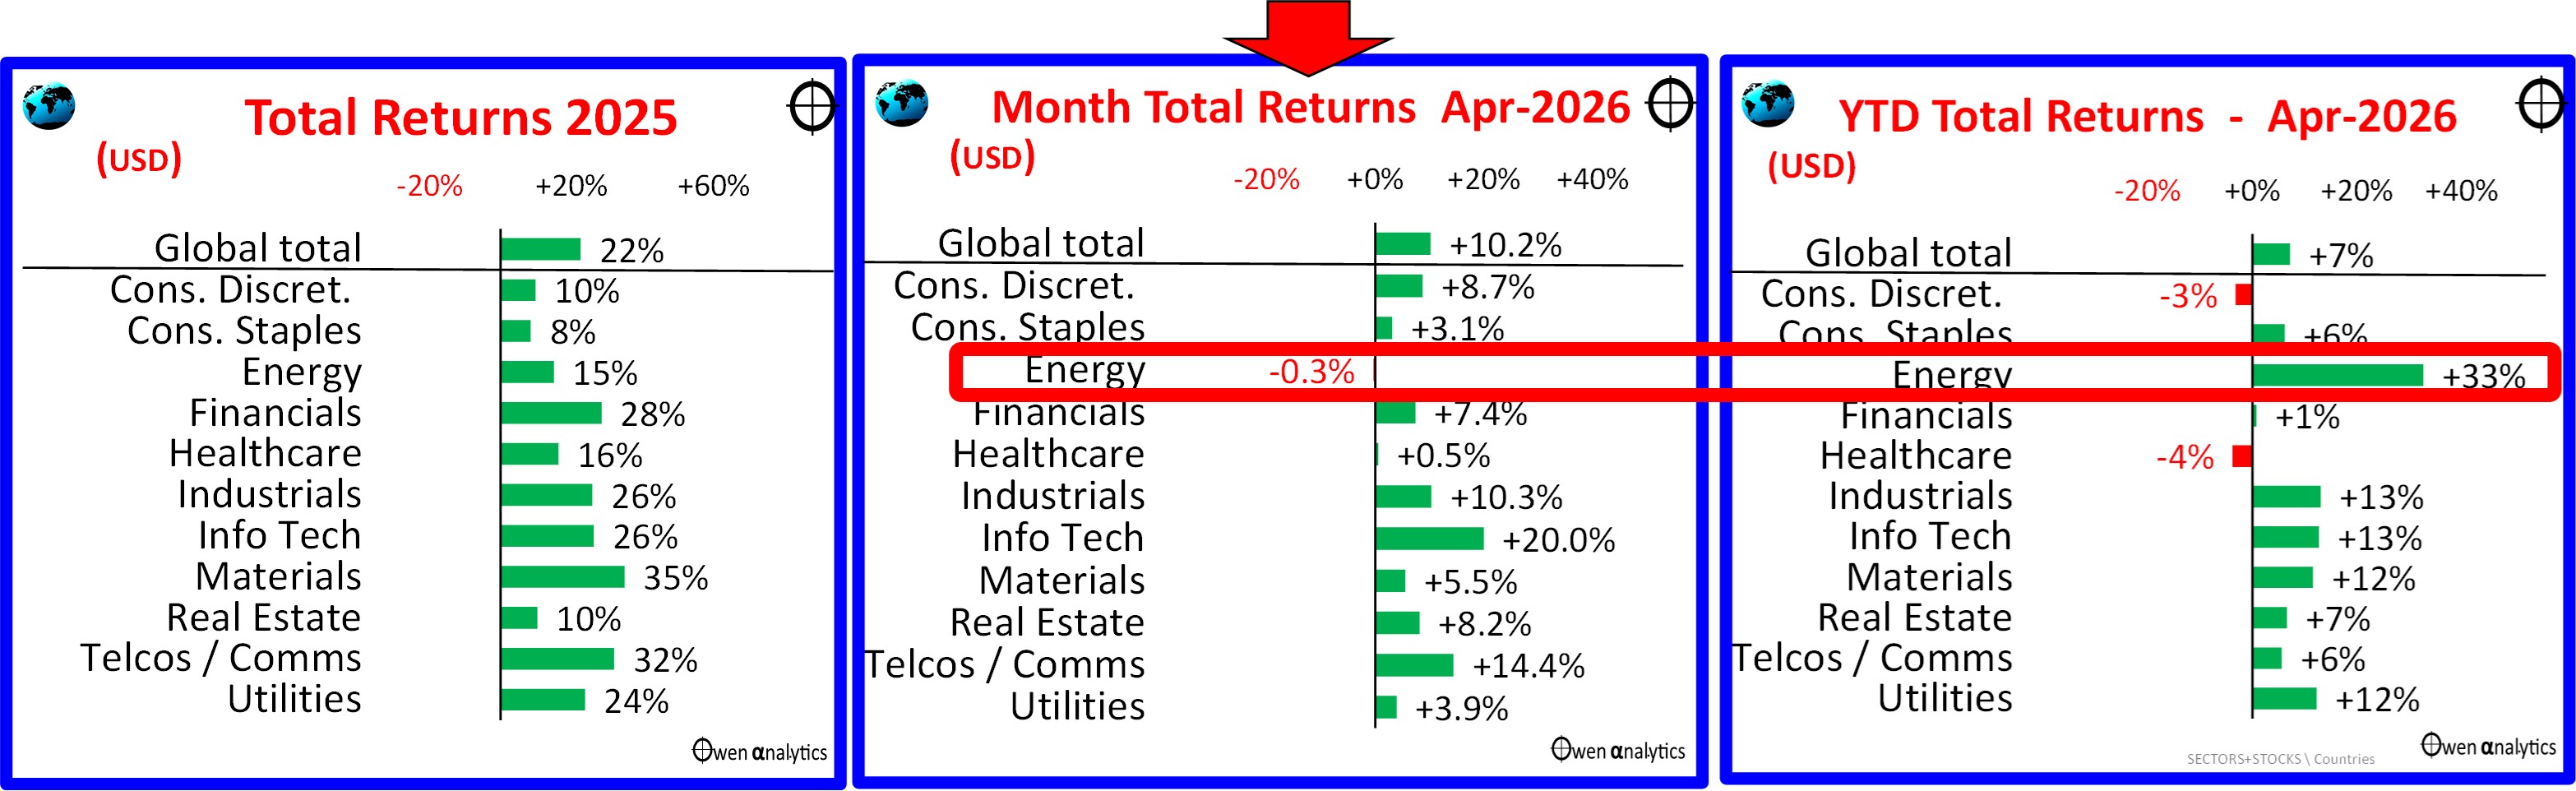
The stand-out sector up is fossil fuels (‘energy’) – with across the board double-digit rises in the major stocks as they profit most from the global supply squeeze.
Major global stocks
Here is the picture for the largest global stocks (all of which are US based) for the same three periods:
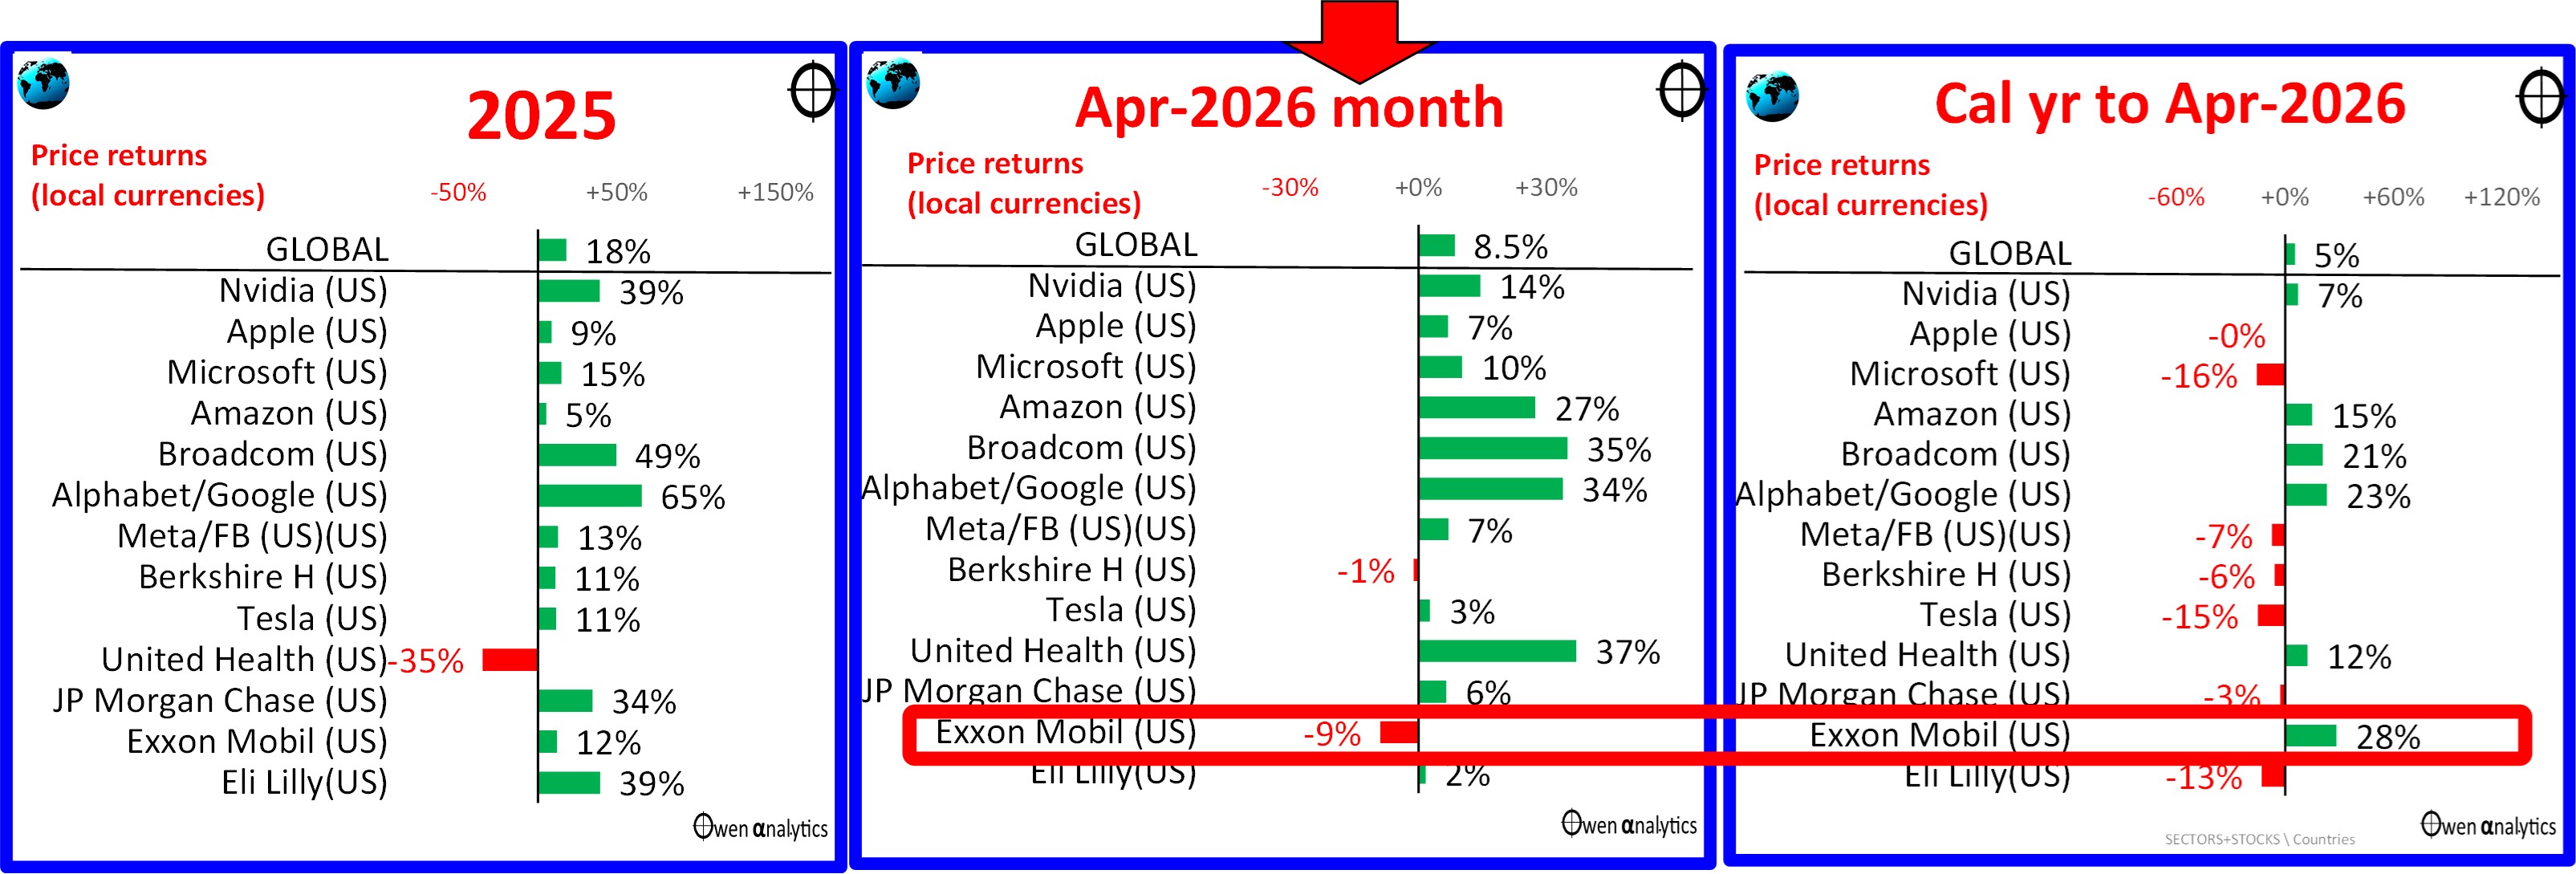
Exxon-Mobil is still leading for the year to date, but the stars in April were the US tech/ai giants, which were under-pinned by very good profit reports for the March quarter (Microsoft, Amazon, Alphabet/Google, although Facebook was not as strong).
Outside of the global/US giants, cycle sectors like industrials, materials and financials did well in April, with good price rises almost across the board.
Mag-7 update
For context, next are share price charts for the so-called ‘Magnificent Seven’ stocks over the past decade. I have also added three other punters’ favourites Oracle, Palantir, and Adobe, plus China’s Alibaba and Tencent:
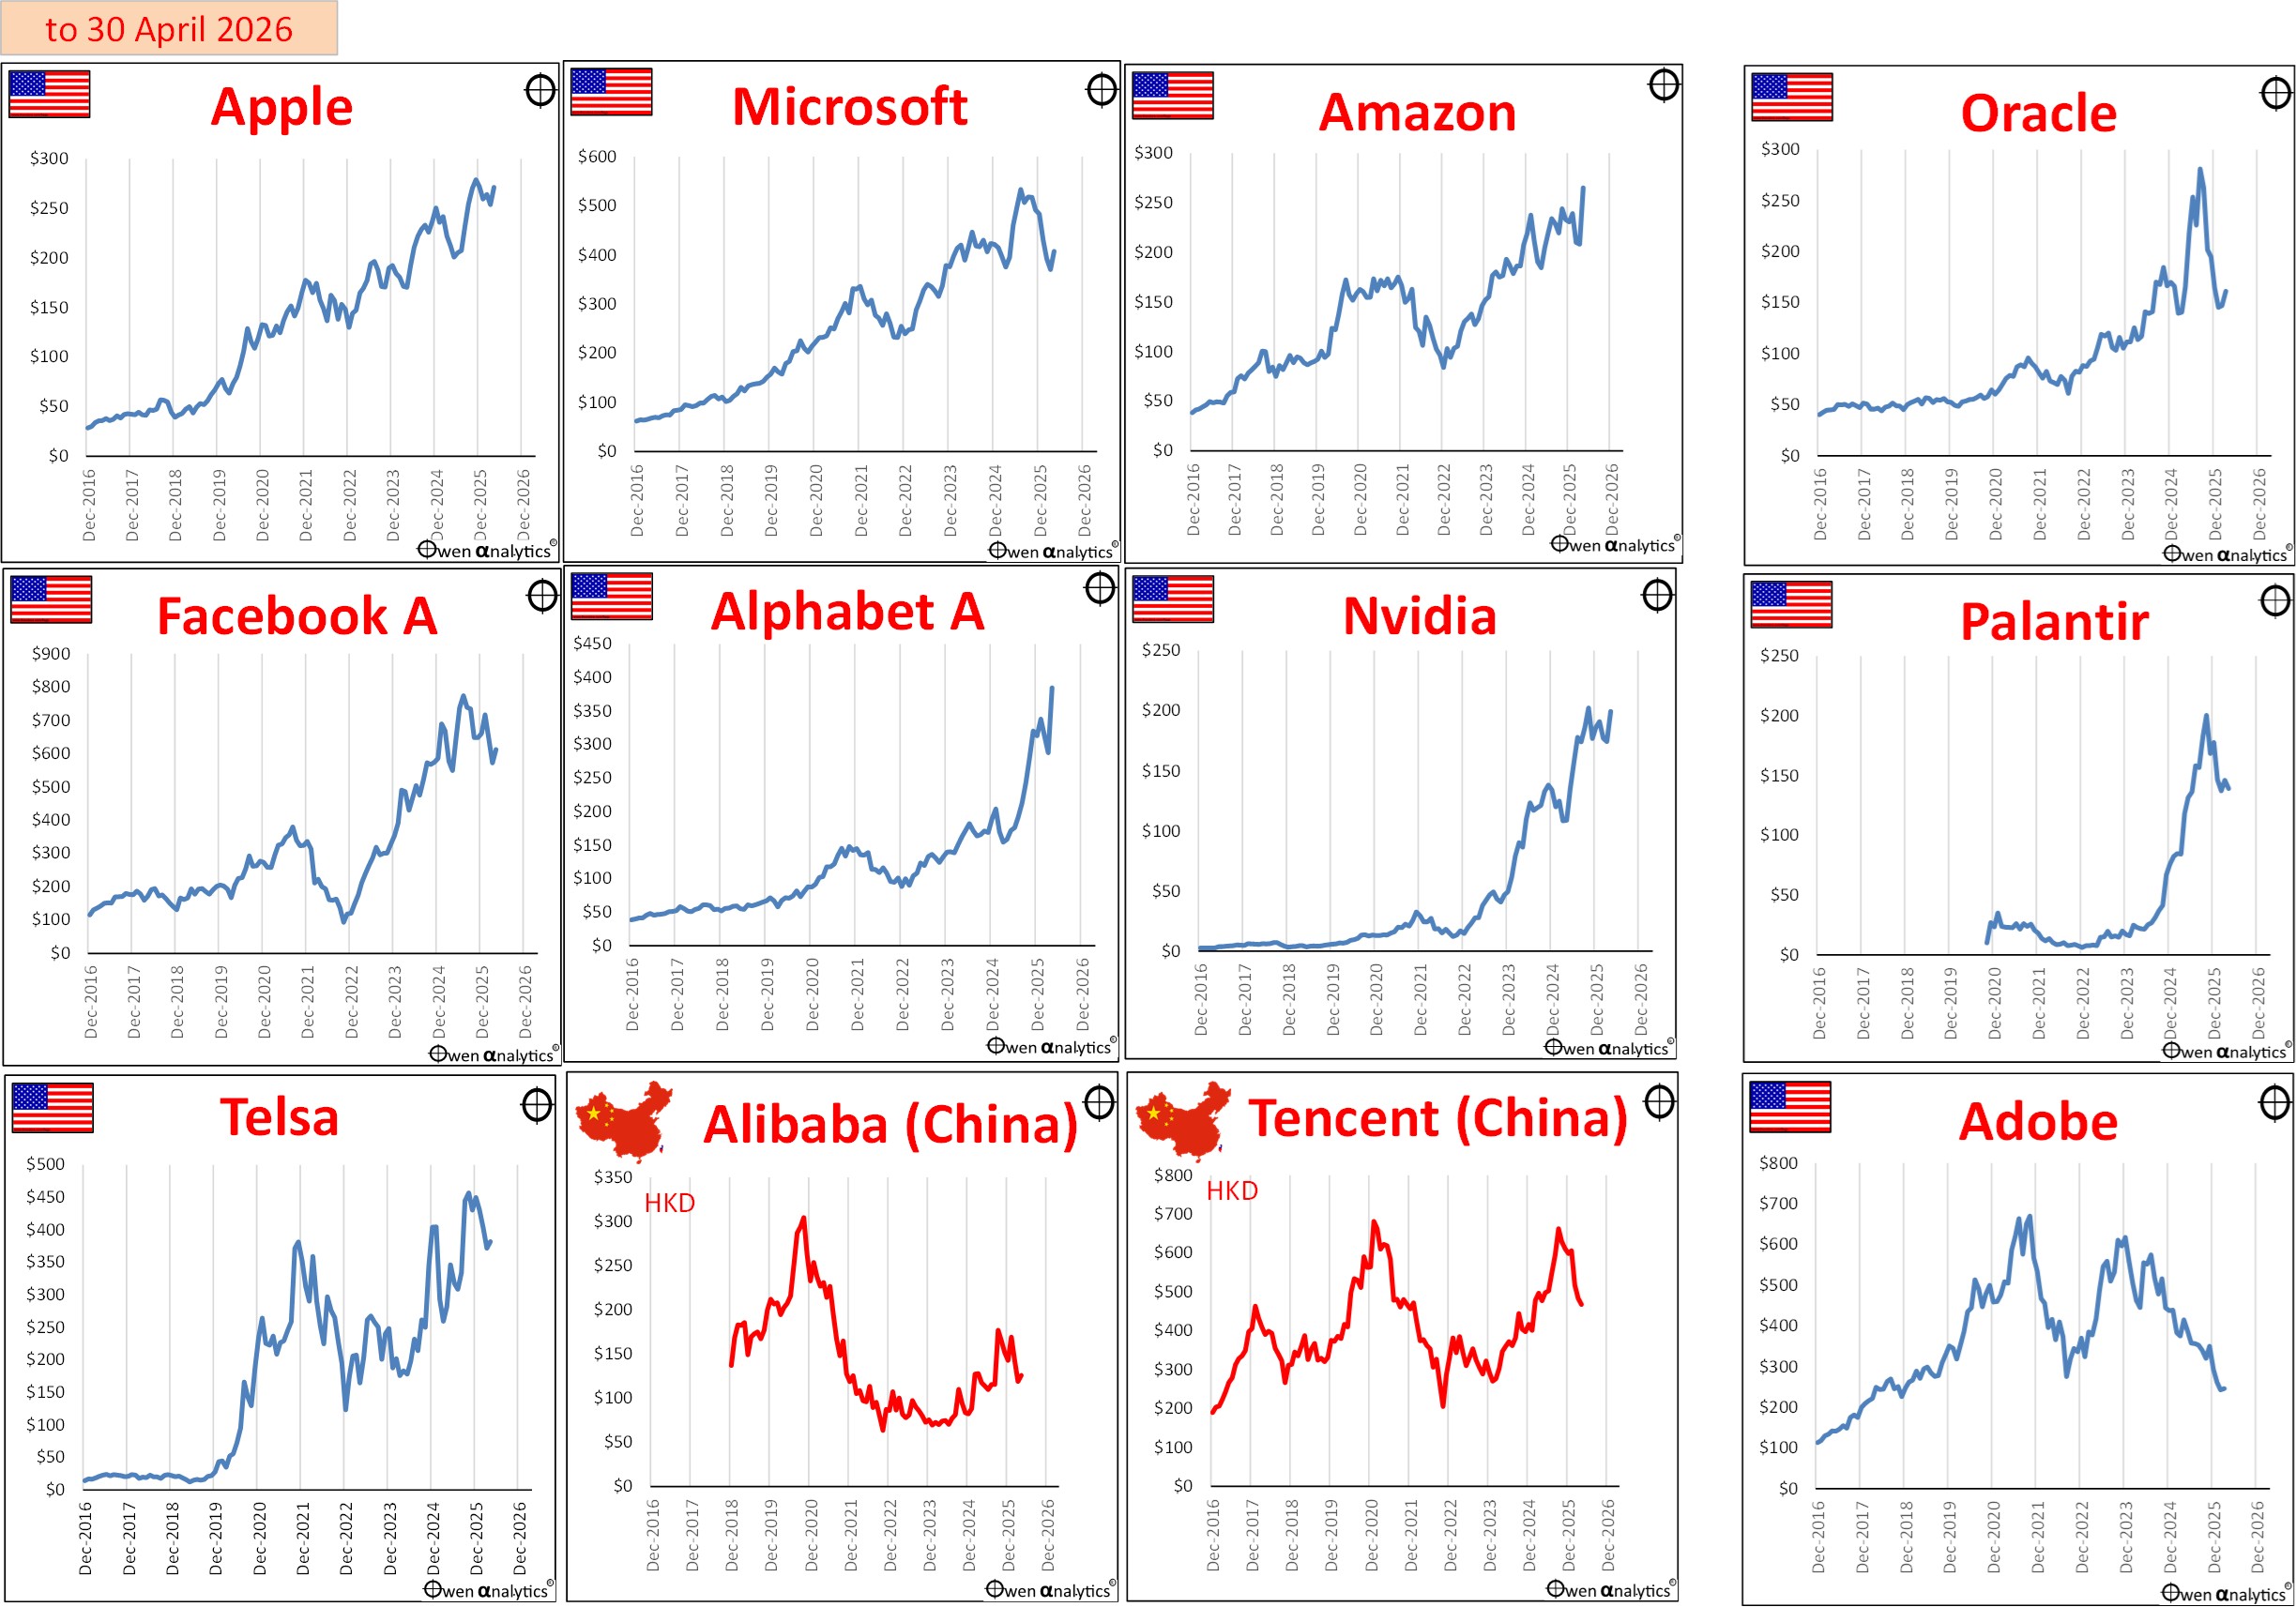
(For the benefit of new readers, I have not used any y-axis scale trickery here – the vertical y-axes all start at zero, and have regular, nominal scales, which highlights the explosive share price growth of the US giants from very low levels in the past decade.)
China’s Alibaba and Tencent are up over the past year, but both are still below their 2021 peaks. By comparison, all of the US majors are well above their previous peaks in the 2021 Covid stimulus boom, even struggling low-margin car-maker Tesla, finally.
Aside from Tesla, Adobe is the odd one out here – seen as being most vulnerable to being eaten by ‘ai’.
The US tech giants are still very expensive on a range of metrics. See my report on how they stack up individually on revenues, profits, dividends, and pricing -
A few months ago I published a six-part series on pricing of global share markets to better understand their implications -
For more on US profits and pricing – see:
Major country share markets
Share markets almost everywhere had a great month in April. Here are the main markets:
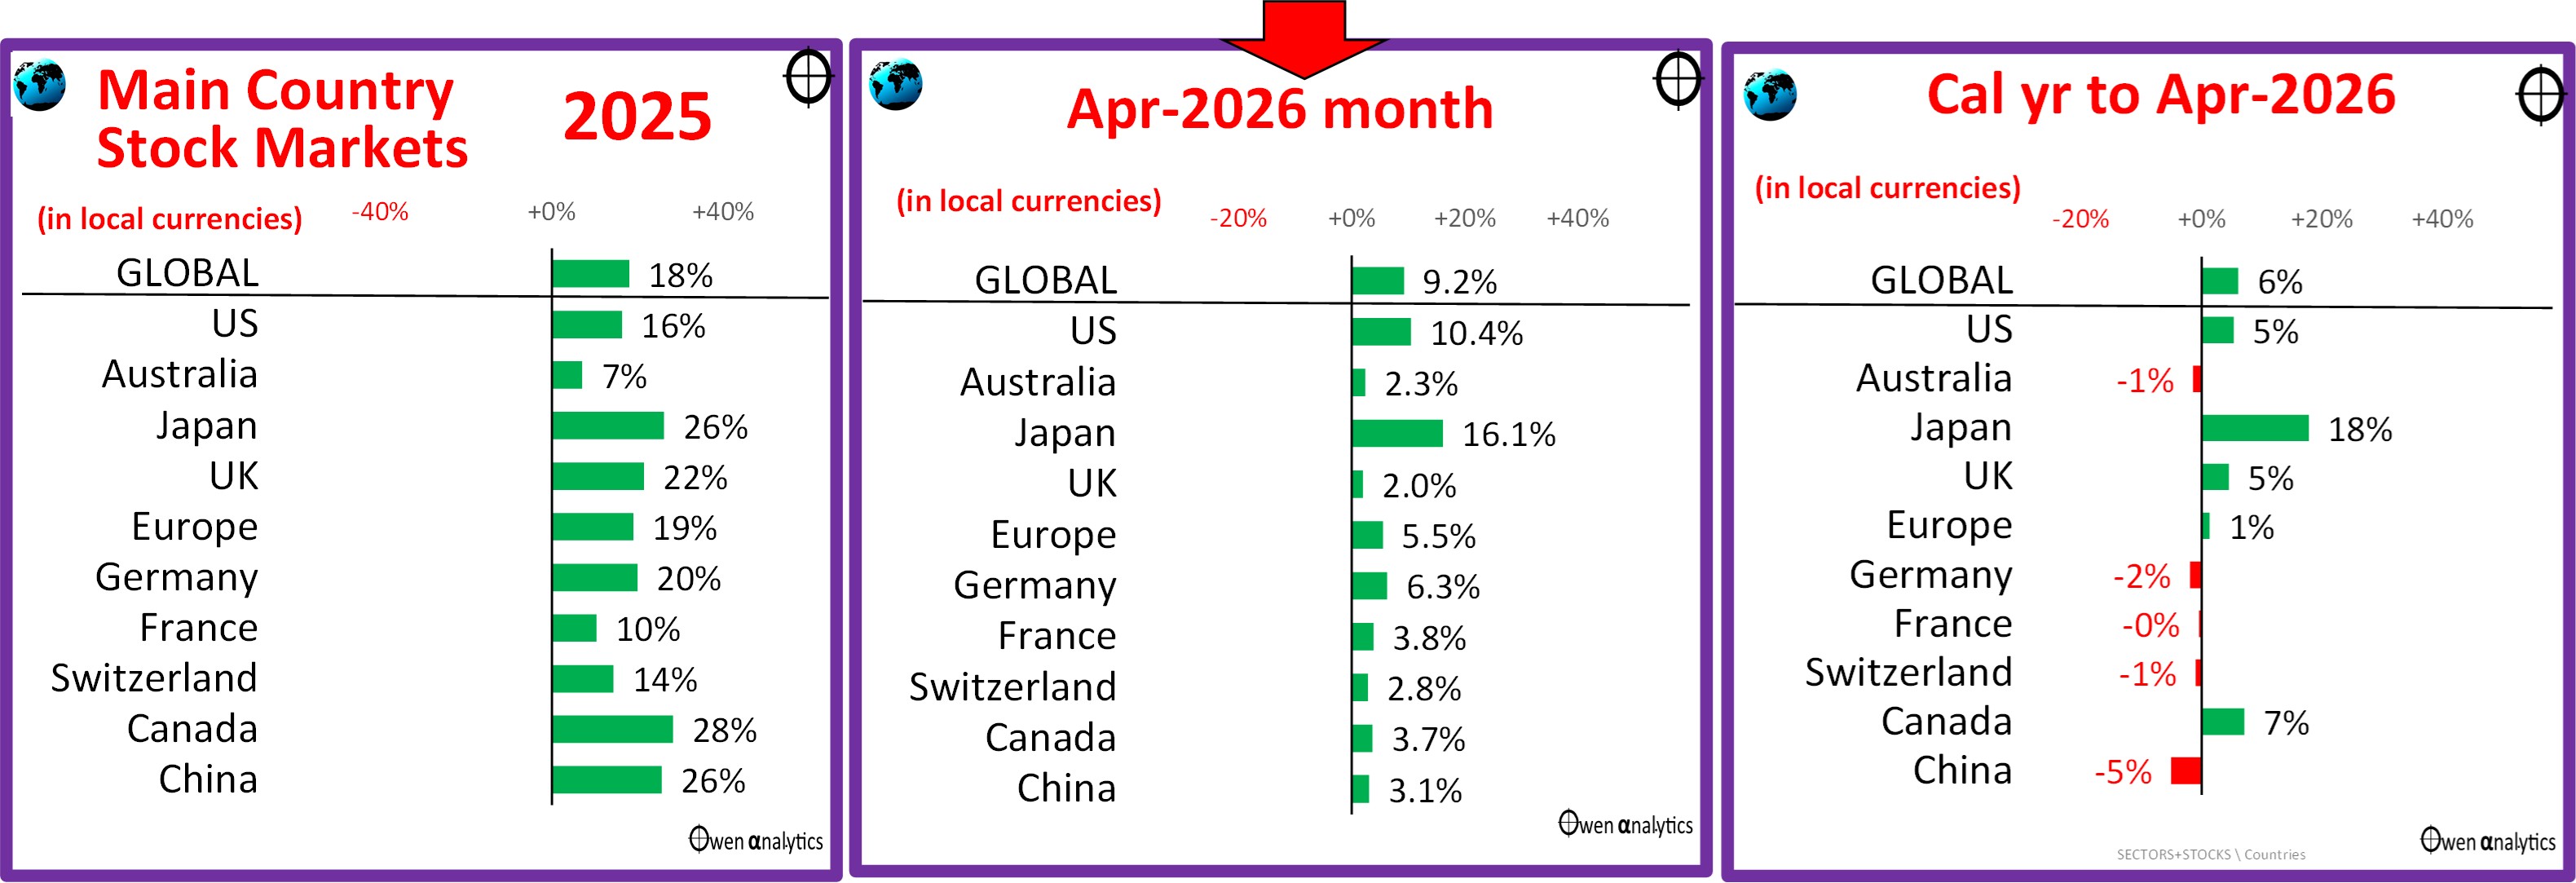
Best of the major markets has been Japan, led by Softbank (big Facebook holding plus other US tech bets), Keyence (robotics), and Shin-Etsu Chemical (plus assisted by weaker yen). Next best was the US (tech/ai giants).
So far in 2026 global share markets are ahead by 6% (in local currency terms). This may make it a fourth good year in a row in the current boom, following three very strong years averaging +20% per year in 2023, 2024 and 2025.
Share markets everywhere (not just US tech/ai stocks) are still vastly over-priced on a variety of measures – including and especially in Australia, and we are well and truly due for a global correction. Refer to the above reports on share market pricing.
Australian shares
Here are the main ASX stocks for April 2026 (middle chart), calendar year to date (right), compared to 2025 (left chart):
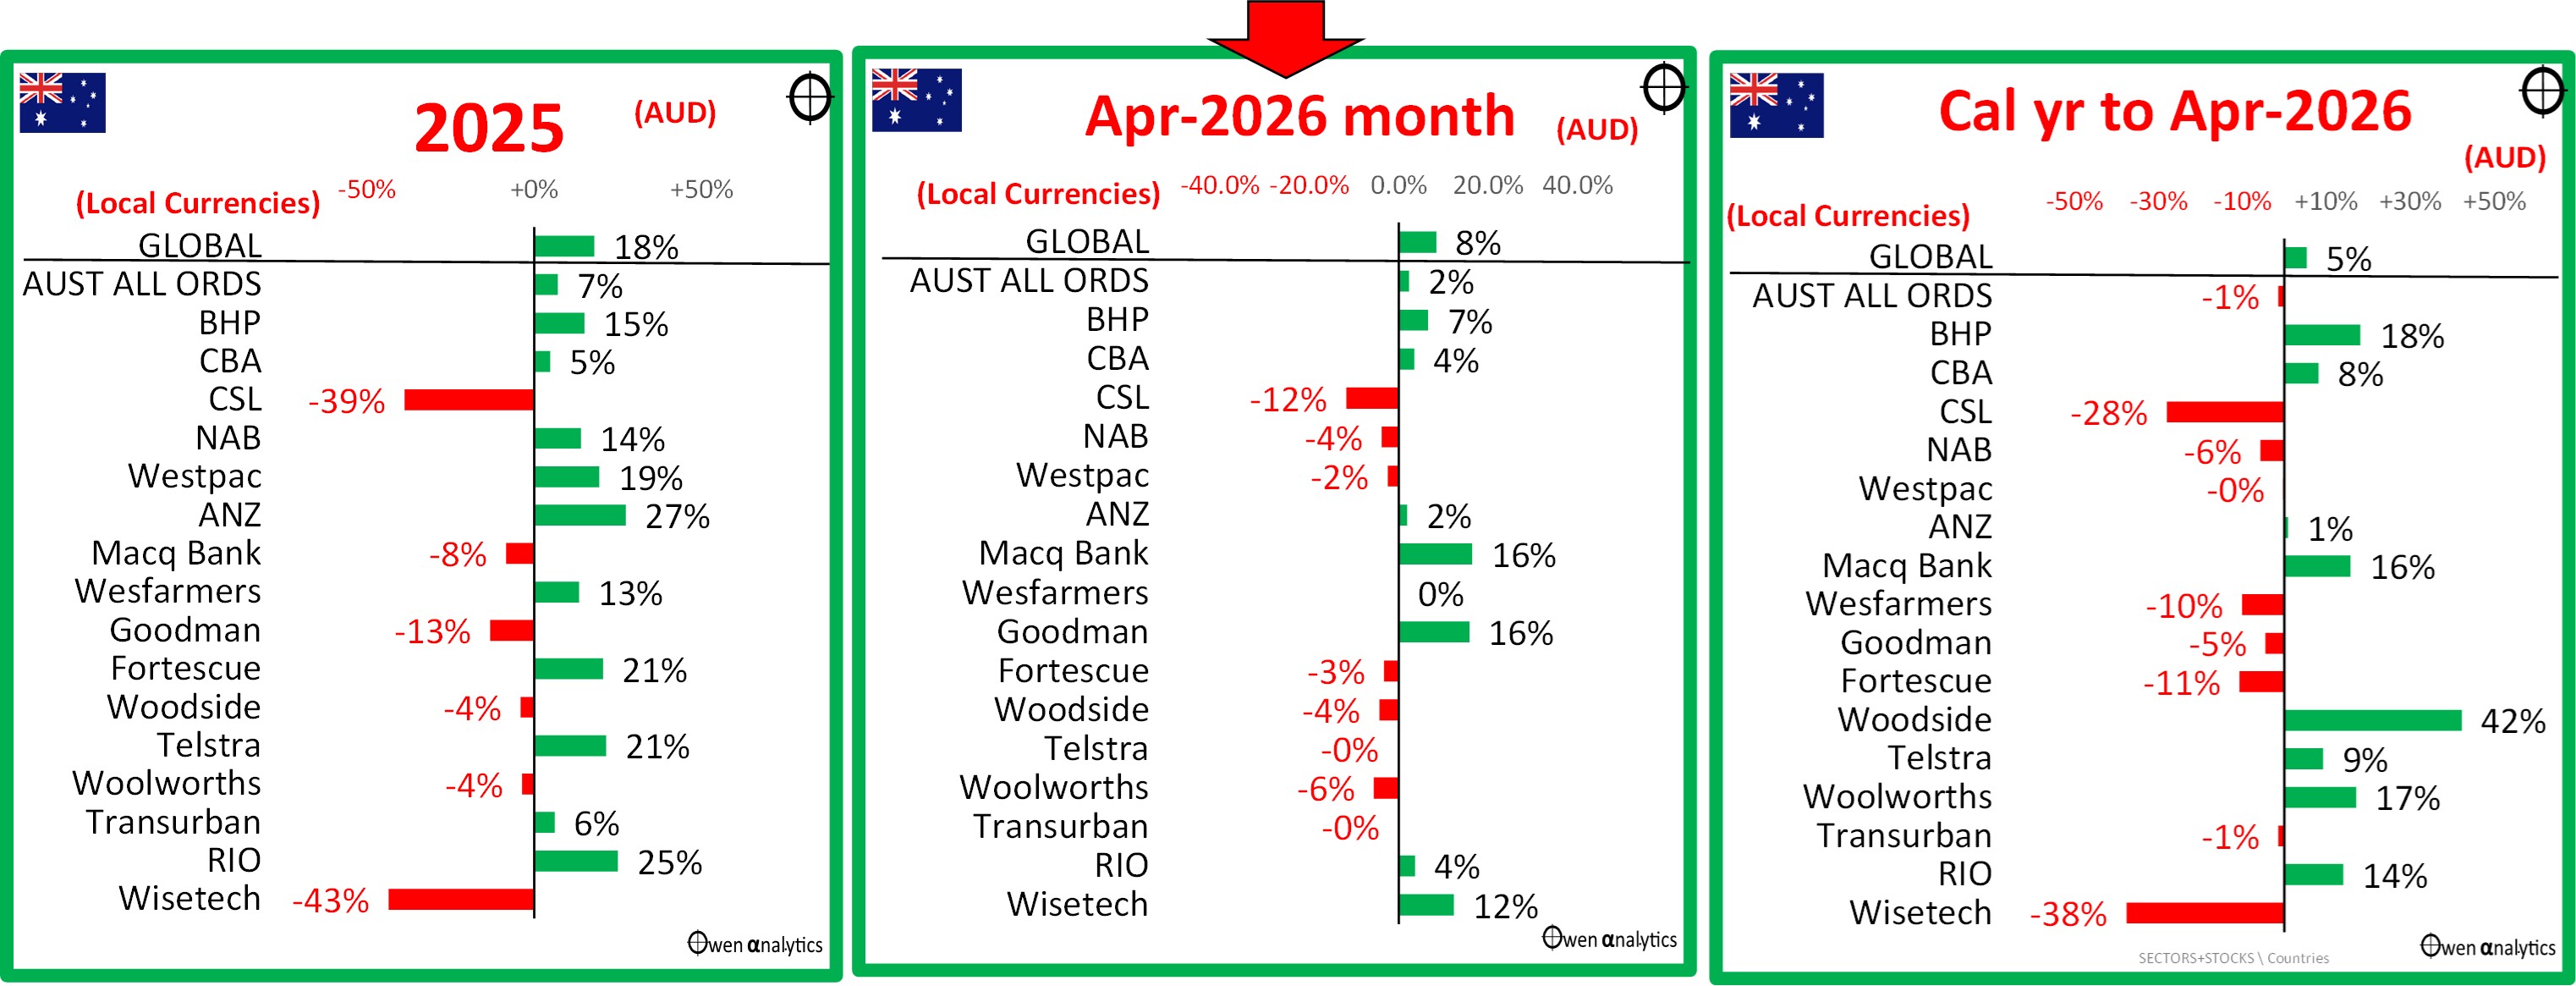
The Aussie share market is lagging the US and rest of the world again this year for two main reasons. First, the ASX market is dominated by century-plus old low-growth dinosaurs – see:
The second reason is that the very few innovative Aussie companies with something to offer the world are notorious for over-ambitious overseas expansion plans that almost never live up the hype.
So far this year, the main winners on the ASX have been fossil fuel producers (led by Woodside +42%, Santos +30%), and miners (BHP +18%, RIO +14%, Lynas +52%, Pilbara Min +43%, Iluka +40%, MinRes +17%), although the gold miners have been flat with the recent gold price boom easing off this year.
The big banks have been mixed this year (CBA +8% to NAB -6%), but other sectors hare mainly down.
Worst this year have been health care, which has been a sea of red ink: CSL (-28%), Cochlear (-64%), ProMedicus (-39%), ResMed (-17%), Sonic (-13%). Most of these have been own goals – with aggressive expansion adventures failing to live up to the hype.
Also hit hard this year have been several former tech stars for the same reason (overly ambitious expansion), plus also the threat of ‘ai’: Wisetech (-37%), Xero (–30%), Seek (-40%), CarSales (-17%), REA (-7%).
Inflation & interest rates
A stalemate in the US/Iran looking like a reasonably likely outcome would mean above-target inflation lasting longer (after short-term rises).
Despite inflation remaining sticky around the world, central banks have mainly held cash rates flat this year – taking a middle road between further rate HIKES to reduce spending and inflation, versus rate CUTS to stimulate slowing economies due to higher prices. In the US, Jerome Powell had his final meeting as Chair of the US Fed rate-setting board, which voted to keep rates flat.
Australia is the exception of course. The RBA has been the only central bank in the world to switch from rate cuts after the 2021-3 inflation surge, back to rate HIKES – with two hikes in February and March this year.
Even before the latest war on Iran, Australia already had the HIGHEST cash rate amongst its peers – because we have the highest inflation, the highest inflation expectations (treasury yields), the loosest/highest inflation target, and the lowest unemployment rate among our peers.
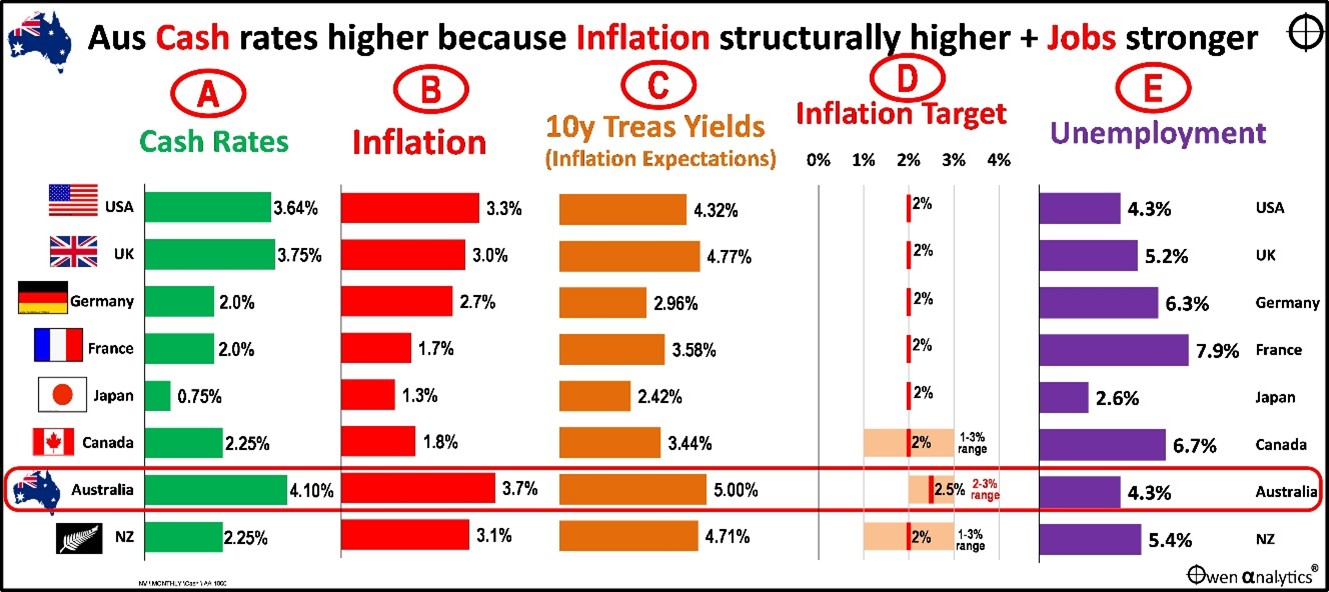
For the full story see –
Now that Australian CPI inflation has risen even further to 4.6% in the year to March, the RBA should hike rates further in its upcoming 5th May meeting, but it may wait to see how expansionary / inflationary the upcoming May Federal Budget actually is. (The budget will range somewhere between ‘highly expansionary / inflationary’ and ‘ridiculously expansionary / inflationary’). Apologies once again to my kids and future grandkids who will be paying for this chronic fiscal diarrhoea through higher interest rates and taxes for the rest of their lives.
Either way, more rate hikes are on the way if inflation is to be returned to target range.
Bond yields and bond markets
The picture on inflation and interest rates leads us directly to bond markets, in which every local and global institutional retirement/pension fund is required to hold huge allocations (but not mine).
Bond yields rose across the board again in April as elevated fuel prices lifted fears of even higher inflation and cash rates ahead.
The next charts show changes in 10-year treasury yields in April (top chart), in 2026 calendar year to date (middle), and last year (bottom):
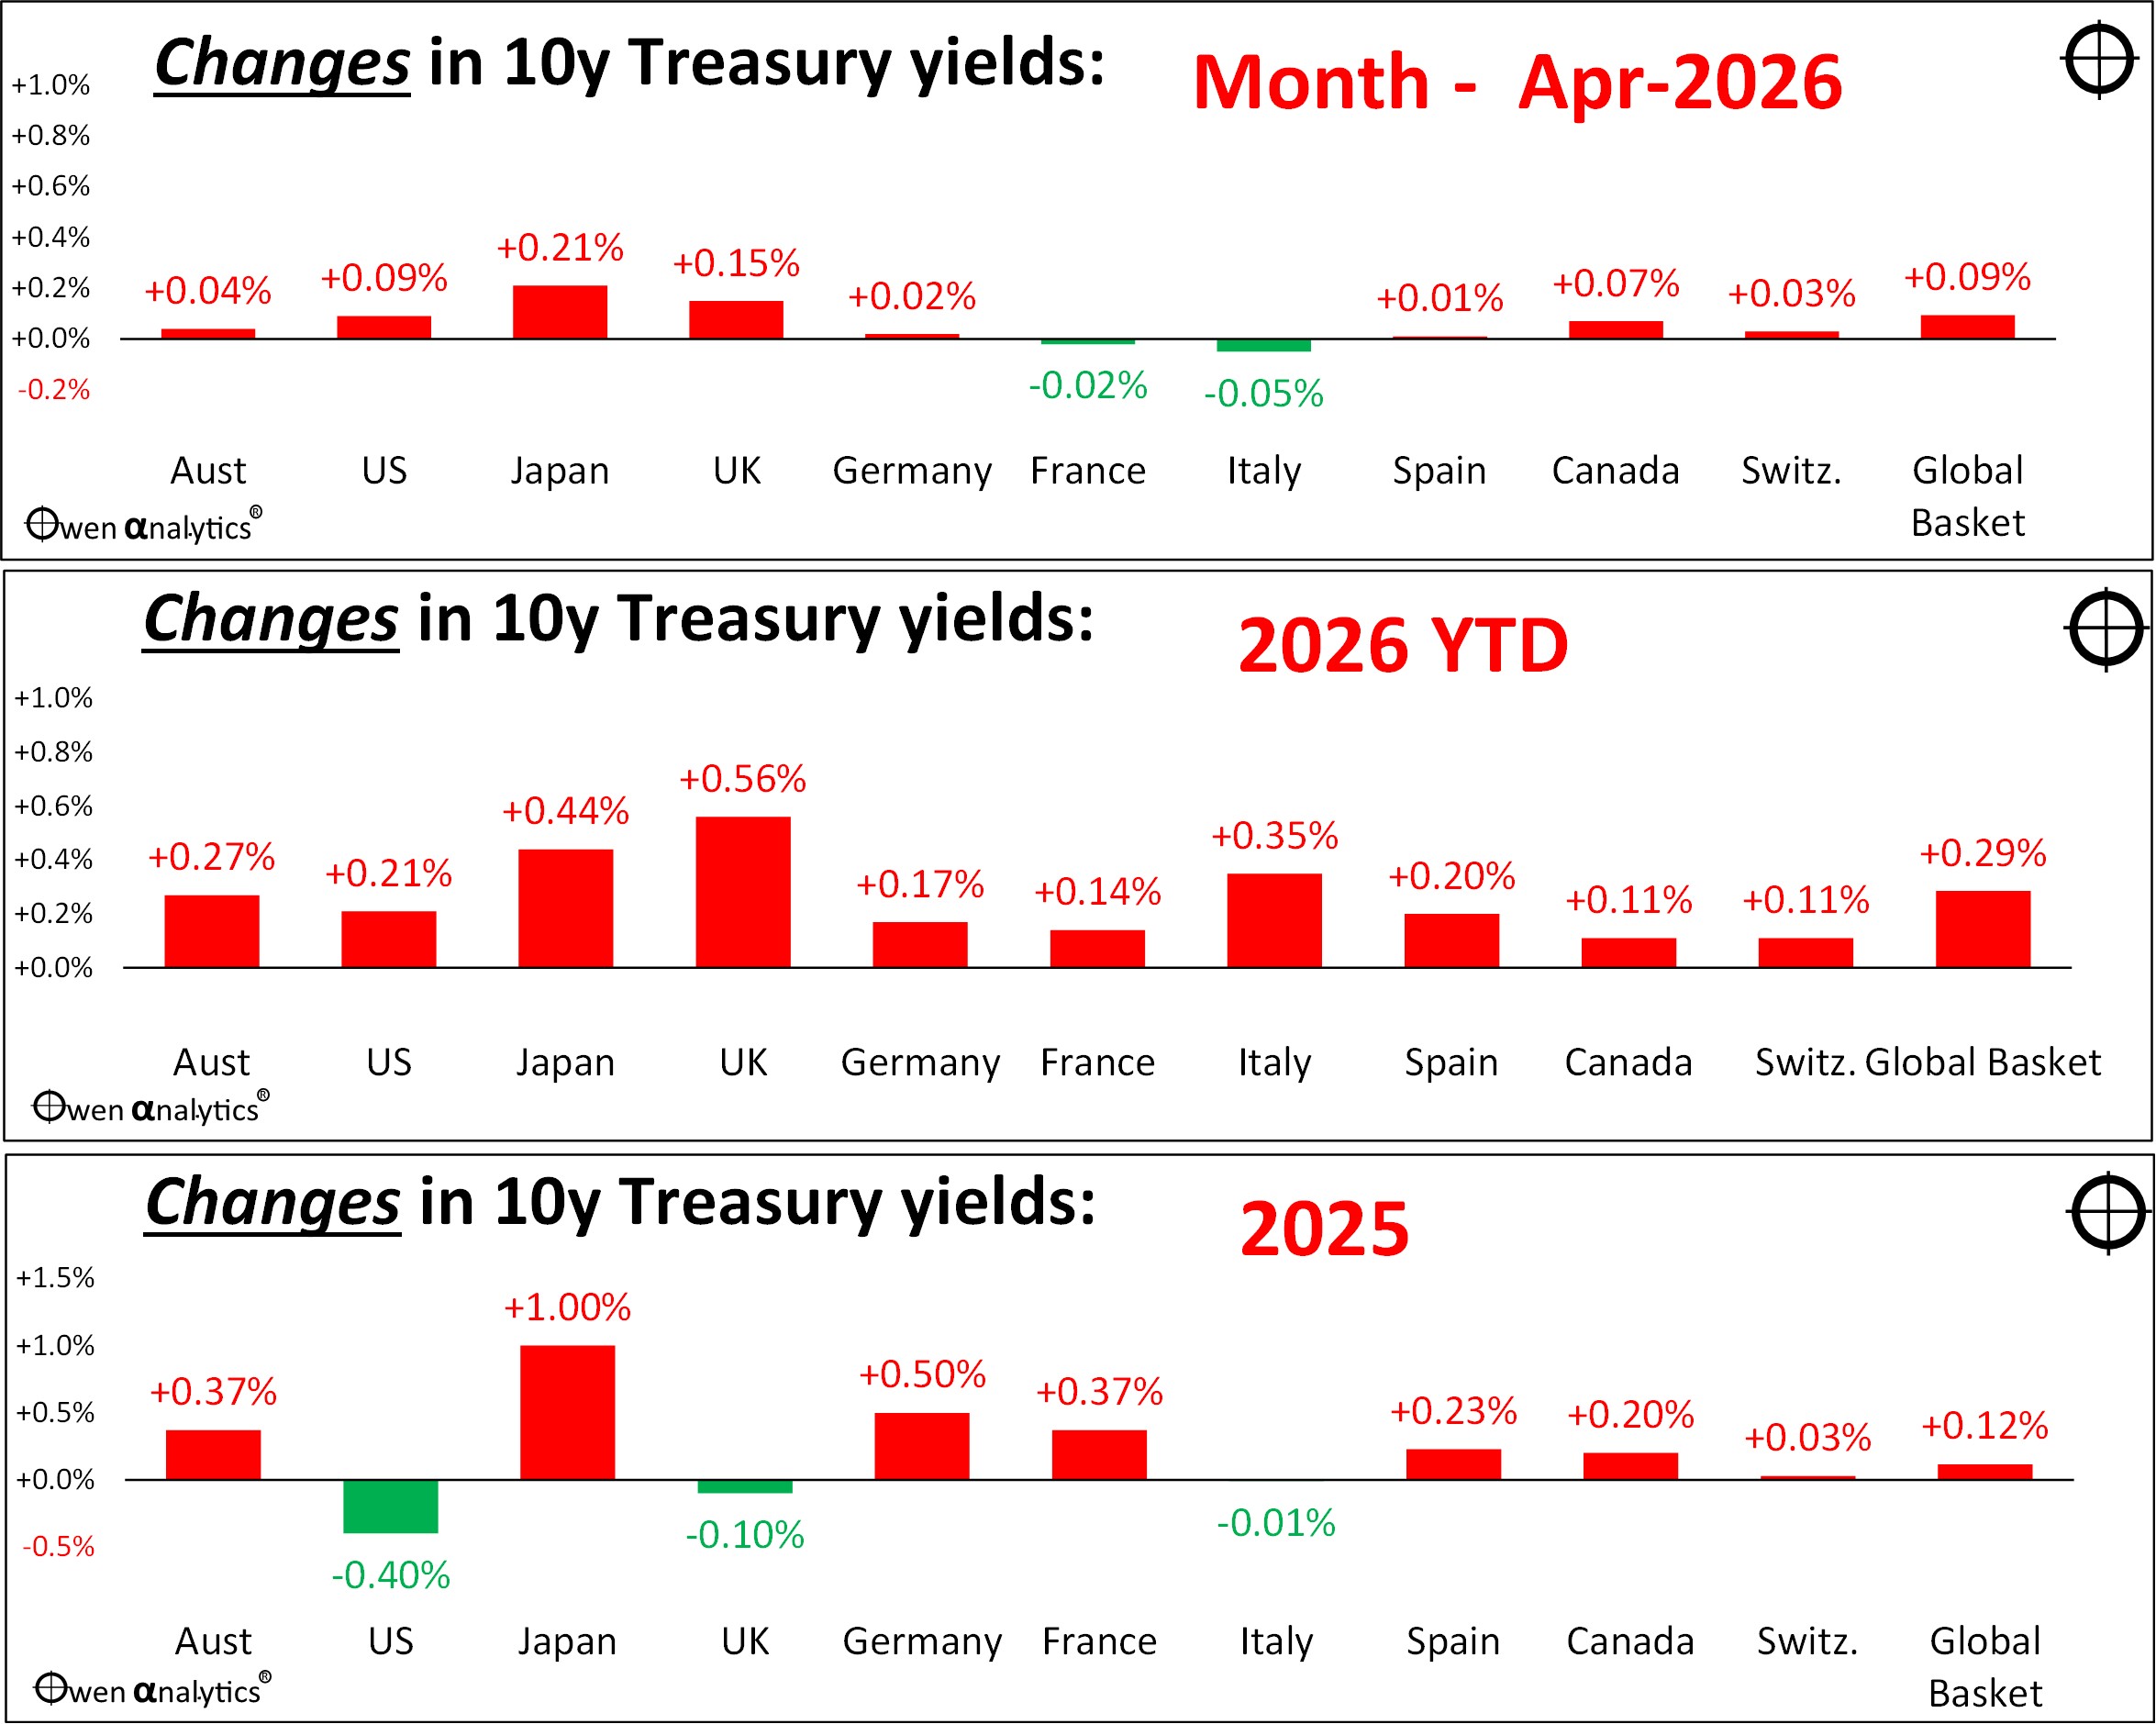
(In my charts of changes in bond yields, I show rising yields in red as they mean lower bond prices & returns; and I show falling yields in green as they mean rising bond prices & returns.)
This sea of red (rising yields) is bad for bond market returns.
Bond market returns
Last year (2025) turned out to be the fourth straight year of poor nominal and real returns from bonds, as yields rose virtually across the board with inflation remaining ‘sticky’. So far 2026 is looking like being a fifth straight year of poor nominal and real returns from bonds. We have not seen that since the 1970s.
Despite below average returns on bonds in 2025, at least 2025 was a better year for bonds than 2024 when yields rose by significantly more. Not nearly as bad as 2022, which was the worst year for US bonds in more than a century, and the worst year for Australian bonds since the 1931 Commonwealth debt default/restructure.
Now with the war in Iran and major oil/gas disruptions, yields are on the rise even further, meaning more losses (or poor returns at best) for bond markets.
Fortunately I have been out of fixed rate bonds in portfolios (advised, and my own) since 2021, due to fears that yields will remain elevated for at least the next few years, due to persistent inflation, with loose fiscal policy (governments running deficits and debts), and also loose monetary policy (central banks under enormous political pressure to keep rates too low).
It is not just the latest war in Iran. We have a host of longer-term inflationary pressures at work – including rising military spending everywhere, on-shoring of manufacturing, wage pressures from labour shortages resulting from reduced immigration, transitions to renewable energy sources, and increased supplies of bonds from profligate, populist, big spending governments here and around the world.
For the real story behind oil price spikes and inflation – see:
Maybe I will take a look at fixed rate bonds again in a few years.
Exchange Rates
As the Aussie dollar is a ‘risk currency’, it always sells off in a global crisis, regardless of local conditions. In the March share sell-off the AUD fell against all major currencies, especially the US dollar (ie the usual pattern). This partially cushioned price falls on ‘unhedged’ foreign shares when converted back into Aussie dollars for portfolio reporting.
Then in April the AUD rebounded along with the share rebound (also the usual pattern).
Conversely, the US is the global ‘safe haven’ currency (and has been since WW1), so it (almost) always rises in global crises, even if the US is the cause of the panic (for example in the GFC). As global investors (ie primarily US investors) panic sold just about everything in March and retreated home, the US dollar strengthened against all other major currencies (the usual pattern).
Then the US dollar then fell back in April as shares rebounded (also the usual pattern).
I have a 40% hedge ratio on international shares in my long-term portfolios, so I have profited from the general rise in the AUD over the past year, but also obtain a decent partial cushion in sell-offs.
There has been a lot of nonsense in the populist media about the impending ‘end’ or ‘death’ or ‘decline’ or ‘demise’ of the US dollar. For the big picture on the strong US dollar and why Trump is understandably trying to talk it down, see:
Commodities
The war (or probably fears of a global recession or slowdown) hit prices of most industrial commodities including battery metals and even gold in March, but most rebounded in April:
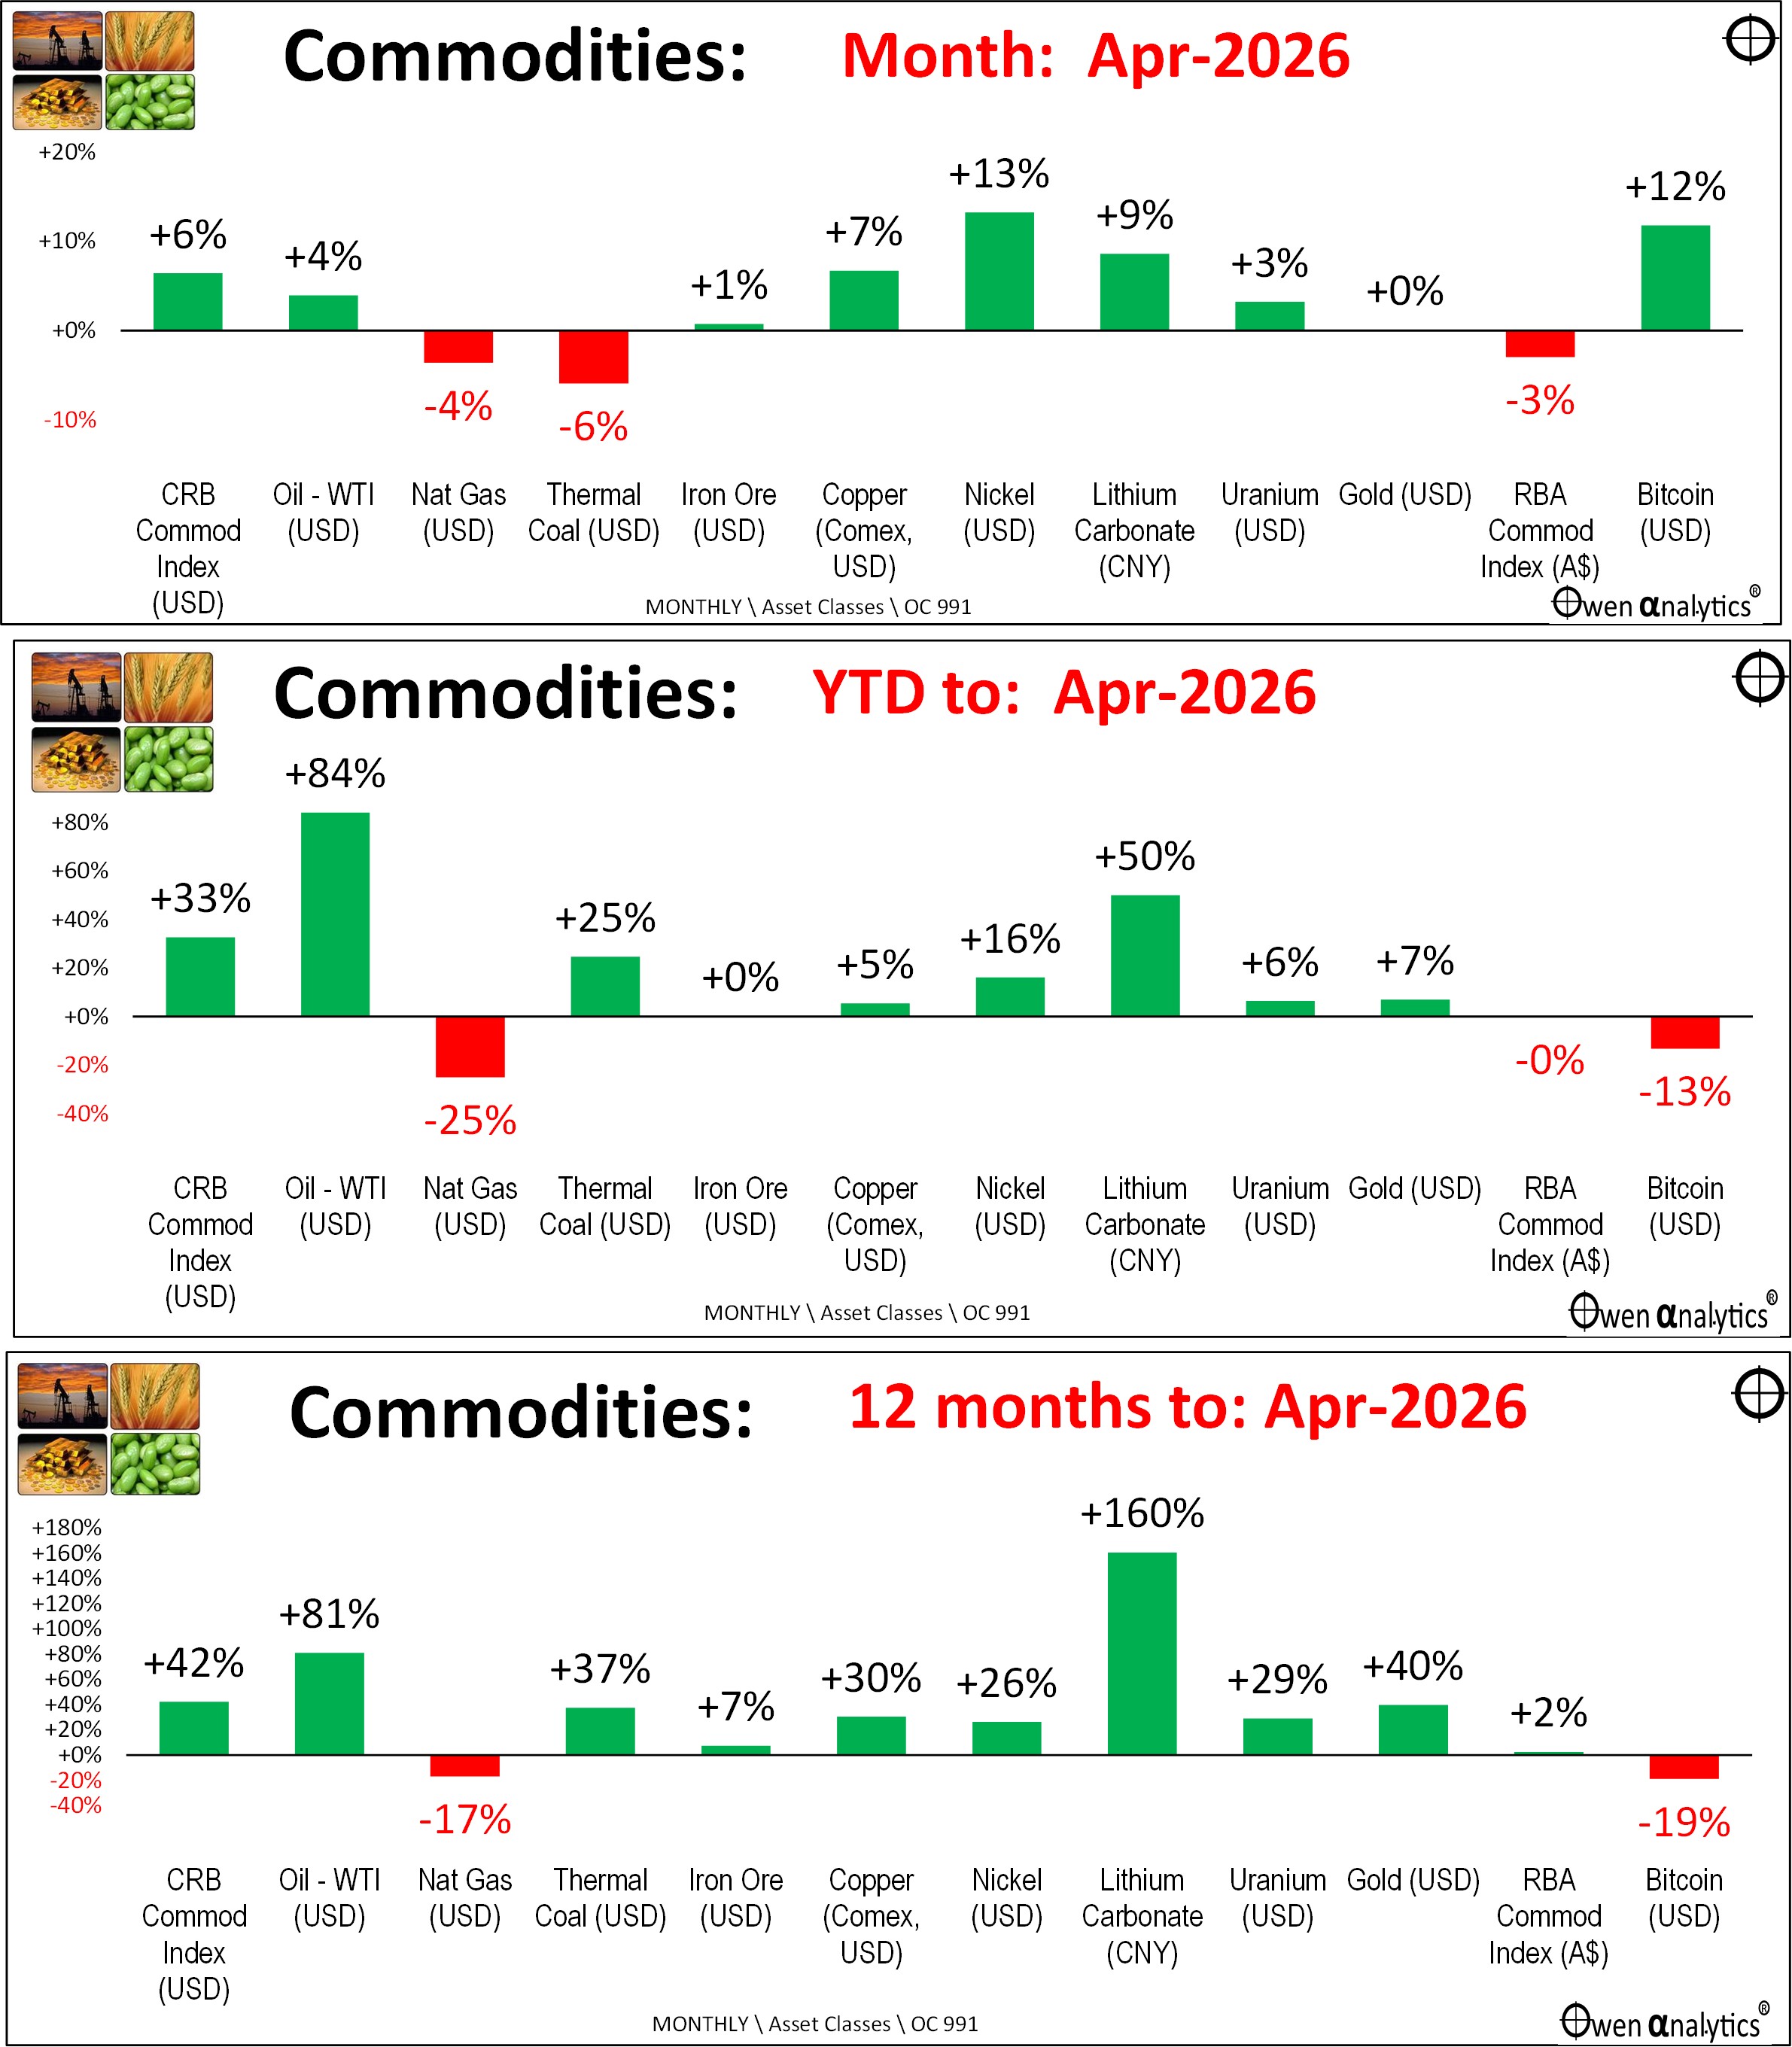
Oil prices surged +52% during the war in March, then rose a further 4% in April as the war starting to look like a stalemate, with extended Hormuz restrictions leading to higher fuel prices for longer.
Yes, oil prices are now high in Nominal (de-based paper money) terms, but they are still significantly LOWER than their 1970s peaks in Real (inflation-adjusted) terms. And the world is far less dependent on fossil fuels than it was in the 1970s.
On gold – I hold gold in my long-term ETF portfolios, and it has doubled in the past couple of years, but is up ‘only’ 7% in 2026 to date. It the best performing holding by far.
While elevated prices for fossil fuels and gold benefit ASX listed fossil fuel producers and gold miners, the most important commodity for the ASX on the whole is iron ore, where spot prices have been more or less flat for the past year. China has been trying to reduce over-production of steel and is also using its market power (which it should have done years ago) to strong-arm BHP, RIO and FMG on pricing.
The problem is that ore grades in the Pilbara are declining, and new supply is now coming out of Simandou, Guinea (RIO), further putting pressure on Pilbara volumes and prices. On top of all that, the Aussie iron ore producers are being hit by rising operating costs: wages, fuel, compliance, red/black/green tape, and now a return to 1970s-style militant industrial action after Labor’s winding back of three decades of IR reforms.
Iron ore has been the stand-out windfall for Australia since 2003, but the days of peak Pilbara iron ore are behind us.
Meanwhile, seeing this trend, BHP has turned itself into primarily a copper play – with the growth and jobs mainly in Latin America.
Bitcoin prices rose in April as the Bitcoin price follows US tech stock confidence cycles. However it has lagged everything else over the past 12 months (lower chart).
Trump’s agenda?
The following is what I said in my end of March report:
The most important factor for the direction of short-term investment markets prices will be Trump’s twists and turns on the war front (or tariff front, or any of his other hobby horses du jour). Not even Trump knows what he will say or do one minute to the next, so it is pointless trying to guess.
However, I have two fairly sound reasons for being relatively positive for share markets in the coming months.
First - Trump probably has one central aim in the short term: to retain MAGA votes in the November mid-term elections. To do that he must (1) get oil prices down, and (2) minimise the number of Americans coming back in body bags.
This points to a relatively quick end to the war. Or at least an end to disruptions in oil/gas supplies, which means opening the Strait of Hormuz to restore normal shipping.
Second – in the event of a sharp economic recession, governments of all flavours in the US, Australia and just about everywhere else no longer have any notion of fiscal discipline. They have shown in the GFC and Covid that they will literally throw ‘free’ money at anything and everything in order to retain populist votes. Politicians no longer have the stomach nor the intellectual framework for ‘tough medicine’, ‘business cases’, trade-offs, or discipline.
The longer-term consequences and downsides will be even higher debts and widening intergenerational inequity, but it supports asset prices in the short-medium term. The current global tech/everything boom is being held up by hopes of endless monetary and fiscal profligacy.
This theory remains my Base Case scenario. Trump is desperate to get out but it must be with him ‘winning’. The problem is finding something to call a ‘win’. He is now reduced to a rather tiresome tirade of threats, then backdowns, then mysterious alleged ‘negotiations’ with nameless parties on behalf of Iran about a so-called ‘deal’, then more threats, and more back-downs.
The most likely outcome is probably yet another humiliating US withdrawal dressed up as a ‘win’, but leaving a festering mess behind.
What to do in portfolios?
Let me start by repeating exactly what I wrote in my end of February monthly report, which was BEFORE the US started bombing Iran in the latest war:
“I see several themes driving markets in the medium term:
-
-
- Continued shift from rules-based order and win-win multi-lateral trade to power-based order and win-lose trade deals. Trump did not start this. The shift started in the 2010s with US/Europe letting Putin take Crimea in return for cheap gas for Germany/Europe, and US/Japan letting China militarise the South-China Sea. It has certainly accelerated under Trump. Lower cross-border trade & investment, more reliance on government subsidies & distortions, inflationary on-shoring of uneconomic industries.
- Sticky inflation - political pressure on central banks to keep rates low – populist pressure on governments to keep deficit spending. Tariffs + onshoring adding to costs/prices. Bond yields to stay elevated or even drift up further, risk of bond yield spikes, or sudden need for rate hikes, unsettling / breaking share markets.
- Share markets continue to be supported by good profit growth for now. Shares everywhere are expensive but buoyed by loose monetary & fiscal policies, plus a near certainty that governments will throw ‘free’/borrowed money at any problem.
- Commodities rally gathering pace – rising demand soaking up over-supply, ai / data centre boom (industrial metals, energy, water, land), global re-armament – especially Europe, Japan, Canada. This should support ASX market, as long as banks avoid a local recession.
- De-dollarisation fears are probably over-done, but is driving up gold, silver, but not bitcoin. US treasury yields not at risk for now (and even fell in February).
- The current boom will end one day of course. All markets everywhere, including and especially Australia, are over-priced on fundamentals, not just US-big tech. However, each boom is different and the triggers for the inevitable bust are different each time. See my recent 6-part series on share market over-pricing.
-
-
- I have not changed my asset allocation in portfolios (my own and for investment committees) and it has done rather well – beating Big Super by about 2% pa, thanks mainly to two themes - having Gold, and zero interest duration (no fixed rate bonds). A lot has happened in that time, and I have left it alone to do its work. That’s the point of an ‘all-weather’ portfolio – I don’t need to constantly worry and fiddle with it. When I get some time in the coming months, I will certainly take a look and see if I need any adjusting.”
Now, the question I posed in my end of March report – ‘Has the new war on Iran changed any of that?’
Probably not, except for two things. First, the war adds weight to my pre-existing medium-term inflation fears.
Second, the war and oil price spike just may be the trigger for the inevitably unwinding of the speculative tech boom. We knew it would end of course, but we did not yet have a trigger.
The background for the big correction may be US/global slow-down caused in part by higher fuel prices / inflation / interest rates. The trigger may be a sudden realisation in the emptiness of the extraordinary hype over tech / ai profitability, probably accompanied by contagion withing the private credit / private equity funds that are holding mountains of unsustainable debt extended to tech / ai / data centre operators, perhaps leaking into / across the US banking sector.
It will be a big correction in the order of 40-60% crashes in share markets everywhere and trillions of dollars of debt written off as worthless. What we don’t know is when.
Meanwhile, life goes on. Looking beyond the daily noise and gyrations, I am sticking to my portfolio holdings, and I will report on returns when I get some free time (a tad busy with cancer & chemo rounds these days!)
‘Till next time – safe investing and stay healthy!