Greetings fellow investors!
Here’s my quick wrap-up on global markets for serious long-term Aussie investors – including share markets, interest rates, inflation, bonds, currencies, commodities, crypto and more, plus portfolio implications.
But first - my essential 1-page snapshot chart - covering Australian and US share markets, short and long-term interest rates, inflation, and the AUD/USD exchange rate. It is my go-to chart that tells me what happened when and why, whenever answering queries from advisers, investors, doing webinars, market updates, etc.
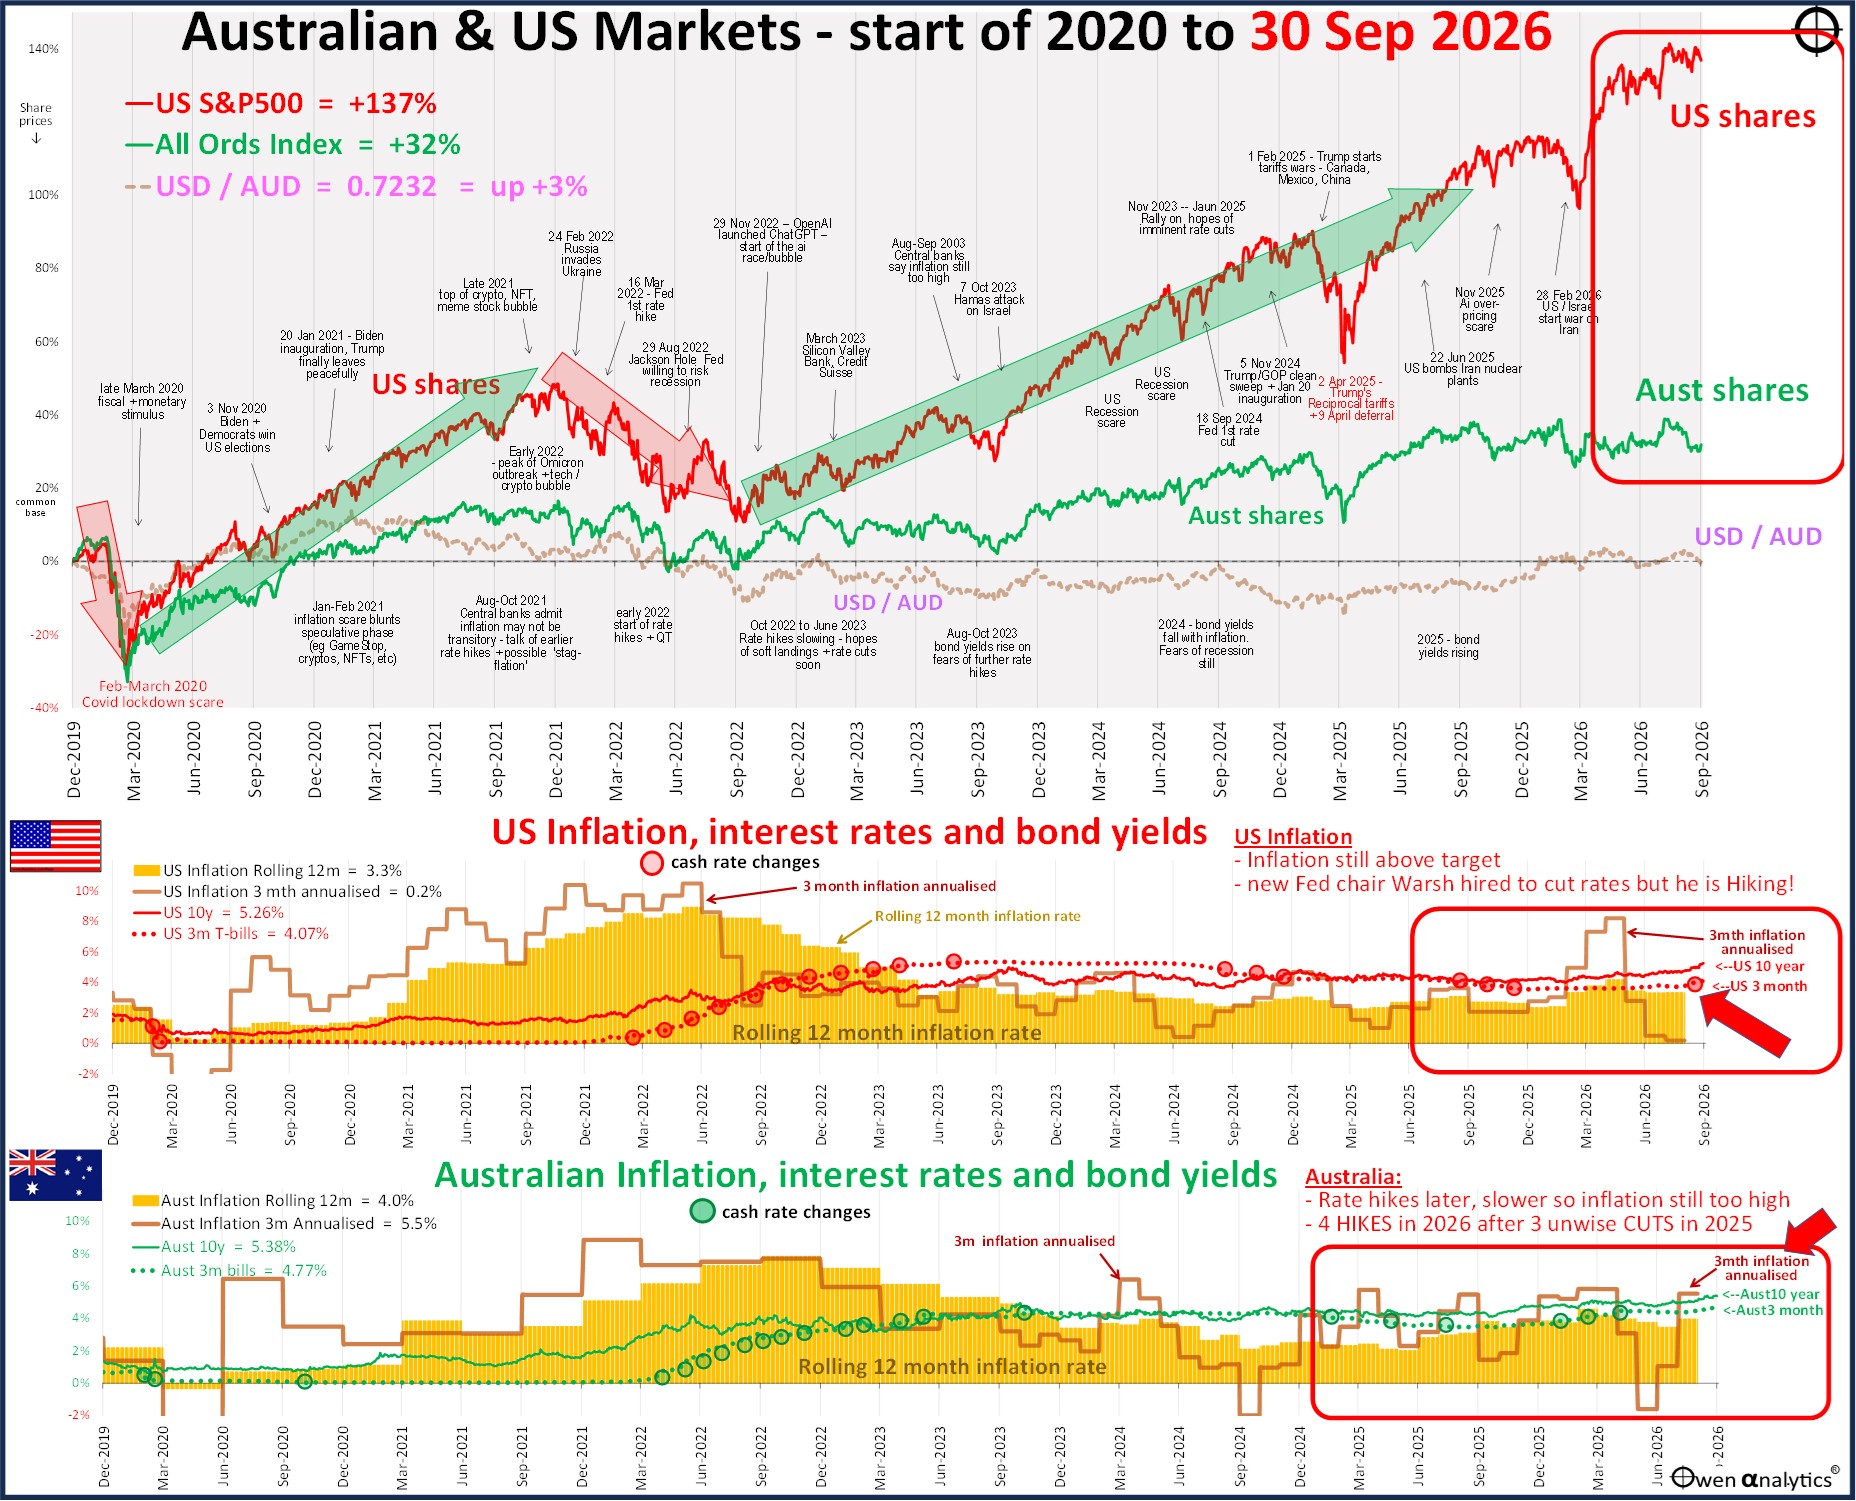
Not only does this chart have all the detail I need to answer investor questions from advisers, but even from the back of the room you can easily see the big picture on where we are for share markets, currency, inflation, long & short interest rates.
I will get into shares in a moment, but from the back of the room you can see that share markets had a minor hiccup in March this year (near top right corner of the chart – red for US, green for ASX), then were quickly back on track with new all-time record highs in the extraordinary tech/ai boom.
Bottom line – if you were rattled by the volatility and (very brief) share market falls in March 2026 or 2022 (rate hikes) or 2020 (Covid), then you ain’t seen nothin’ yet! (or you are too young to remember what a real crash looks and feels like!). There is certainly a proper correction on the way, but we’re making hay while the sun still shines!
September 2026 snapshot: Rate hikes + rising bond yields rattle markets
So far this year I have remained bullish on shares and bearish on bonds. This has worked but share markets are facing more headwinds.
Oil prices rose by another +4% in September as Trump’s war on Iran ran further out of control, with Red Sea trade also blocked. I had assumed Trump would know that he must get out of Iran to get oil prices down to retain MAGA votes in the mid-term elections (3 Nov).
Thus far I had been reasonably confident that he would find away to get out of the Middle East and get oil prices down because that would be the obvious way to retain the Senate and House. But he must find a way to make a limp US retreat look like an EPIC VICTORY!
Instead it appears he is stuck there and is resorting to crazy tactics to buy votes - eg with $5k gifts to all adult citizens (with borrowed money of course!) if the Republicans win. He could even order retailers to lower prices, or other crazy tactics. Who knows? Timing is running out. He has one month left before the mid-terms.
Meanwhile, inflation remains high. US ‘CPI’ and ‘PCE’ (Personal Consumption Expenditure, the Fed’s preferred measure) are at 3.4%. Australian inflation rose to 4% annually, and annualised 3-month 5.5% running rate.
Cash rates were hiked here and around the world. New US Fed Chair Warsh defied Trump's orders to cut rates, and started hiking rates instead.
The RBA hiked rates for a 4th time this year, but it was really a first hike as the first three just reversed the three unjustified cuts last year.
Australia still has the highest cash rate and highest inflation in developed world.
Smirking Jim Charmer continues to blame foreign wars but here are the FACTS:
-
- Inflation was already too high BEFORE Russia invaded Ukraine in Feb 2022 (3.5% annual, and 5.0% 3-month annualised running rate).
-
- And inflation was already too high BEFORE Trump started his war on Iran at the end of Feb 2026 (3.7% annual, and 5.2% running rate).
But still he smirks and carries on spending and borrowing, as Commonwealth government debt passed the A$1 trillion mark.
Global share markets were hit (down 1%) by rising short & long interest rates. Big gains in Intel +34%, Micron +11%, Nvidia +3%, Taiwan Semi +3%, Samsung Electronic +3%. Other gainers included Meta +27%, Apple +5%, and oil majors (Exxon, Shell, BP). The rest of the global share market was a sea of red ink.
The Aussie market fell -3%. Big iron ore miners (BHP, RIO, FMG) fell as iron ore prices fell -4% in China’s price war. The banks were flat as a group as more money rotated out of the still vastly over-priced CBA (most exposed to the housing meltdown) and into ANZ (least exposed to housing), Westpac & NAB. Gold miners fell as gold prices fell -8%.
Bonds had yet another shocker as yields rose everywhere. US 10-year yields ‘soared’ above 5%, shocking commentators everywhere, but I pointed out that 5% is still NOT high relative to history, logic, fundamentals, or inflation. See -
· US 10-year yields ‘soar’ above 5%. Shock Horror! But actually they’re still rather LOW relative to history, logic, fundamentals, and inflation. Get used to it! (27-Sep-2026)
Welcome to the new world of higher inflation, cash rates and bond yields. I have been out of fixed rate bonds in portfolios (mine and advised) since 2021.
Aussie house prices continued to fall, and will fall further with more rate hikes. Most of the losses in this cycle will be borne by ‘private equity’ investors (not the big banks this time). More private credit funds were hit during the month, but we’ ain’t seen nothin’ yet!
(Apologies for the brief report as I have been rather busy with post-chemo tests and biopsies).
‘Till next time – safe investing and stay healthy!
Ashley Owen
No ai. All Human.
All original research & analysis.