Greetings fellow investors!
Here’s my quick wrap-up on global markets for serious long-term Aussie investors – including share markets, interest rates, inflation, bonds, currencies, commodities, crypto and more, plus portfolio implications.
But first - my essential 1-page snapshot chart - covering Australian and US share markets, short and long-term interest rates, inflation, and the AUD/USD exchange rate. It is my go-to chart that tells me what happened when and why, whenever answering queries from advisers, investors, doing webinars, market updates, etc.
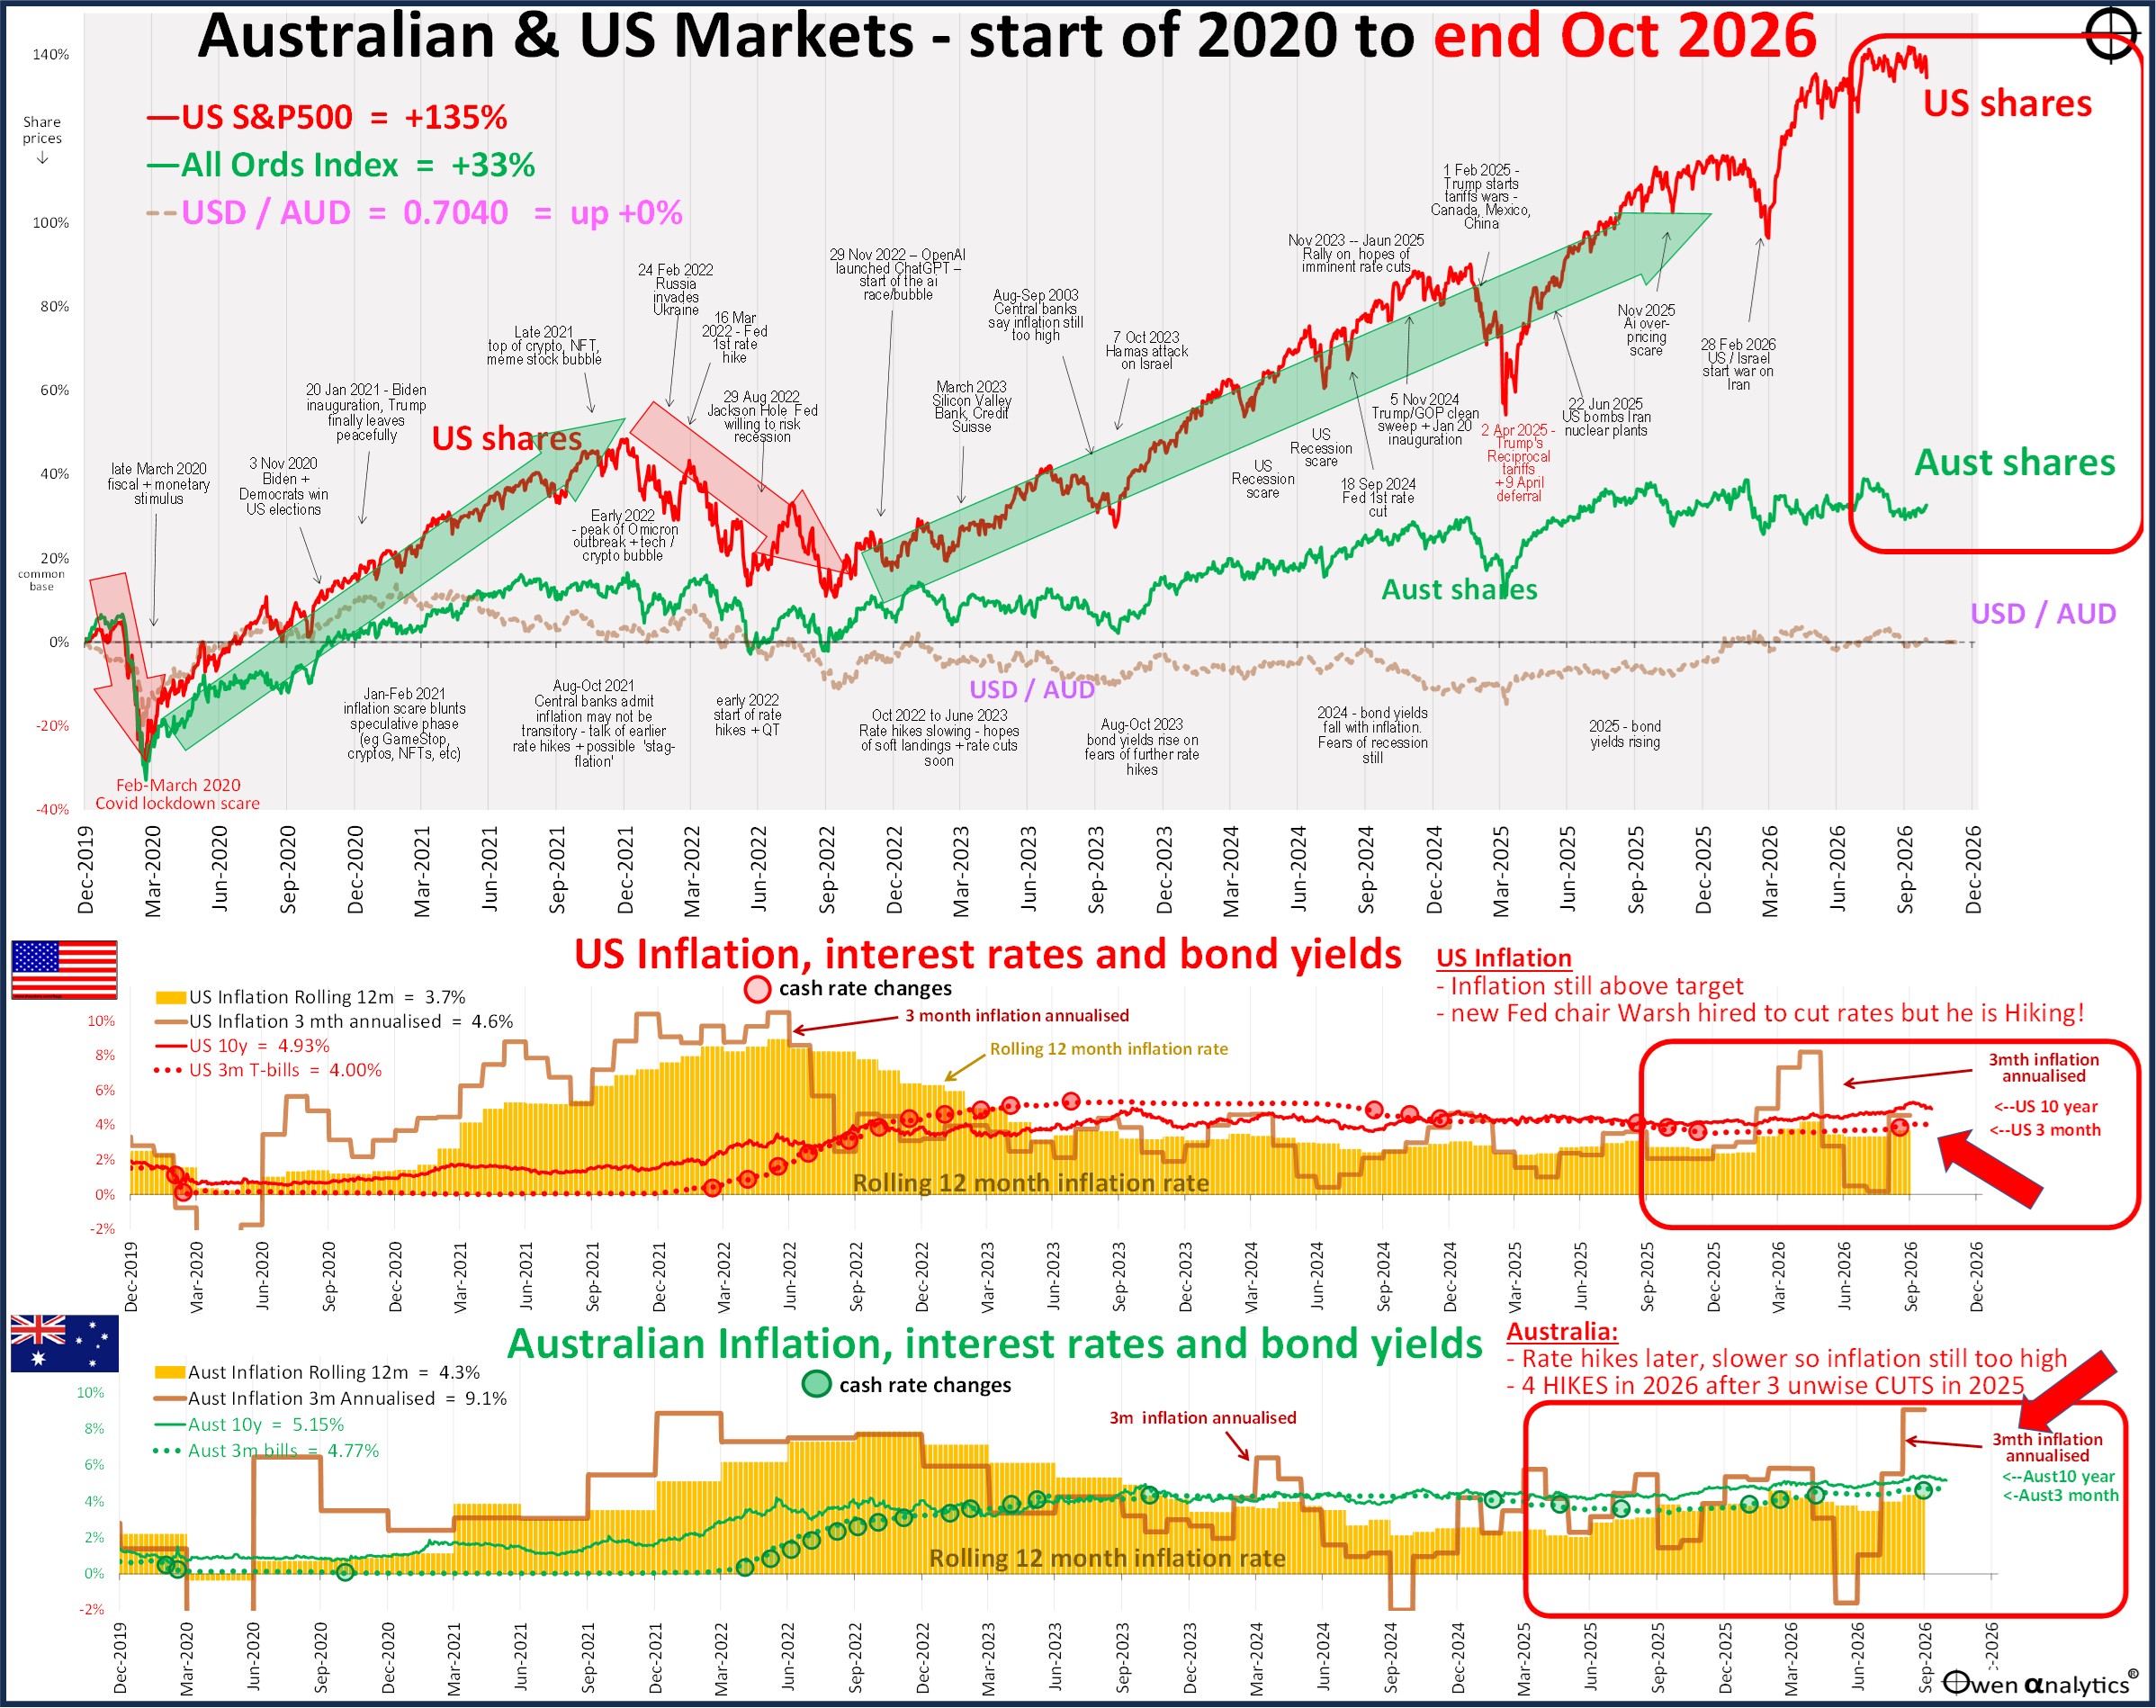
Not only does this chart have all the detail I need to answer investor questions from advisers, but even from the back of the room you can easily see the big picture on where we are for share markets, currency, inflation, long & short interest rates.
So far this year I have remained bullish on shares and bearish on bonds. This has worked but share markets are facing more headwinds.
October 2026 snapshot: Inflation troubles, Political interest rate decisions, ai wobbles
What a month!
Oil prices soared another 14%, back above US$100 in the US, and above $110 in Europe as Trump’s war on Iran drags on with ever-more twists and turns. My favourite was on 6 Oct when Trump offered to sacrifice up millions of American lives to be bombed by Iran - “Let them take out LA or San Diego. That’s a small price to pay.” (both are Democrat cities of course!)
Election impacts?
Some polls suggest Democrats may regain both the House and Senate, picking up the required 4 seats in each. I don’t think it will make much difference to financial markets because I don’t think it will make much difference to Trump. He will continue to do whatever he wants regardless, as JD Vance said: “Who’s going to stop him?”
Aside from the US election race, the main theme was the continued slow unravelling of the ai frenzy. Anthropic’s $100b capital raising will be the largest IPO raising in history, and is notable for its prospectus containing dire warnings about how it poses catastrophic threats to human survival! That's some marketing pitch!
On the other hand we had some ai data centre flops, including South Korea’s Elice (0158S0.KQ), market darling CoreWeave (CRWV) fell 37%, NextDC down 45%, and Firmus didn’t even make it to the starting line on the ASX (Firmus was never a serious ai play, just an opportunistic money grab)
Inflation
INFLATION remains too high everywhere. US CPI inflation rose to 3.7% (at a 4.6% annualised 3-month running rate), and the Fed’s preferred measure - ‘PCE’ (Personal Consumption Expenditure) is running at 3.1%. Despite firming inflation, the Fed opted not to infuriate Trump with a pre-election rate hike. Same story in NZ, where the RBNZ also bowed to political pressure and avoided a hike rate prior to next week’s NZ elections.
See –
· My Cash Rate Barometer for the US says next Fed move is UP. Trump will not be happy! Here’s how it works (23-Oct-2026)
The RBA in Australia has a worse record – with three rate CUTS in 2025 (election year) despite sticky inflation. No surprise that it had to reverse them with the first three hikes in 2026.
With no election pressure, the RBA should hike again on 3 Nov as inflation is getting away from it once again. CPI rose to 4.3% pa, with an annualised 9.1% 3-month running rate, and the RBA’s preferred measure ‘Trimmed Mean’ is at 3.7% pa, with a 4.0% 3-month annualised running rate. All very ugly.
See -
· My Cash Rate Barometer says next RBA move is UP. I have used this reliable tool for 20 years. Here’s how it works (15-Oct-2025)
Australia still has the highest cash rate and highest inflation in developed world, but smirking Jim Charmer continues to blame foreign wars! Problem is: Inflation was already too high BEFORE Russia invaded Ukraine in Feb 2022 (3.5% annual, and 5.0% running rate). And it was already too high BEFORE Trump started his war on Iran in Feb 2026 (3.7% annual, and 5.2% running rate). But still he smirks and carries on spending and borrowing, as Commonwealth debt sailed passed the A$1 trillion mark. No big deal – just add it to the credit card and let our kids and grandkids pay for it!
SHARES
Global share markets ended flat overall for the month despite gains in most stocks and sectors, especially in health care, staples, oil/gas, industrials. But these were offset by big falls in tech/chip/ai stocks, including Intel -45%, Samsung Electronic -16%, Nvidia -10%, Micron -17%, Taiwan Semi -4%, Oracle -5%, Facebook -15%, Alphabet/Google -19%, Amazon -4%, Alibaba -9%, Tencent -11, Netflix -11%.
Similar pattern on the ASX. Most major stocks were up in most sectors, especially the big banks, but miners were almost all down, with lower prices for iron ore, gold, copper, nickel, lithium. Besides miners, NextDC was the stand-out, falling 45% over backlashes against its data centres and over-confident projections.
BONDS
Bond markets had a rare positive month as yields fell back around the world on slowing growth outlooks and rising unemployment. The exception was France, where yields kept rising with its mounting debt and social unrest. Bond markets are heading for a fourth year of negative real returns. I have been out of fixed rate bonds in portfolios (mine and advised) since 2021. But all so-called ‘diversified’ Big Super funds have sizeable mandatory allocations to bonds, which is hurting returns.
Aussie house prices fell further across all cities, and will fall further with more rate hikes. Most of the bad debt losses in this cycle will be borne by ‘private equity’ investors (not the big banks this time). More private credit funds hit problems during the month, but we ain’t seen nothin’ yet!
‘Till next time – safe investing and stay healthy!
Ashley Owen
No ai. All Human.
All original research & analysis.