Background - I track and analyse thousands of data points across all markets and asset classes, but the most important barometers and drivers of local and global markets for my day-to-day purposes (answering questions from media & colleagues, and mentoring advisors & portfolio managers in managing their client portfolios and client comms) are the following key items:
- Share markets (Australia & US),
-
- the Aussie market as it still anchors most long-term diversified portfolios
- the US market as it dominates (financial and sentiment) global markets
- Treasury bonds (Aus & US)
-
- because fixed rate bonds still make up a sizeable chunk in most long-term diversified portfolios,
- and because treasury yields reflect expectations of future inflation and interest rates, which directly affect other asset classes including shares, real estate, commodities, currencies.
- Currencies (AUD & USD)
-
- The AUD because it is a ‘risk’ currency, which it ALWAYS falls in general global sell-offs as global (mainly US) investors dump foreign risky assets and retreat to the safety of the US. Conversely, but in general global rebounds and booms, the AUD usually (but not always) rises as foreign investors (mainly US) venture back in.
- The USD as it is the global reserve currency on which everything else is anchored,
- Oil – because fuel prices filter directly or indirectly into just about every inflation category, and inflation expectations drive interest rate decisions and bond yields, which in turn affect the pricing of all other assets.
- Gold – as it is the original ‘hard currency’ and it is still a good proxy measure for how investors, governments, and central banks are felling about future inflation and political / civil / military unrest and disruptions.
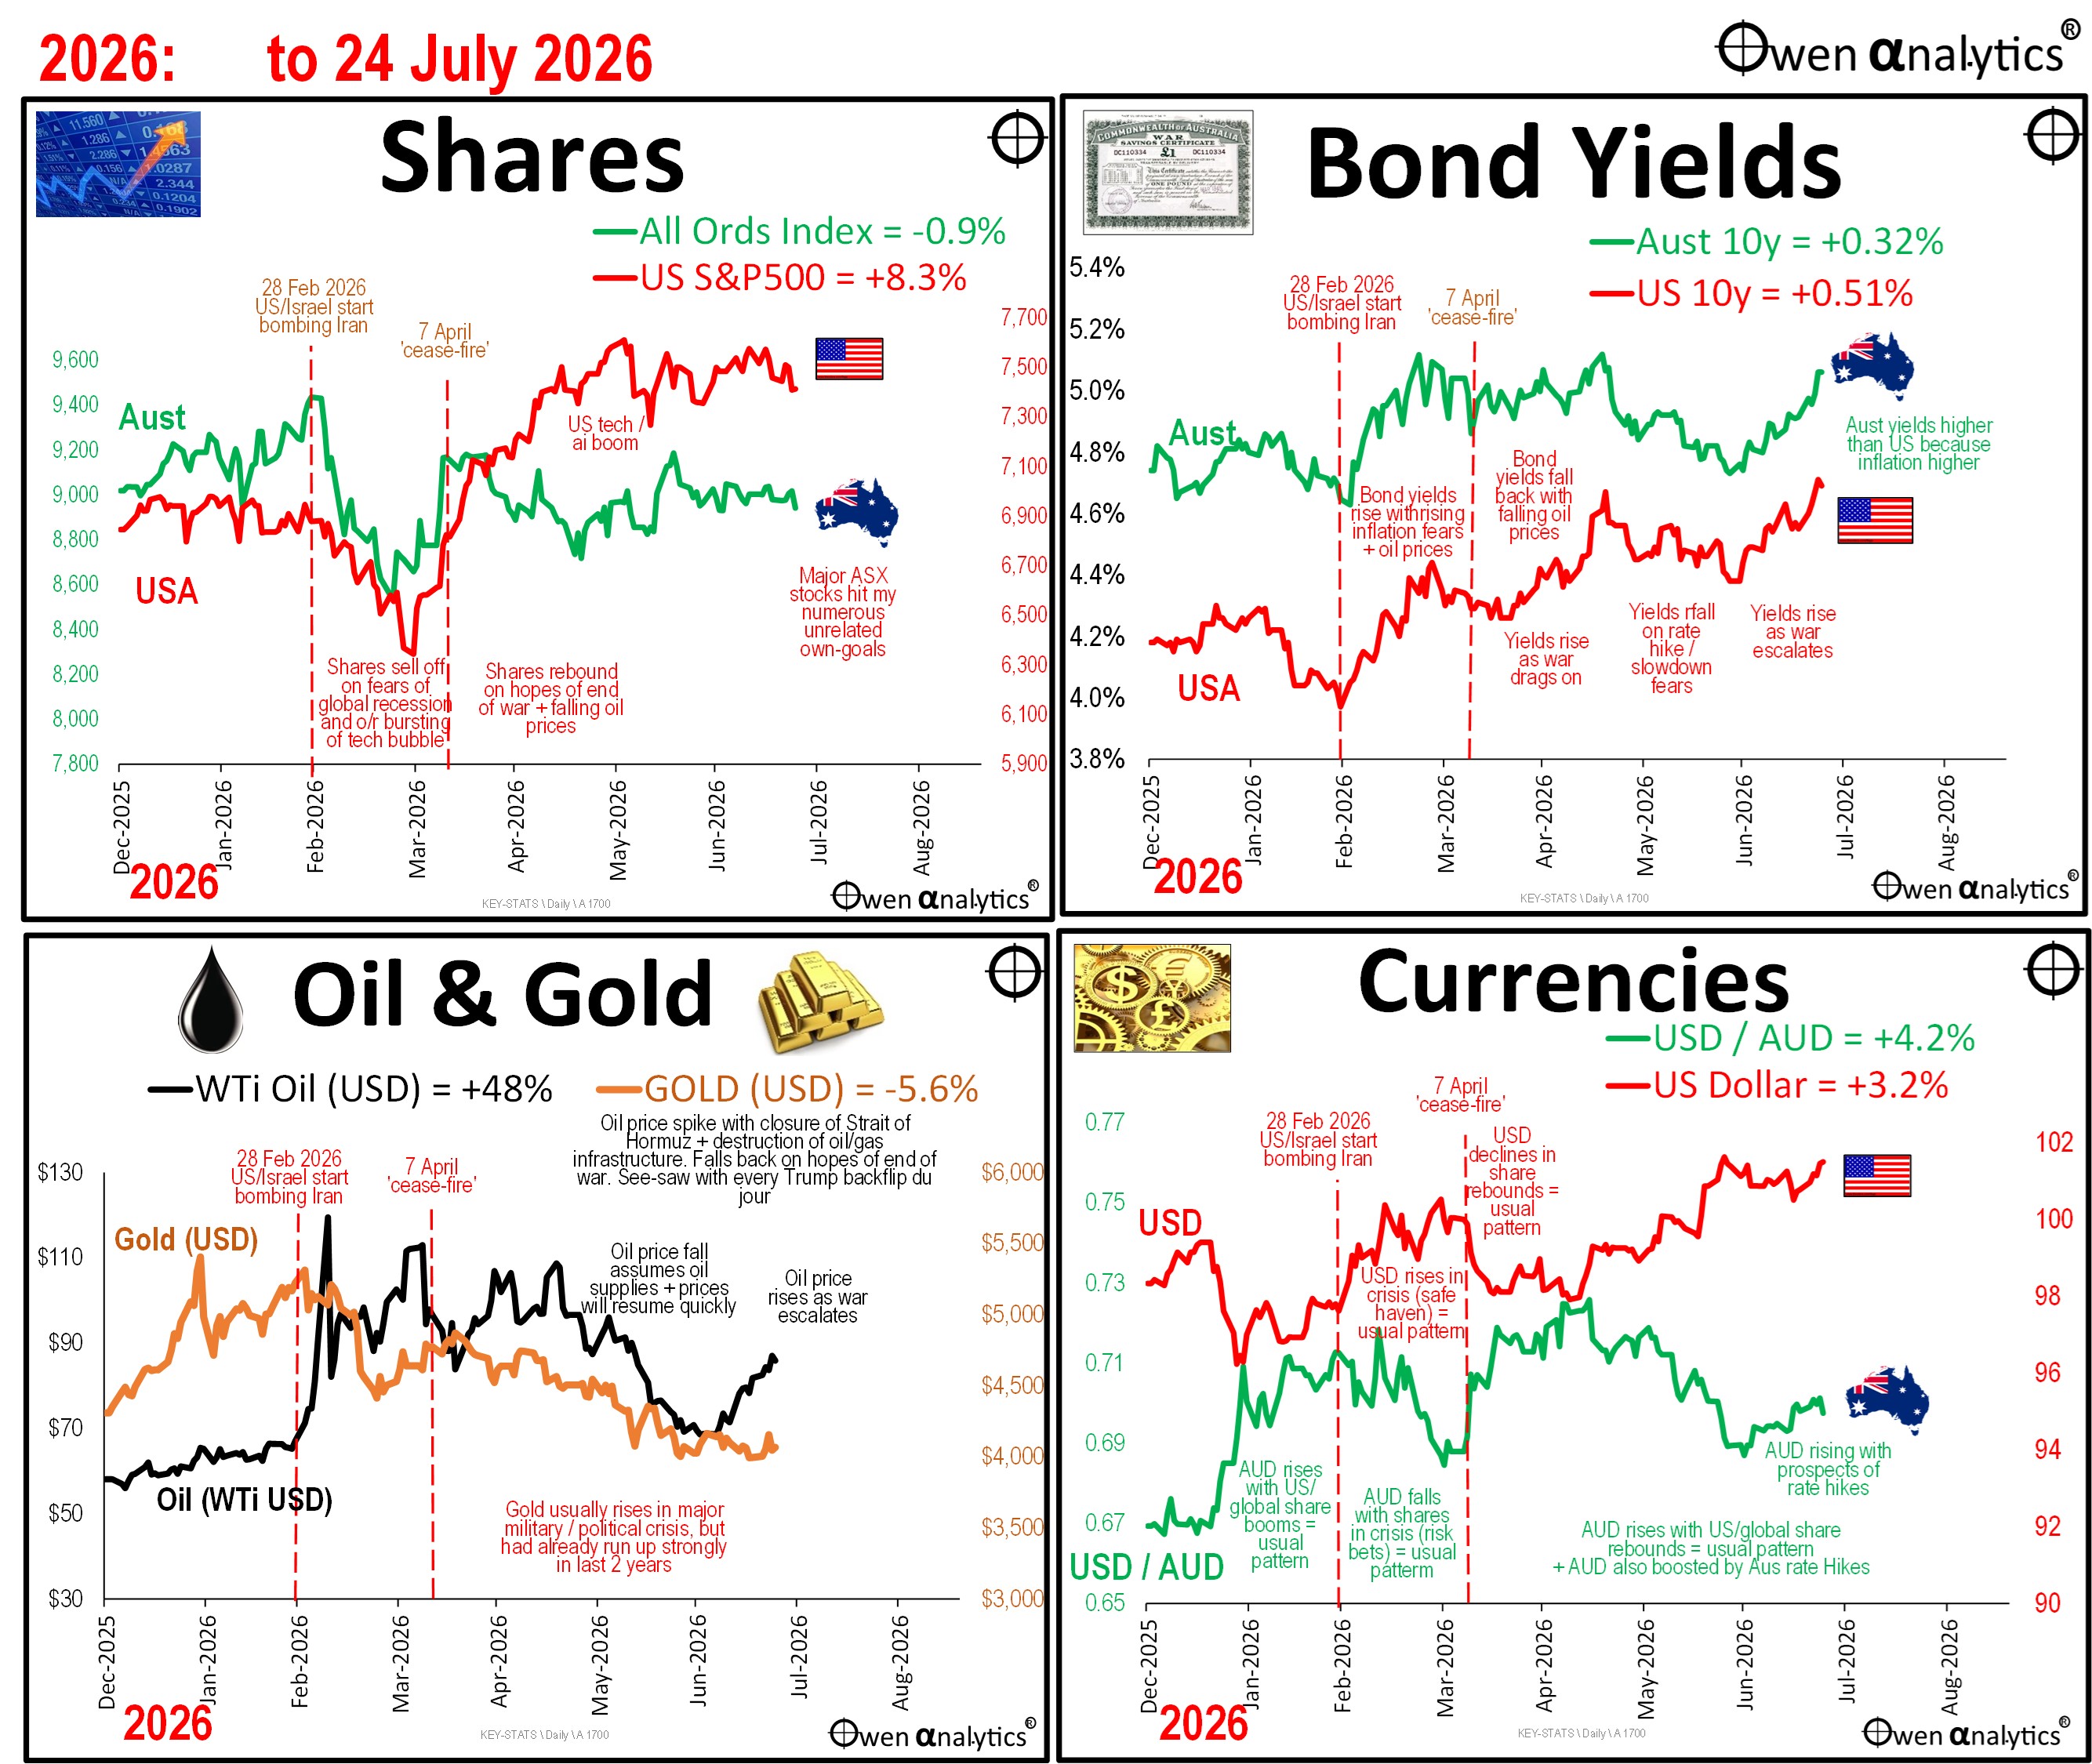
This handy set of four charts track changes in these key markets since the start of 2026, and is my quick go-to daily reference point.
Owen’s Market Pulse- 25 July 2026: War escalation lifts oil, gold, bonds yields, but hurts share markets
Here’s my latest quick take on the week’s activity on local & global markets for long-term Aussie investors:
In a nutshell: Oil prices surged as the US/Iran war escalated, sending gold, bond yields and short term interest rates higher on rising outlooks for inflation and interest rates. These, plus Trump’s new tariff attacks, sent share markets further south.
SHARES - The ASX market ended down a fraction for the week, as money rotated out of the big iron ore miners (on weak iron ore prices) and into the big banks. Gold miners posted gains on a lift in gold prices, Woodside surged on the oil price spike. CSL had another bad week. Goodman (now an ai/data centre bet) followed the global ai centre slide.
US share markets fell, with festering fears of over-investment in ai that will fail to generate returns. US inflation is easing but the latest oil price spike will end that.
Chip makers Nvidia, Micron and AMD gained for the week but the chief chip buyers (eg Amazon, Google, Meta, Tesla, Palantir) all fell. They are now chewing up more than all of their operating cash flows (plus borrowing even more) to bet on an ai future. SpaceX had another shocker and is now -15% below its crazy IPO price – no surprises there! Talk about top-of-the-market bad timing for all those FOMO punters.
However, the S&P500 and Nasdaq are both still up 8% so far this year, but the likes of Microsoft, Tesla and Palantir are down big time.
BONDS - Australian yields kept rising for a fourth straight week and are now above 5% on inflation fears due to escalating government spending/debt binges (Federal & State) with no sign of restraint or discipline. Short rates also edged up further, indicating higher rates ahead.
US yields also rose further with government spending / debt / inflation fears outweighing slowdown fears as higher fuel prices drag on spending and confidence. It will be another shocker of a year for bond holders everywhere. (I have had no fixed rate bonds in my own or advised portfolios since 2021.)
OIL - WTi rose back above $90 (and above $100 in Europe) during the week as Iran-backed Houthi rebels in Yemen disrupted oil shipments through the Bab el-Mandep Strait (the alternate Red Sea route with the Strait of Hormuz closed).
GOLD – gained +2% for the week on rising Middle-East risks, boosting Aussie gold miners.
CURRENCIES – The AUD ended flat for the week. It has been rising steadily since March on rising prospects of another rate hike soon, which would attract more money into Australia and push up the dollar.
The US dollar index also rose a fraction for the week, consistent with share markets falling and prospects of rate hikes.
My take - despite escalations in the US/Iran war, I remain relatively positive in the short-term (lower oil prices, which should support share markets) because Trump’s primary immediate goal must be to do whatever it takes to get fuel prices down in time to retain MAGA votes in the November mid-term elections.
He knows he must retain both the House and Senate in order to retain unfettered power in the next two years to execute his agenda to achieve his goal of becoming the greatest leader in the history of the world (in his own mind anyway).
Stay tuned!
‘Till next time – happy investing and stay healthy!